Equitable Heads Into Q3 Needing Alternatives And Flows To Back Its Merger-Year Momentum
Equitable Holdings enters its third-quarter report with an unusual mix of confidence and unfinished business. Last quarter, the CoreBridge merger cleared its biggest hurdles, organic flows turned positive across the franchise, and management raised several operating targets. It also quietly lowered its sights, steering its multiyear earnings growth ambition to the low end of its 12% to 15% range rather than the midpoint. The stock has rallied since then, so this report must show that the improving pieces are strong enough to outweigh the soft spots.
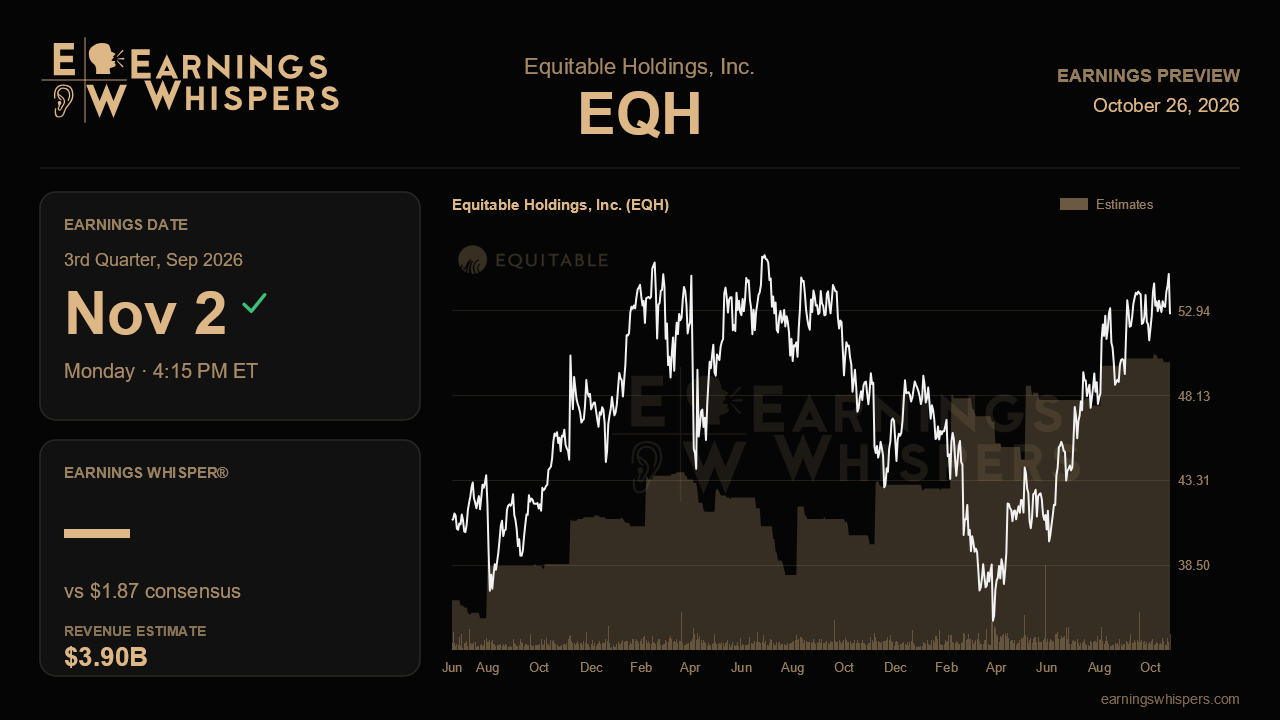
Wall Street expects earnings of $1.87 per share when the company reports after the close on November 2, up about 26% from $1.48 a year ago and ahead of last quarter's $1.70. That would extend the 24% to 25% growth pace of the first half, well above management's full-year marker of better than 15%. Consensus revenue of $3.90 billion implies growth of roughly 169%, but reported revenue at life insurers can swing sharply with accounting effects, so that figure says less about the business than the per-share earnings line. The EPS estimate is the real bar, and it assumes the first-half pace holds.
The most direct test of last quarter's story sits at AllianceBernstein. After net outflows of $7.1 billion in the first quarter, AB swung to $0.8 billion of inflows in the second, helped by a $9 billion sub-advisory mandate moved over from Equitable's separate accounts. The $12 billion commercial mortgage loan book that onboarded in July should now show up in a full quarter of assets, and management flagged a further $14 billion unfunded pipeline. Evidence that this pipeline is funding, and that third-party flows are positive beyond the internal transfers, would validate the narrative. The tradeoff is fee rate: AB's base fee rate slipped to 37.7 basis points on mix, and the mortgage assets carry below-average fees, so further erosion would temper the benefit of higher assets. With the performance fee outlook raised twice, to $115 million to $135 million, another lift would be a welcome but higher hurdle.
In Retirement, management said core spreads should hold near 174 basis points rather than compress further. A stable reading would reinforce that improvement; renewed slippage would undercut one of last quarter's cleaner positives. The bigger swing factor remains alternative investment returns, which ran at roughly 1% annualized in the second quarter against an original 8% to 9% expectation. Management already said the full year will fall short, so investors need to see whether third-quarter marks begin to recover. Corporate and Other is another pressure point, after a $106 million loss excluding notables ran above the pace implied by the $350 million to $400 million annual guide, driven by stock compensation accruals and large mortality claims. With the shares up again, the stock-comp drag may not disappear.
Capital return should be supportive. Buybacks resumed forcefully after the merger blackout, with $366 million repurchased at a 92% payout, and the employee benefits sale to The Hartford frees capital. Any update on the year-end CoreBridge close, integration, and the targeted move of $100 billion of CoreBridge assets to AB will matter, though revenue synergies are not expected to be quantified until a 2027 investor day.
The market has already rewarded the setup. Shares have gained 9.4% since the last report while the S&P 500 fell 2.1%, and the stock trades near $52.75, comfortably above its 200-day average of $45.70 and in the upper half of a post-earnings range that sits entirely above the prior quarter's. Sentiment has improved to 34.3% bullish from 12.5% last quarter. That optimism raises the stakes: Equitable needs to show that flows, spreads, and buybacks can carry earnings while alternatives remain weak, or the lowered growth target could start to look like the more telling signal.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 11 hours | |
| Sep-30 | |
| Sep-25 | |
| Sep-25 | |
| Sep-02 | |
| Sep-01 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-30 | |
| Jul-22 | |
| Jul-14 | |
| Jul-01 | |
| Jun-25 | |
| May-12 |
