HealthStream Rallies Into Q3 As Investment Ramp Tests Its Reaccelerating Growth Story
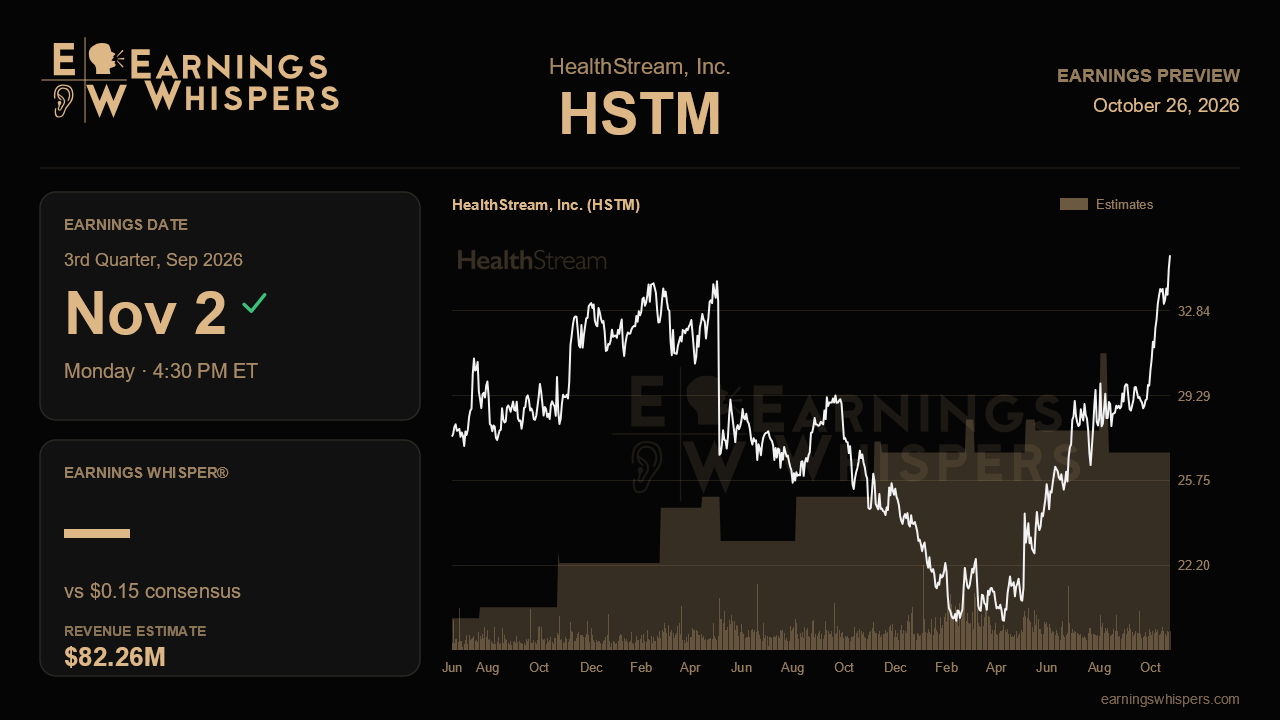
HealthStream heads into its third-quarter report with a stock that has run 22% since its last update and a management team that has already told Wall Street the next few months will look slower and less profitable. That combination sets up an unusual test. The company delivered four straight quarters of accelerating revenue growth, raised its full-year outlook, and then deliberately leaned into spending. The question now is whether the market has priced in the acceleration while overlooking the planned pause.
Consensus calls for earnings of $0.15 per share on revenue of $82.3 million when results arrive after the close on November 2. Revenue would be up 7.6% from a year ago, in line with management's guidance for roughly 8% growth this quarter, while earnings are expected to fall 25% from $0.20. That EPS decline is not a sign of trouble so much as the bill coming due for choices management made openly: 15 positions added beyond budget to expand its career networks business, heavier trade-show activity, and higher professional-service costs. Management pointed to an adjusted EBITDA margin near 22%, down from 24.6% in the second quarter, and trimmed its full-year net income range to $19.5 million to $22.2 million even as it lifted revenue guidance to $327 million to $332 million and adjusted EBITDA to $74 million to $78 million.
The sequential math matters. Second-quarter revenue of $83.7 million included a one-time $2 million contingent-fee catch-up, so the underlying run rate was closer to $81.7 million. The $82.3 million consensus therefore implies modest genuine sequential progress rather than a step backward, even though the headline number will look lower. Notably, the Street's full-year estimate of $326.9 million sits just beneath the floor of management's raised range, a sign that analysts remain cautious about the second half. A quarter that lands comfortably above $82.3 million would make the low end of guidance look conservative and could pull estimates up.
Under the hood, the product mix deserves close scrutiny. CredentialStream growth has cooled steadily, from 23% to 21% to 19% to 14% over the last four quarters, and Competency Suite slowed to 12%. Further deceleration in those flagship products would undercut the acceleration narrative, while stability would suggest the slowdown was a normalization. ShiftWizard, growing about 30%, and My Clinical Exchange, up 29%, are the faster engines, and the latter is where the new hiring is aimed. Remaining performance obligations, which have drifted from $691 million to $687 million to $685 million over three quarters, need to resume climbing to support claims that larger bundled deals, including a $10 million-plus resuscitation suite contract, are adding to the backlog. Investors should also expect updates on the cybersecurity incident disclosed in July, the continued erosion of legacy credentialing and scheduling revenue, and any early signs that Medicaid pressure or expiring ACA subsidies are squeezing hospital budgets.
Sentiment has soured even as the shares have climbed. Bearish readings rose to 57.2% from 42.4% ahead of the last report, suggesting skepticism that the rally is justified by a quarter guided to be softer. Yet the stock, at $35.16, sits well above its 200-day moving average of $25.27 and within a whisker of its post-earnings high of $35.23, effectively testing a breakout from a range that has shifted sharply higher than the prior quarter's $21.69 to $30.00 band. That leaves little cushion for disappointment.
Ultimately, this report will be judged less on the expected earnings dip than on whether the spending is buying durable growth. If underlying revenue holds near 8%, backlog turns higher and management reaffirms or nudges its outlook, the investment ramp will look like a confident bet. If core product growth keeps fading while costs climb, the rally may have gotten ahead of the business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours | |
| Sep-15 | |
| Sep-14 | |
| Aug-11 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-23 | |
| May-04 | |
| May-04 | |
| Apr-21 | |
| Mar-26 | |
| Mar-13 | |
| Mar-02 |
