Innovative Industrial's Rebuilt Balance Sheet Faces A Shrinking Rent Roll In Q3
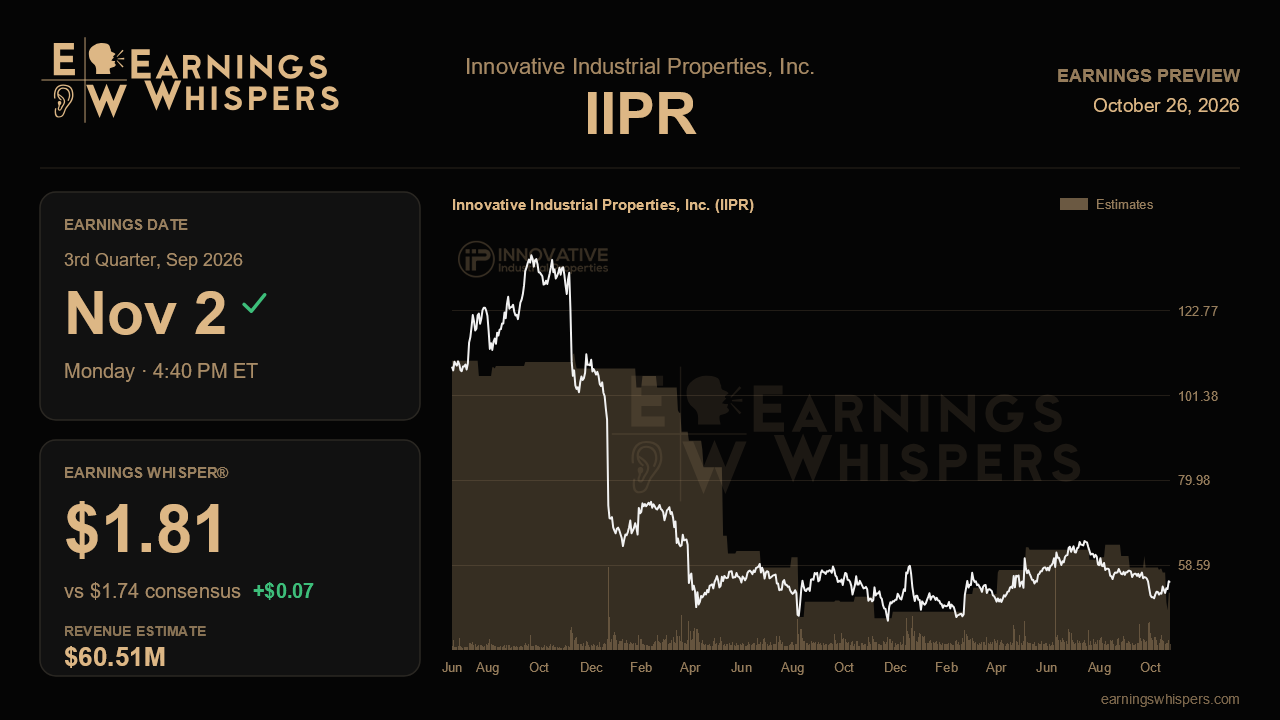
Innovative Industrial Properties spent the past year fixing its balance sheet, and by last quarter's call management was ready to talk about growth again. The problem is that the income statement has not caught up with the story. Revenue has slid for three straight quarters as payments from defaulted cannabis tenants dry up, and the space the company has re-leased will not pay rent for months. The third-quarter report, due after the close on November 2, is less about whether the company can hit a number and more about whether the revenue decline is close to bottoming.
The Street expects non-GAAP earnings of $1.74 a share, the same as last quarter and slightly above the $1.71 posted a year ago. Revenue is forecast at $60.5 million, down from $63.3 million in the second quarter and 6.5% below the year-earlier $64.7 million. That gap is the heart of the setup. Analysts are modeling a meaningful drop in rent while assuming per-share earnings hold steady. That only works if the company's recent capital moves carry real weight: the $80.5 million share buyback shrinks the share count, the final IQHQ life-science tranche earns more than 14% against financing near 6%, and the $49 million of seller financing on the $88.5 million Vireo sale in New York pays 15%. The Earnings Whisper sits at $1.81, about 4% above consensus. That is a meaningful gap, and it suggests some investors think those offsets will more than cover lost rent. The company has not issued fresh formal guidance, so the bar is set by analysts rather than management.
The prior call left a clear checklist. Management pointed to roughly 877,000 square feet of gross leasing across executed leases and the Forefront agreements, but it also warned of a 9- to 12-month-plus lag before those leases start paying rent. Investors should look for evidence that the lag is not stretching: specific commencement dates, any early rent starts, and whether new leasing keeps building on the 389,000 square feet signed in the first half. The new drag is the expected return of 593,000 square feet of Florida space from Parallel. If the company has already lined up interest in those buildings, the backfill burden looks manageable. If the space sits idle with no clear timeline, the earnings trough could last longer than the growth narrative implies.
Interest costs are the other swing factor. Net debt to adjusted EBITDA rose to 1.7x from 1.1x as the company added the $402.5 million of 6% exchangeable notes and secured term loans. That is still low leverage for a REIT. Even so, a full quarter of higher interest expense will test whether the IQHQ and seller-financing income is actually accretive or simply plugs a hole. Second-quarter AFFO per share already slipped to $1.83 from $1.88, so another step down would raise questions about dividend coverage.
Sentiment has warmed. Readings went from strongly bearish before last quarter's report to roughly neutral now. The stock has not followed. Shares are down 6.2% since the last report, against a flat S&P 500, and at $54.21 they sit just below the 200-day moving average. The stock is trading in the lower half of a post-earnings range of $49.44 to $60.70, which is itself well below the prior quarter's band. The market is crediting the safer balance sheet but declining to pay up for growth it cannot yet see.
Ultimately, the report has to show that $60 million or so of quarterly revenue is the floor rather than a waypoint. If management can tie the leasing pipeline to concrete rent commencements in 2027 and show progress on the Parallel space, the return-to-growth thesis holds. If revenue keeps falling with no visible offset, the stronger balance sheet will look like it is simply buying time.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-14 | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Sep-15 | |
| Aug-26 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-20 | |
| Jun-15 | |
| Jun-10 | |
| Jun-09 | |
| May-26 |
