MSA Safety's Autronica Debut Meets A Promised Margin Dip As Fire Orders Face Test
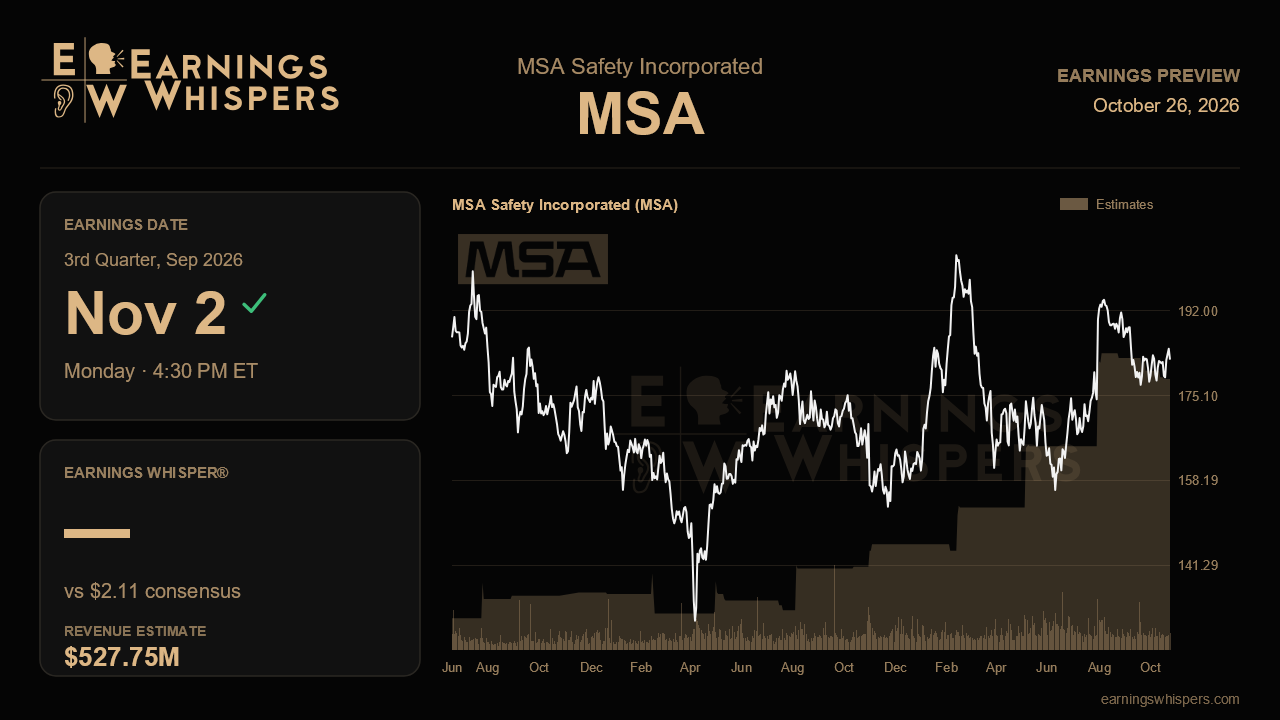
MSA Safety enters its third-quarter report with a peculiar setup: revenue is expected to jump, earnings per share are expected to fall from last quarter, and management already told investors why. After a second quarter in which adjusted EPS climbed 24% and gross margin expanded nearly three percentage points, the company warned that delayed input-cost inflation would trim second-half profitability just as the newly closed Autronica fire and security deal starts adding sales and interest expense. The Nov. 2 report, due after the close, is the first real check on whether that warning was conservative housekeeping or the start of a less flattering trend.
Wall Street is looking for EPS of $2.11 on revenue of $527.8 million. That works out to 8.8% earnings growth and 12.7% sales growth from a year ago, but a meaningful step down from the $2.40 posted last quarter. The revenue figure leans heavily on Autronica, which generated roughly $160 million in sales last year, or about $40 million a quarter. Strip that out and consensus implies organic growth in the low-to-mid single digits, broadly consistent with the mid-single-digit organic outlook management reaffirmed rather than raised. The gap between sales and earnings growth reflects two known headwinds: interest expense guidance that jumped to $40 million to $43 million on acquisition financing, and a full-year gross margin band of 47.5% to 48.5%. Because the first half ran well above the midpoint, that band implies a noticeably softer second half, so a quarterly margin in the high-40s would be on plan rather than alarming.
The more interesting questions sit beneath the margin line. Fire service, the company's swing segment, slipped 2% organically last quarter as federal Assistance to Firefighters Grant orders arrived slowly while the Department of Homeland Security was shut until late May. Management said order activity accelerated through June and July and framed fire service as inflecting into 2027. Evidence of that turn, in orders and backlog more than in revenue, would validate the bullish tone; another quarter of grant-timing excuses would chip away at it. Industrial PPE, which surged 16% on Type 2 helmet demand in the Americas and ballistic helmets in Europe, needs to show that strength was not a one-quarter spike. Connected products matter too: MSA Plus reached 14% of portable sales, and the new Altair IO6 was tracking ahead of plan.
Risks flagged last quarter remain live. Fixed and international detection were hurt by the Middle East conflict, which cost about 1.5 points of first-half revenue, and electronic-component supply pressure was forcing inventory builds. Any worsening in those areas, or a margin taper deeper than the guided moderate dip, would challenge the idea that the first half marked a durable inflection. Investors should also note that M&C results are now folded into organic growth, making the segment picture somewhat less transparent.
Sentiment has warmed noticeably, moving from deeply bearish before last quarter's report to only mildly bearish now. The stock has not followed, slipping 0.6% since the last report while the S&P 500 rose 2.1%. At about $182, shares sit above their 200-day average near $178 and in the lower half of a post-earnings range spanning roughly $175 to $197, a range set well above the prior quarter's. That suggests the market banked the second-quarter improvement but is waiting for proof before paying up.
The central issue is whether MSA can absorb its telegraphed margin squeeze while showing that demand, especially fire service orders, is genuinely broadening. If the taper lands within guidance and grant-driven orders confirm the summer acceleration, the improving narrative stays intact and Autronica becomes upside rather than a distraction. If orders stall again, the margin dip will look less like timing and more like the new normal.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-22 | |
| Oct-20 | |
| Sep-23 | |
| Sep-16 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-03 | |
| Aug-12 | |
| Aug-03 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-21 |
