Pampa Energia Faces A Rincon De Aranda Recovery Test After A Record Quarter
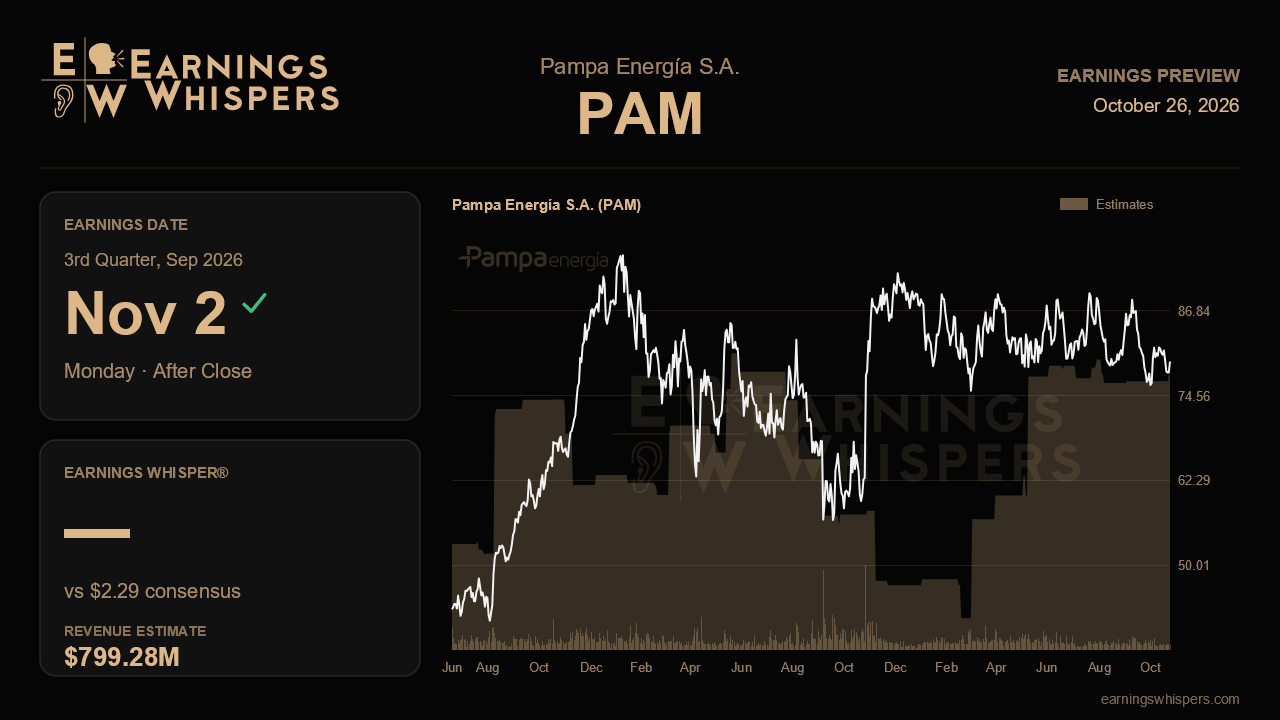
Pampa Energía heads into its September-quarter report with an awkward mix of momentum and doubt. Last quarter delivered record production, record adjusted EBITDA of $415 million and a board-approved $2.7 billion urea plant. Yet the stock has slipped 8.6% since then while the broader market was flat. The report due after the close on November 2 needs to show that last quarter's weak spots were temporary. The biggest of those was the dip in output at the Rincón de Aranda shale oil block.
The Street is looking for earnings of $2.29 per share on revenue of $799.3 million. That would be roughly a fivefold jump in EPS from the year-ago $0.42, with sales up about 35%. Even so, the comparison is less heroic than it looks. Consensus revenue sits above last quarter's $746 million, but the EPS estimate sits well below the $3.21 Pampa just posted. Analysts are effectively assuming some normalization in below-the-line items or margins. That leaves room for an upside surprise if operations cooperate. Management did not issue formal company-wide guidance, so the most concrete yardstick is power generation. Pampa targeted roughly $600 million of power EBITDA for the year, with $299 million already banked in the first half. It also said the third quarter should run higher because of Argentina's winter demand.
Oil is the swing factor. Rincón de Aranda's exit rate fell to about 16,000 barrels a day last quarter, down from more than 21,000 in the prior quarter. Management choked back wells to avoid frac interference, completed 10 new wells in July and tied them in during August. If the recovery is real, this quarter should show volumes climbing back decisively toward the 28,000-barrel year-end target. A muted rebound would cast doubt on the 45,000-barrel plateau planned for 2027 and on the investment case behind the newly granted RIGI status. Lifting costs deserve equal attention. Management expected them to exit near $10 a barrel while a second treatment facility is commissioned, before easing toward $5 next year. Costs creeping above that range would undercut the margin story just as volumes are supposed to scale.
Pricing adds another layer. Hedges held Pampa's realized crude price to about $59 a barrel last quarter, against roughly $91 unhedged. That cost the company around $64 million. With the book hedged about a year forward near $67 Brent, investors should not expect realizations to catch up with spot prices quickly. Power also has its own headwinds, which will test whether the winter boost can offset them. These include maturing Energía Plus contracts, the exit of the Iwiles hydro concession at the end of July, and outages at several units. Management itself called the petrochemical strength circumstantial and tied to the war, so a fade there would not be alarming.
The balance sheet story looks solid on paper, with $1.3 billion in cash and net leverage of 1.4 times. The question is how quickly that cushion erodes. Capex is running near $1 billion this year, and the urea plant will require about $1.4 billion of equity over the coming years. Any update on closing the project financing, targeted at roughly 60% debt, would help ease concerns about funding the plant.
Sentiment has cooled noticeably, with bullish readings falling to 4.1% from 24.5% ahead of the last report. The stock trades at $79.50, below its 200-day moving average of $82.67. That leaves it in the lower half of its post-earnings range of $75 to $88.83. Expectations are therefore subdued rather than stretched. Ultimately, the narrative hinges on Rincón de Aranda. Clear evidence that production has rebounded, with costs under control, would validate management's growth trajectory and give the market a reason to revisit the recent selloff. Another stall would make last quarter's record look like a peak rather than a new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| May-06 | |
| May-06 | |
| Apr-09 | |
| Mar-03 | |
| Mar-02 | |
| Mar-02 | |
| Nov-07 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-08 |
