Sabra Must Show Its Senior Housing Engine Can Outrun The Lost RCA Loan Income
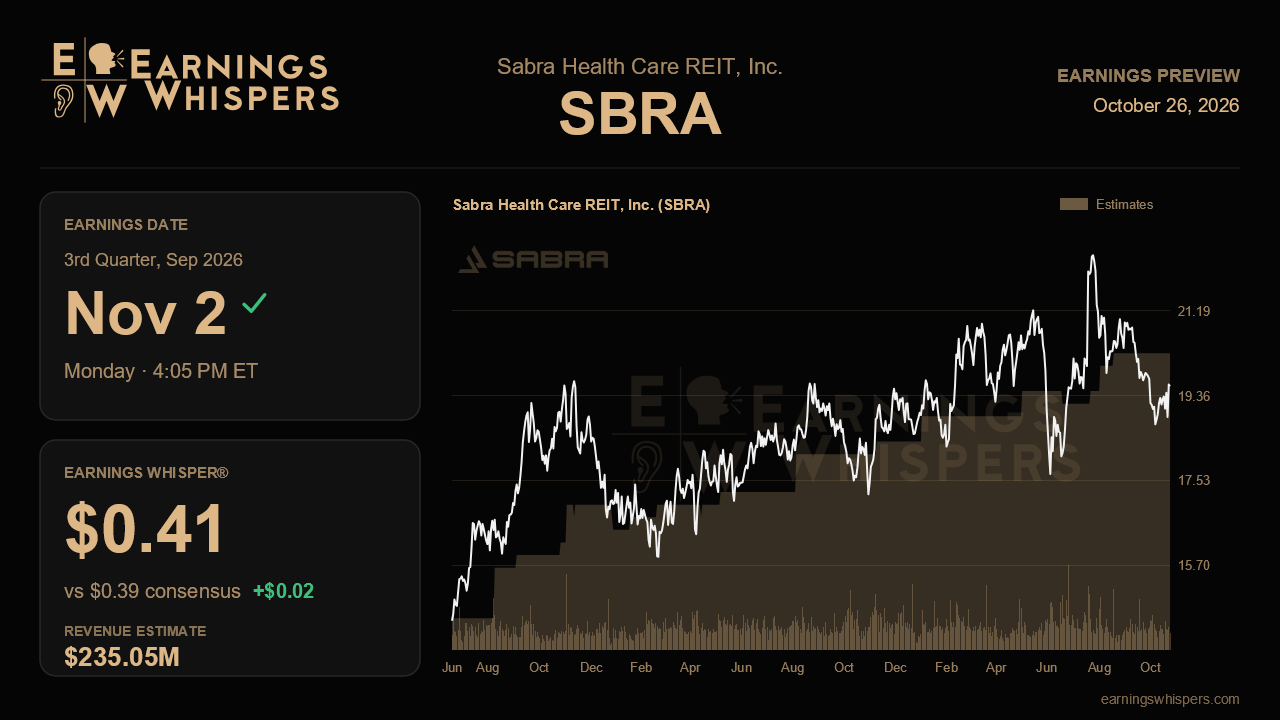
Sabra Health Care REIT heads into its third-quarter report with an odd disconnect. Management sounded more confident last quarter than it has in some time, raising its full-year growth outlook and describing a deal pipeline that has grown into the billions. Yet Wall Street's full-year estimate sits below the company's own guidance, sentiment has soured, and the shares have slipped. The report due after the close on November 2 is a test of which side is reading the business correctly.
The quarterly bar looks modest. Analysts expect funds from operations of $0.39 per share, up about 2.6% from $0.38 a year ago but a penny below the $0.40 Sabra posted last quarter. Revenue is forecast at $235.1 million, roughly flat sequentially but nearly 24% higher than a year ago, a jump that largely reflects the shift of more properties into the senior housing operating portfolio, where Sabra books facility revenue rather than just rent. The Earnings Whisper of $0.41 sits two cents above consensus, a meaningful gap for a REIT and a sign that some market participants think the sequential dip is too conservative.
That dip is not mysterious. Sabra resolved its troubled RCA mortgage through a discounted payoff that produced a $102.4 million loan-loss provision and cut interest and other income to $5.8 million from $10 million in the prior quarter. Management said the roughly 2.5 cents of dilution was already built into its outlook, which it has reaffirmed at $1.59 to $1.61 per share for 2026. The consensus figure of $1.55 is below the bottom of that range, suggesting analysts either doubt the timing of new investments or are discounting management's numbers. A quarter that tracks the guidance path would make that estimate look stale.
The operating story rests on the senior housing operating portfolio, now about 40% of NOI. Same-store cash NOI rose 13.7% last quarter as revenue per occupied room accelerated to 6.6% growth from 4.6% in the first quarter, while expense growth stayed contained near 4%, producing 130 basis points of sequential margin expansion. Year-over-year occupancy gains, however, narrowed to 170 basis points from 280 basis points as comparisons stiffened. Continued pricing strength with steady expense control would validate the margin story; a slide in rate growth or a jump in labor costs would challenge it, especially if occupancy gains keep shrinking.
Capital deployment is the second pillar. Sabra had about $599 million closed year to date and $700 million closed or awarded, with another $330 million in active pursuit and a reviewed pipeline above $1 billion, nearly all senior housing. With leverage down to 4.61 times, well under its prior 5 times target, the company has room to fund growth. The question is pricing. Management acknowledged persistent cap-rate compression and has begun buying value-add assets near 80% occupancy with roughly 6% first-year yields. Updates on whether those deals are leasing up, plus progress on the Avamir rent stepping toward $53 million and any movement on a Signature Behavioral exit, will shape the 2027 outlook.
The market has not given Sabra credit for its improving tone. The stock is down 3.7% since the last report against a roughly flat S&P 500, trades at $19.56 just below its 200-day average near $19.96, and sits closer to the bottom of its post-earnings range of $18.58 to $21.59. Sentiment has turned more bearish than it was a quarter ago. Ultimately, the report hinges on whether senior housing NOI growth and fresh acquisitions can visibly replace the income lost with the RCA loan. If they can, the case for sustained 7% to 8% growth stays intact and the Street's below-guidance estimate looks too cautious.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-19 | |
| Sep-09 | |
| Aug-14 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-23 | |
| Jul-21 | |
| Jul-20 | |
| May-28 | |
| May-01 | |
| Apr-29 | |
| Apr-29 | |
| Apr-20 |
