SITE Centers Tests A Breakout As Its Shrunken Revenue Base Faces Scrutiny
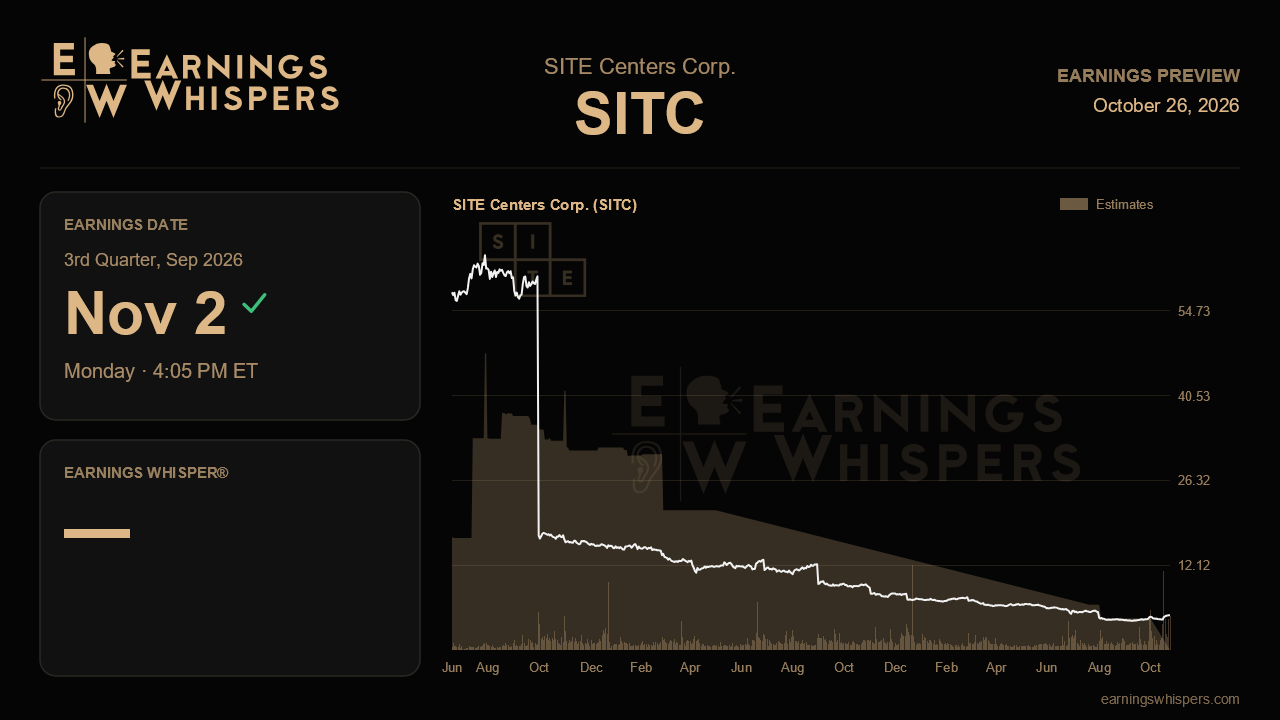
SITE Centers heads into its third-quarter report with an unusual tension. The stock has climbed roughly 23% since the company last reported, beating a flat S&P 500 by more than 23 percentage points. Meanwhile the business behind it has become far smaller. Last quarter the shopping center owner booked just $7.0 million in revenue, compared with $24.5 million in the same quarter a year earlier, and posted a loss of 9 cents a share. The rally suggests the market sees value the income statement does not yet show. The report after the close on November 2 should show whether that confidence is justified.
Wall Street has not offered a usable benchmark. There is no reliable consensus estimate for earnings or revenue, and the company has not issued updated guidance. That makes this a less conventional earnings event. With no clear bar to beat or miss, the reaction will likely depend on the quality and direction of the underlying numbers rather than a headline comparison to estimates. For a real estate investment trust whose revenue base has shrunk by more than two-thirds in a year, the key question is whether the remaining operation is stable and self-funding, not whether a quarterly figure topped a forecast.
That puts the focus on the basics of the open-air retail model. SITE Centers concentrates on suburban centers in high-income communities, where tenant demand has tended to hold up. The report would support the bull case if revenue steadies near last quarter's level instead of falling again, if per-share losses narrow from the 9 cents of the second quarter, and if leasing and occupancy data show the remaining properties are earning well. It would weaken the story if revenue keeps shrinking with no matching drop in overhead. In that case a smaller company carries the same fixed costs, and losses can widen even when the properties perform well. How quickly costs come down relative to revenue is probably the most important number in the release.
Sentiment has not kept pace with the stock. Readings were 34.6% bearish heading into this report, slightly more pessimistic than the 31.9% bearish reading before last quarter. The gap matters. A stock that rallies hard while sentiment worsens is not resting on wide enthusiasm. That cuts both ways. Doubters may be caught off guard if results are clean, but the recent gains also mean the shares have less room for disappointment than they did three months ago.
The chart adds to the tension. At $3.74, the stock sits about 3% below its post-earnings high of $3.84, close enough to call this a test of a breakout. A sharp rebound from the $2.80 low has driven the move. Even so, the shares remain well below the 200-day moving average of $4.76 and below most of last quarter's $3.30 to $5.66 range. The recovery is real but incomplete. A clean move above $3.84 after the report would point to a lasting shift in perception, while a rejection at that level would suggest the rally had already priced in the good news.
In the end, this report comes down to one question. Can a much smaller SITE Centers show a cost structure and revenue run rate that justify its rebound? Stable revenue, narrower losses and evidence that overhead is falling would support the market's recent optimism. Further revenue erosion without matching savings would suggest the rally got ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-01 | |
| Sep-16 | |
| Aug-03 | |
| Jul-27 | |
| Jul-20 | |
| Jun-30 | |
| May-07 |
