SI-BONE Heads Into Q3 With Catalysts Looming And A Stock Testing Its Highs
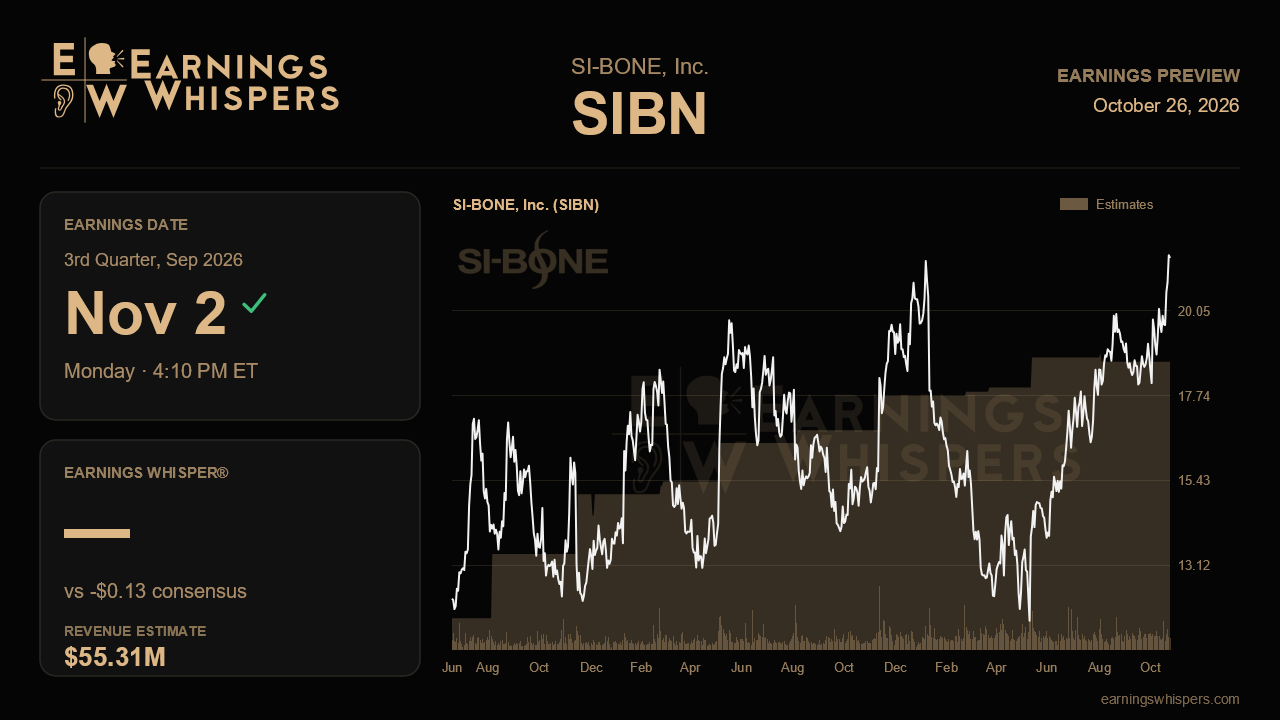
SI-BONE enters its third-quarter report in an unusual spot. The stock has climbed more than 21% since the last release while the S&P 500 went nowhere, yet sentiment toward the name has turned sharply more bearish. The reason the quarter matters is timing. The company's biggest catalysts, including finalized Granite reimbursement and the launch of its third breakthrough device, only began to arrive in October. That leaves the September quarter as a test of the core business before those catalysts can help.
The Street expects a loss of 13 cents per share on revenue of about $55.3 million. Revenue would be up 13.7% from a year ago, which is solid but continues the slowdown from the roughly 21% pace of a year earlier and the 15.2% reported last quarter. The forecast also implies a slight decline from second-quarter revenue of $56.0 million. That fits management's own assumption of a 1% to 2% seasonal sequential dip, so a modest step down should not alarm anyone on its own. The loss is expected to widen from 9 cents last quarter and 11 cents a year ago. That is consistent with management's plan to put some of its first-half profit outperformance into second-half R&D, but it puts pressure on the profitability story. For the full year, management narrowed revenue guidance to $231 million to $233 million by raising the low end. Consensus of about $231.7 million sits in the lower half of that range, so the bar for the year looks reachable rather than stretched.
The previous call was mostly about catalysts moving from possible to real. The complex-spine Granite DRGs, worth up to $50,000 more per procedure, were finalized and took effect October 1. The 510(k) for the first non-pelvic breakthrough device was filed in June, ahead of schedule, with a phased launch targeted as early as October. CMS also proposed higher outpatient and ambulatory surgery center payments for SI joint procedures, plus a new office-based lab rate above $20,000. None of these should show up much in third-quarter revenue. What investors should want is evidence that they are on track: confirmation the device launch has started, early surgeon feedback on Granite under the new DRGs, and some sign of how management is thinking about 2027 now that it has deliberately left these benefits out of its 2026 guidance.
In the reported numbers, the key signs of underlying demand are U.S. procedure volume, physician adoption and the sales build-out. Management had 93 territory managers in the second quarter and expects about 100 by year-end, and its active physician count rose 19% to 1,715. Continued growth in both would suggest the seasonal dip is just seasonal. Gross margin is the other check. Management held its full-year target at 79% while assuming low-single-digit pricing pressure from a mix shift toward interventional and trauma cases, which use fewer implants. A margin slip, or faster price erosion, would weaken the operating leverage argument that supported last quarter's 178% jump in adjusted EBITDA. Cash flow could look lumpy because most of the new headquarters build-out spending was expected in the third quarter, so a weak cash figure needs context before it is read as a warning.
The stock's setup adds to the stakes. At $21.48, shares sit about 31% above the 200-day moving average and within roughly 1% of their post-earnings high of $21.73. They are effectively testing a breakout, and the whole trading range has moved well above the prior quarter's $12 to $19 band. A rally like that suggests the market has already priced in a good part of the catalyst story, while the jump in bearish sentiment shows doubters are positioned for disappointment.
The central question is whether SI-BONE can deliver an in-line seasonal quarter, protect its 79% gross margin and keep its guidance range intact, while showing that the October catalysts have started on time. If it does, the case for faster growth in 2027 holds up. A larger-than-expected U.S. slowdown or a delayed launch would give the skeptics their opening.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-26 | |
| Oct-19 | |
| Sep-28 | |
| Aug-31 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-20 | |
| Jun-04 | |
| May-12 | |
| May-11 | |
| May-11 | |
| Apr-30 | |
| Apr-20 |
