Tactile Medical Needs Lymphedema To Carry Q3 As AfloVest Inventory Drag Lingers
Tactile Systems Technology heads into its third-quarter report with a split personality. Its core lymphedema franchise is growing at a healthy double-digit clip and margins have rarely looked better. Yet management told investors last quarter that its airway clearance business would stay stuck in an inventory hangover through this very period. The November 2 release, due after the close, is therefore less about whether Tactile can grow and more about whether one strong engine can pull the whole train while the other idles.
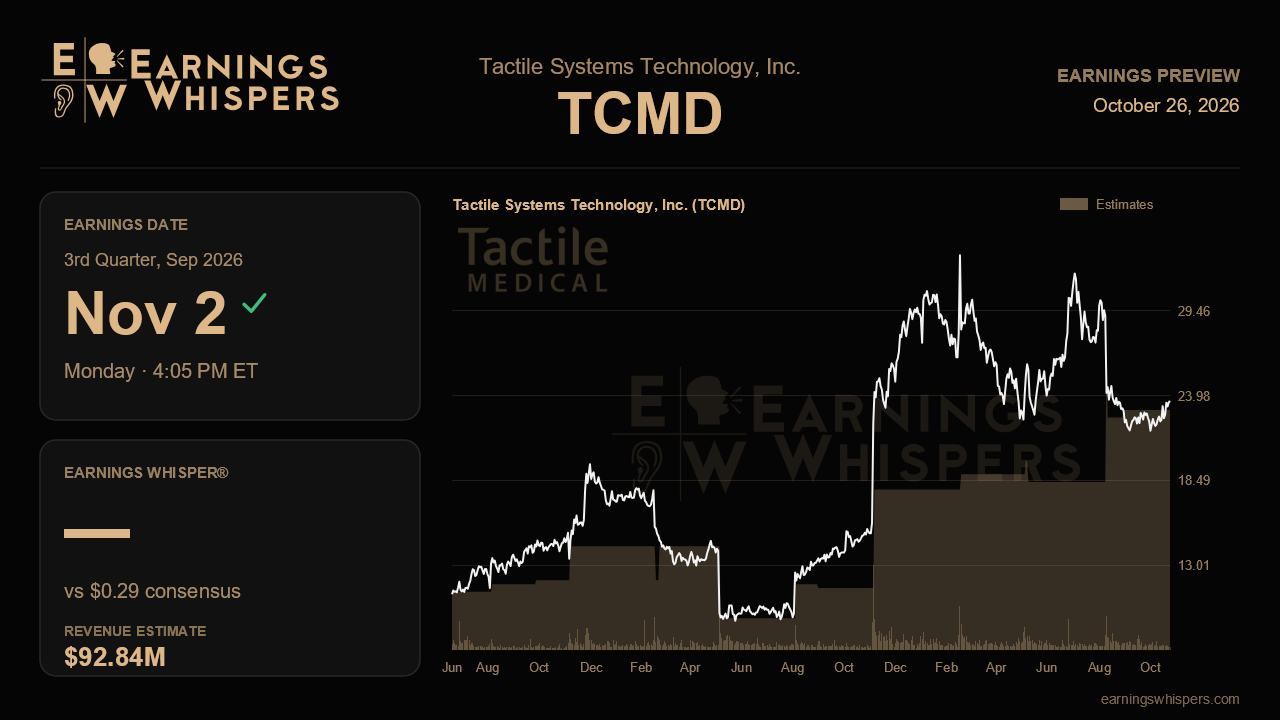
Wall Street expects revenue of about $92.8 million, up roughly 8.3% from $85.8 million a year ago and a meaningful step up from the $85.7 million reported in the second quarter. Earnings are a different story. Consensus calls for $0.29 a share, down about 19% from $0.36 last year and below the $0.34 Tactile earned last quarter. That combination of rising sales and falling profit implies analysts are bracing for heavier spending or less help below the operating line, and the company did trim its interest income outlook to roughly $2.4 million from $3.0 million as cash declined. With gross margin guidance raised to 76% to 76.5% and adjusted EBITDA guidance held at $49 million to $51 million, the profit bar looks more cautious than demanding, which leaves room for upside if margins hold near last quarter's 76.3%.
On the top line, the Street is leaning optimistic. Full-year consensus of about $364.3 million sits in the upper half of management's narrowed $360 million to $366 million range, a range whose top end was shaved by $2 million last quarter. That positioning matters because the airway clearance cut was sharp: AfloVest revenue fell 7% in the second quarter after growing 22% in the first and 66% in the quarter before that, as several large distribution partners worked down inventory around the launch of the next-generation vest. Management now sees that business roughly flat for the year. If the third quarter shows AfloVest steadying even modestly, it would support the claim that the problem is temporary channel stocking rather than softer patient demand. Another decline deeper than the second quarter's would make the promised fourth-quarter normalization harder to believe and could push the full-year outcome toward the low end.
That puts the burden squarely on lymphedema, which grew 12% to $73.6 million last quarter on broader Flexitouch adoption and a fully built sales force with improving territory productivity. Management reaffirmed low-double-digit growth for the segment, and the third quarter needs to look at least that good. The swing factor is Medicare. The April prior authorization requirement caused order volumes to moderate and Medicare revenue fell in the second quarter. Evidence that approvals are flowing more smoothly would validate management's view that the transition is on track. Investors may also look for early color on the newer catalysts, including the MyoSleeve distribution deal in the VA and Defense Department channel, which sits outside guidance, and progress using the published head and neck trial to win commercial coverage.
Sentiment has soured notably, with the bearish reading deepening to 38.7% from 18.3% ahead of the last report. Even so, the stock has edged up 1.3% since then while the S&P 500 slipped 1.9%. At $23.64, shares sit in the middle of their post-earnings range of $21.29 to $25.32 and below the 200-day moving average near $26.05, a far calmer band than the prior quarter's swing between $20.53 and $32.44. The market appears skeptical but not panicked.
Ultimately, the report hinges on whether lymphedema strength and Medicare recovery can offset a soft AfloVest quarter without forcing another cut to the revenue range. Holding guidance with an airway clearance business showing signs of bottoming would keep the transitory narrative intact. Another trim would suggest the air pocket is more than a passing inventory issue.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-19 | |
| Sep-06 | |
| Aug-10 | |
| Aug-10 | |
| Jul-21 | |
| Jul-13 | |
| Jun-02 | |
| May-20 | |
| May-04 | |
| May-04 | |
| Apr-20 | |
| Mar-09 | |
| Mar-09 | |
| Feb-26 |
