UDR Signals Top Of Its Range As Coastal Leasing Strength Meets A Skeptical Market
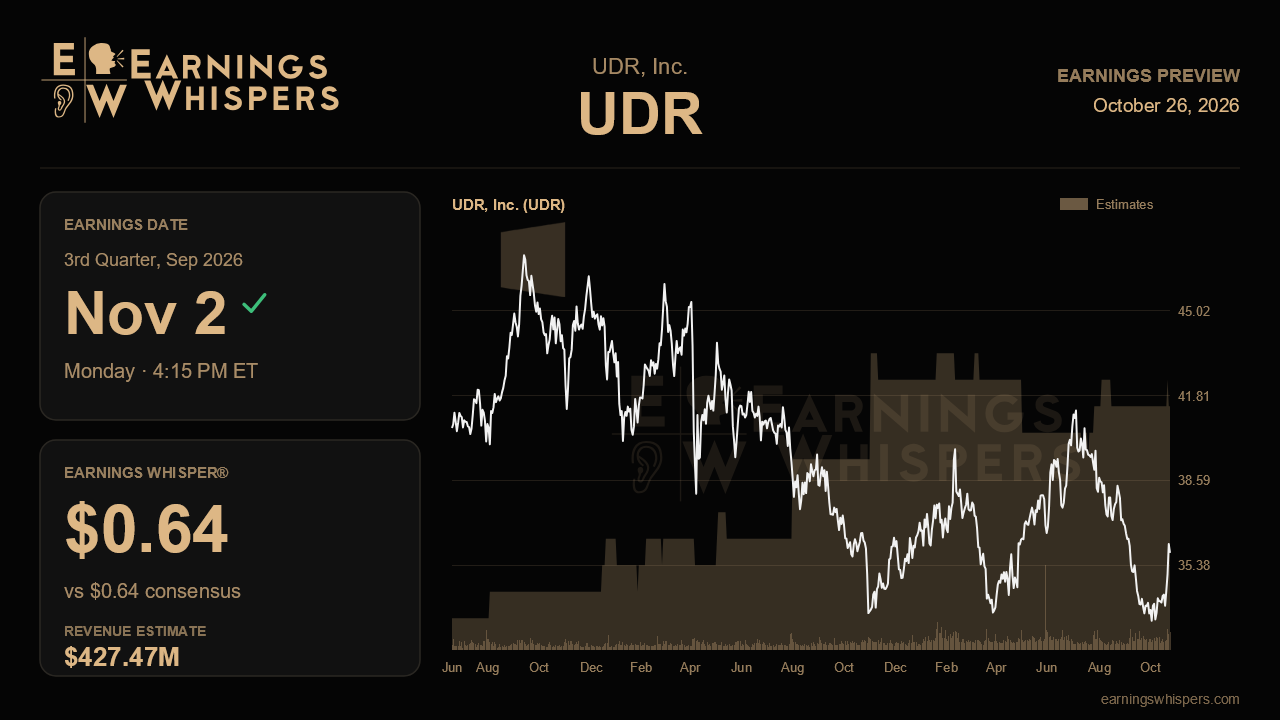
UDR heads into its third-quarter report with an unusual mismatch between what management is saying and what the market seems to believe. The apartment landlord has already told investors it expects funds from operations of about $0.65 per share, the top of its earlier $0.63 to $0.65 range. Yet the shares have fallen 6.9% since the last report while the S&P 500 gained 2.8%, and sentiment has turned noticeably more bearish. This report is a test of whether improving fundamentals can finally close that gap.
The Street is looking for $0.64 per share on revenue of $427.5 million, with the Earnings Whisper also at $0.64. That implies a slight decline from the $0.65 posted a year ago and revenue about 1% lower than last year's $431.9 million, though a modest step up from the $425.4 million reported last quarter. In other words, this is a flat quarter on paper. What stands out is that consensus sits a penny below management's own updated outlook. Unless analysts are discounting something management isn't, simply delivering on the company's stated number would count as a beat, which makes the bar look reachable rather than demanding.
The more important story is momentum. Last quarter marked a clear shift in tone after three calls spent trimming or merely holding guidance. UDR raised its full-year same-store revenue, net operating income and FFO outlooks, cut its expense growth forecast to 3.25%, and reported blended lease rate growth of 2.1%, up from 1.6% in the first quarter. Management also said new lease pricing should hold roughly flat through September, a longer leasing season than the late-summer slowdown that undercut results in prior years. That claim deserves the closest scrutiny. If third-quarter blends hold near the second-quarter pace and retention stays close to its record 60% seasonal level, the improving narrative gains real credibility. A sharp fade after Labor Day would echo last year's stumble and reopen questions about the durability of the recovery.
Geography is the other swing factor. Coastal markets produced blends near 3.8% last quarter, led by San Francisco at roughly 13%, while Sun Belt markets such as Dallas, Nashville and Florida were still negative at about minus 2%, improving to minus 1.5% in July. Continued narrowing in the Sun Belt would suggest supply pressure is genuinely abating. Washington, D.C., which generates about 16% of net operating income and saw occupancy slip after federal workforce disruptions, needs to stabilize rather than drift lower.
Capital allocation adds a layer of complexity. Management is winding down its debt and preferred equity book, from $380 million at midyear toward $250 million to $300 million by year-end, a move that costs roughly a penny of FFO for every $100 million not redeployed. Investors should look for clarity on how quickly that dilution arrives and how it shapes 2027. Buybacks partly offset the drag: UDR repurchased $300 million of stock this year at an average near $36.34 and expanded its authorization. With shares now at $35.84, below both that average and the 200-day moving average of $36.84, continued repurchases would signal management still sees deep value relative to asset value.
The stock sits in the lower half of its post-earnings range of $33.10 to $39.75, well beneath the prior quarter's $42 high, so expectations are hardly stretched. The central question is whether leasing momentum survived the seasonal slowdown. If UDR confirms its $0.65 figure, holds the fourth-quarter range of $0.63 to $0.65, and shows coastal strength persisting while the Sun Belt improves, the case that fundamentals have turned stays intact. If blends faded and the debt book runoff looms larger, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Sep-24 | |
| Sep-15 | |
| Sep-09 | |
| Aug-17 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-08 | |
| May-11 | |
| May-04 |
