Bank Of Marin Beats As Margin Expansion Lifts Returns, But Tangible Book Erosion And Souring Sentiment Complicate The Setup
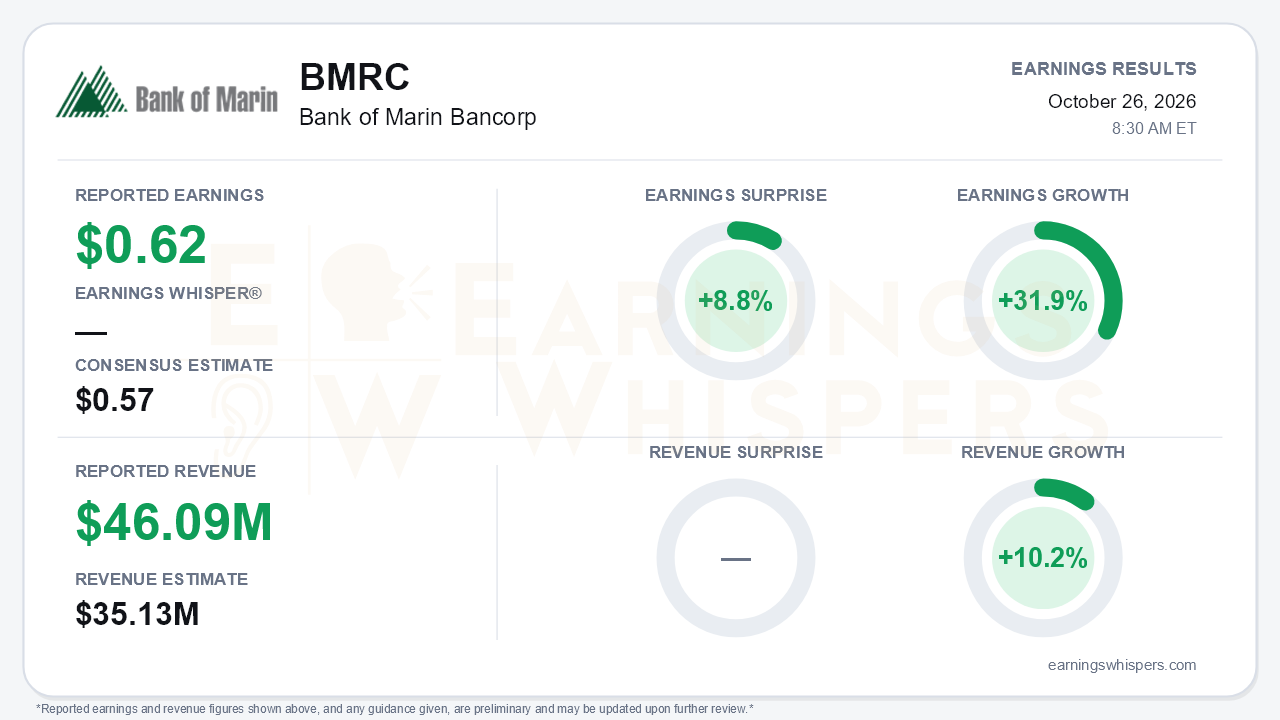
Bank of Marin Bancorp (NASDAQ: BMRC) delivered its third consecutive quarter of improving profitability. Earnings of $0.62 per share beat the $0.57 consensus by 8.8% and grew 31.9% from a year ago. Revenue of $46.09 million topped the $35.13 million consensus by 31.2% and rose 10.2% year over year. EPS has now climbed from $0.53 in the first quarter to $0.58 in the second and $0.62 in the third. Return on assets crossed 1% for the first time in this recovery, reaching 1.05%, and return on tangible common equity rose to 12.26%. The central tension is that the income statement keeps getting better while the balance sheet absorbed a rate-driven hit. Accumulated other comprehensive loss worsened by $24.8 million, pulling tangible book value per share down to $18.81 from $19.92 and the TCE ratio to 8.05% from 8.52%.
The operating engine is genuine, but parts of the beat deserve scrutiny. Net interest income rose $619 thousand sequentially to $31.4 million, and the tax-equivalent margin widened 10 basis points to 3.48%. That followed a 14-basis-point gain in the second quarter, so expansion continues but at a slightly slower pace. Average loan yields rose 11 basis points to 5.23%, and total deposit costs eased to 1.24%. Pre-tax, pre-provision income jumped 17.4% sequentially. Some of the improvement is less durable than it looks:
- A $199 thousand special FHLB dividend inflated fee income.
- Expenses fell $1.0 million partly because of an incentive-bonus accrual adjustment, which flattered the drop in the efficiency ratio to 58.65% from 63.62%.
- Margin benefited from one-way deposit sales averaging $130.6 million. Excluding those sales, the call indicated the margin would have been roughly 3.46%.
The call nonetheless preserved a credible growth story. New fundings came on at 6.65%, up from 6.53% in the second quarter and 5.91% in the first, while payoffs rolled off at 5.93%. That leaves a positive 72-basis-point spread that keeps repricing the book upward. Management raised its 12-month forward loan-yield tailwind estimate to about 25 basis points, from roughly 20 last quarter. The September margin of 3.54% reached the mid-3% target set earlier in the year. Other operating trends improved as well:
- Total commitments of $102 million rose for a third straight quarter and are up 21% year to date.
- Payoffs normalized to $31.6 million from $71.2 million.
- Noninterest-bearing deposits grew $45 million to 37.8% of total, reversing the second-quarter deposit decline.
- Business deposit repricing effective July 1 added $251 thousand in service charges, and management said more fee initiatives are coming.
Management described the fourth-quarter pipeline as similar to last year's strong fourth quarter and guided expenses roughly flat.
Bears have legitimate ammunition beyond book value. Classified loans rose $15.2 million to 1.63% of loans, driven by a $14.1 million owner-occupied commercial real estate downgrade. Management says that loan is well-collateralized, current, and carries no expected loss. Provisions resumed at $825 thousand, compared with a reversal in the second quarter, though that reflects loan and construction-commitment growth rather than deterioration. The $31.1 million residential pool purchase, at a roughly 6% expected yield, flattered loan growth. Management characterized such purchases as opportunistic rather than organic. Commercial loan pricing remains competitive, some deals slipped, and HELOC payoffs and quasi-public deposit outflows persist. Buyback discussions with regulators are 'getting closer,' but nothing was executed, and $23.9 million of authorization remains unused. On rising rates, management cited a 29% deposit beta last cycle versus 43% for peers. That argues the margin can keep expanding, but higher rates are also what is eroding tangible book.
The market setup is more complicated than the surprise implies. Investor sentiment deteriorated sharply heading into the report, sliding from roughly neutral at -0.03 to -0.40. Shares closed at $27.11 on October 23, the latest pre-report price available. That was 9.0% below the $29.80 open following the July report and 12.3% below the $30.92 52-week high set that same day. The stock bottomed at $25.45 on October 14 and entered earnings only 1.4% above its 200-day moving average of $26.74. The Earnings Whispers trend readings are mixed: momentum is positive while AVWAP remains negative. That is consistent with a stock that has bounced off its lows without recovering its post-July losses.
The bottom line is that Bank of Marin is executing its margin-recovery plan, with rising returns, disciplined costs, and a loan book repricing higher. Skeptics, however, were focused on tangible book value and credit migration, and the quarter supplied fresh evidence on both. With a modest boost from nonrecurring items, falling tangible book, and investors already leaning negative, the stock's next leg likely depends on whether margin gains keep compounding without one-way sales, whether capital rebuilds enough to unlock buybacks, and whether the downgraded loan stays an isolated case.
Read our earnings preview for Bank of Marin Bancorp: https://www.earningswhispers.com/article/BMRC/20630
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-02 | |
| Jul-27 | |
| Jul-27 | |
| Jul-27 | |
| Jul-02 | |
| Apr-28 | |
| Apr-27 | |
| Apr-27 | |
| Apr-24 | |
| Apr-02 | |
| Feb-05 | |
| Jan-27 |
