Voya Must Prove Its Promised Second-Half Rebound After An Alternatives-Battered Second Quarter
Voya Financial heads into its third-quarter report carrying a promise rather than a fresh beat. Three months ago, management asked investors to look past a $1.51 per share quarter that was dented by roughly 90 cents of alternative investment losses and severance costs. Its pitch was that the second half of 2026 would mark an earnings and cash-generation inflection. The report due after the close on November 2 is the first real test of that claim.
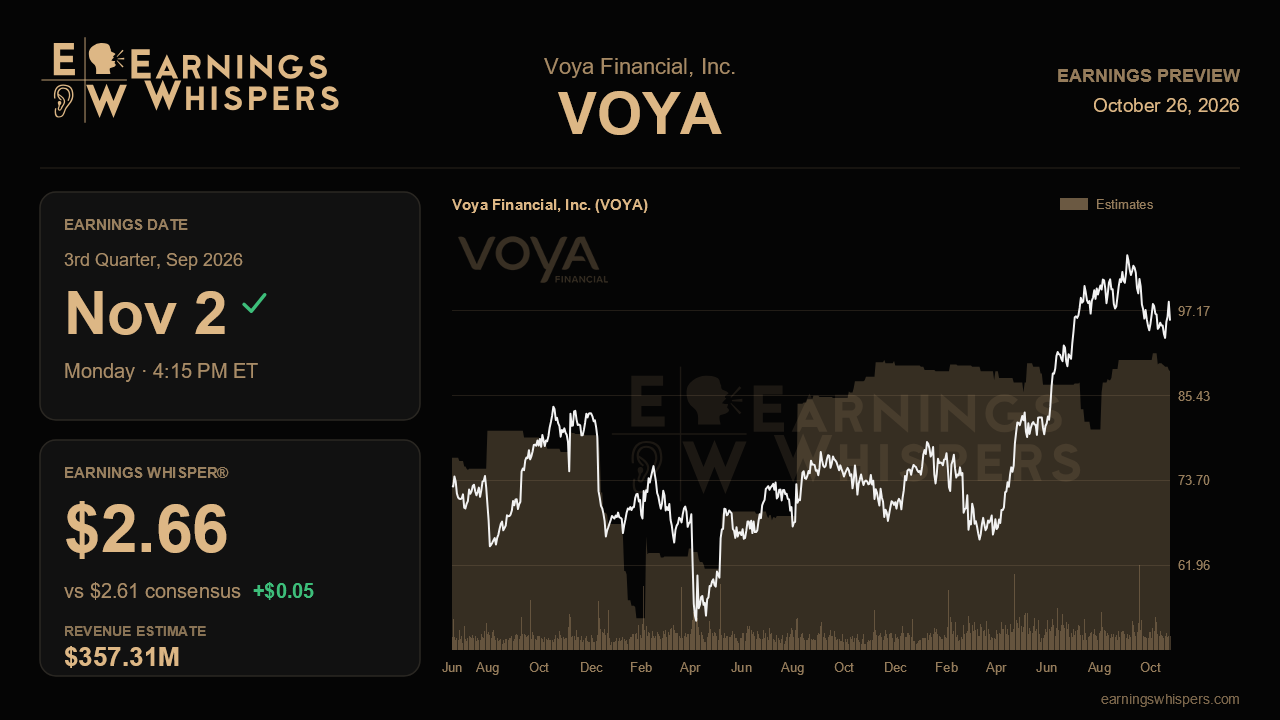
The Street is taking management at its word. Consensus calls for $2.61 per share, a steep sequential rebound from the second quarter and about 6.5% above the $2.45 earned a year ago. That is modest growth rather than a breakout. The Earnings Whisper sits a touch higher at $2.66, hinting that some investors expect a cleaner print, though the gap is too small to signal a meaningfully raised bar. The revenue consensus of $357.3 million implies an 83% drop from last year's $2.13 billion. That gap looks more like a difference in how revenue is measured than a collapse in the business, so per-share earnings and segment trends matter far more. Management reaffirmed rather than raised its outlook last quarter, and it gave no fresh numerical targets to anchor the estimate.
Getting to $2.61 depends heavily on things that went wrong in the spring reversing. Alternative investments returned a negative 2.5% annualized in the second quarter, against 8% in the first quarter and a 9% long-term expectation. Because the private equity book is reported on a one-quarter lag, a move back toward normal returns would flow directly into Retirement and the broader bottom line. Retirement earnings slid from $255 million in the fourth quarter to $190 million on softer spread income. A rebound there would confirm the weakness was mostly mark-to-market noise. Another drop would suggest spread pressure is more structural. Severance should also fade from the numbers, and management has said those actions pay for themselves by year-end, setting up operating leverage for 2027.
Employee Benefits is the swing factor on the insurance side. Stop loss has been the most encouraging story, and management's tone has grown steadily more confident. It has moved from describing a two-year repair to explicitly targeting a return to target margins in 2027, backed by a 2026 book running meaningfully better than the prior two years. Segment earnings still fell to $22 million from $63 million, as voluntary loss ratios drifted to about 54% against an earlier framing near 50%. Investors need to see those voluntary ratios settle back down, with the stop loss improvement showing up in the numbers. More reserve releases would add to the case.
Growth engines deserve a check as well. Wealth management revenue rose 12% with a fast-growing advisor force, and retirement fee revenue now exceeds 60% of the total. Investment Management, however, ran below its 2% organic growth target in the first half. A legacy sub-advised relationship winding down now adds a fresh headwind, so flows near target would ease a nagging concern.
Sentiment has cooled noticeably, swinging from mildly bullish before the last report to mildly bearish now. Yet the stock has edged up since then while the S&P 500 fell about 2%. At $95.81 it trades comfortably above its 200-day average but in the lower half of its post-earnings range, roughly 9% below the $105.64 high. Speculation about an activist push toward a stop loss sale or a sale of the company adds another layer of uncertainty. Ultimately, the quarter hinges on whether the second-quarter shortfall proves to be temporary noise. A clean rebound in Retirement and Employee Benefits earnings would validate the inflection story, while another quarter of excuses would leave it looking more like hope than plan.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-09 | |
| Oct-02 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-28 | |
| Sep-24 |
