Archrock Must Prove Its Trimmed 2026 Outlook Holds As Margins And Maintenance Work Soften
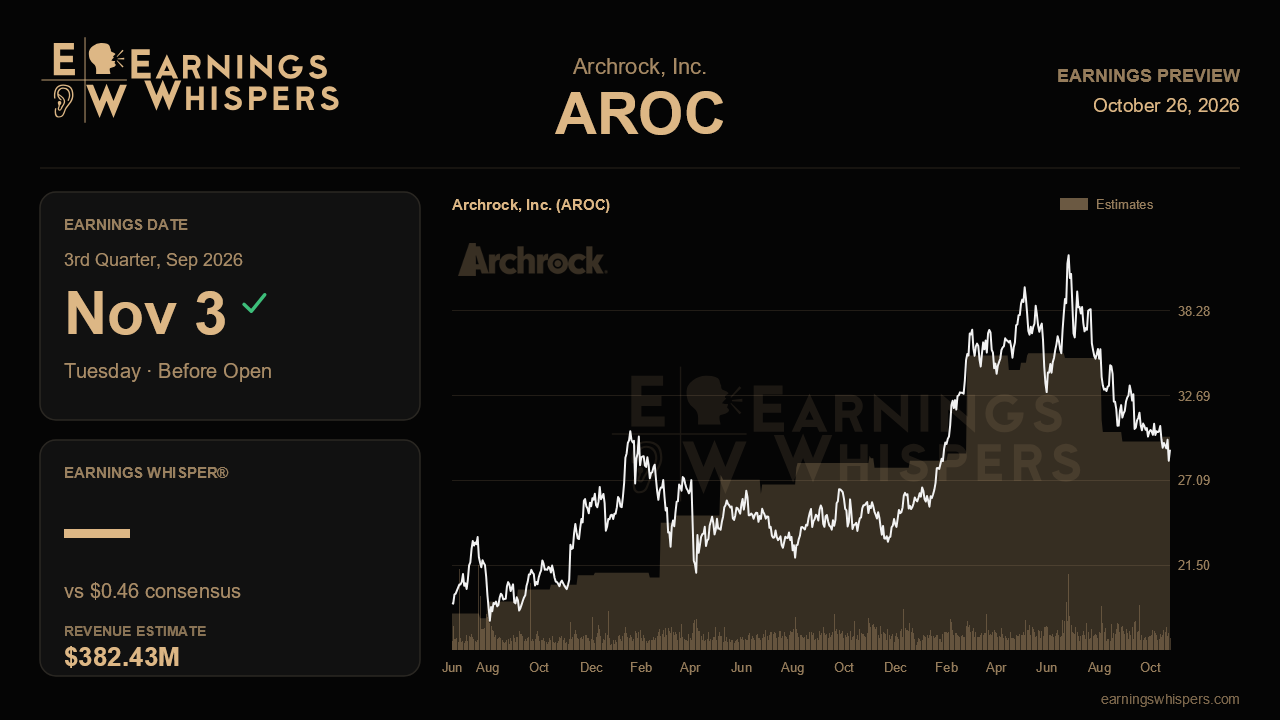
Archrock heads into its third-quarter report with an unusual split personality. Last quarter, management laid out its most ambitious growth plan yet, calling for roughly 1 million horsepower of additions and $1.4 billion to $1.6 billion of cumulative growth capital from 2027 through 2030. At the same time, it trimmed the top of its 2026 adjusted EBITDA range, lowering it to $865 million to $885 million from $865 million to $915 million. The market has taken the cut more seriously than the long-term plan. The real question for November 3 is whether the near-term softness was a temporary detour or the start of something more persistent.
Wall Street expects earnings of $0.46 per share on revenue of $382.4 million. That implies roughly 9.5% EPS growth from the $0.42 earned a year ago, on revenue that is essentially flat. In other words, the Street is betting on margin and cost discipline rather than top-line expansion. The sequential bar is more demanding than it looks. The forecast calls for a solid step up from last quarter's $0.38 on revenue only about 3% above the second quarter's $371.2 million.
The guidance math deserves attention. Adjusted EBITDA was $221 million in the first quarter and $213 million in the second, totaling about $434 million for the half. Hitting the midpoint of the revised range requires roughly $220 million per quarter in the back half. Even the low end needs about $215 million. Management has already said contract operations gross margins should drift to about 70% in the second half, from 71% last quarter, because of higher lube oil costs tied to the Iran conflict, make-ready expenses, and heavier incentive compensation. A third-quarter EBITDA print at or above second-quarter levels, despite that margin guide, would go a long way toward validating management's claim that the cut was about costs and timing rather than demand. A figure that slips below $213 million would put the low end of the range in play.
The aftermarket services segment is the other swing factor. Revenue there fell to $42 million last quarter from $50 million to $56 million in prior periods, as customers enjoying high oil prices postponed major maintenance. Deferred work does not disappear forever, so any sign of those projects returning would support the timing argument. Utilization merits equal scrutiny. It has slid from 96% to 94.4% over four reports, and another decline would be harder to blame on asset sales or one-off factors in a market where Caterpillar lead times have stretched to about 195 weeks. Investors should also look for updates on the 665,000-horsepower, eight-year midstream contract, on whether 2026 growth capex stays within $250 million to $275 million, and on how the new CFO, Mohit Singh, frames the outlook.
Sentiment has soured sharply. Bearish readings have risen to 49% from just 6.9% heading into the prior report. The stock has fallen 13.1% since the last release, trailing the S&P 500 by 11 percentage points. At $29.12, shares sit well below their 200-day moving average of $33.98 and only about 4% above the post-earnings low of $27.95. That entire trading range sits beneath the prior quarter's low of $32.60. One modest irony is that a lower share price could ease some of the incentive-compensation pressure that contributed to the guidance cut.
That gloomy positioning lowers the emotional bar, but not the arithmetic one. To keep its story intact, Archrock needs to show that EBITDA can hold near $215 million to $220 million while margins absorb cost inflation. It also needs to reaffirm the trimmed range without a second cut. If it does, the long-term growth framework regains credibility. If it cannot, investors will keep discounting 2030 ambitions until 2026 stabilizes.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-23 | |
| Oct-22 | |
| Oct-08 | |
| Sep-02 | |
| Aug-05 | |
| Aug-04 | |
| Jul-23 | |
| Jul-20 | |
| Jul-15 | |
| Jun-24 | |
| May-05 | |
| May-05 | |
| Apr-30 | |
| Apr-20 |
