AMETEK Must Turn Record Orders Into Sales As Stock Lags Its Upgraded Outlook
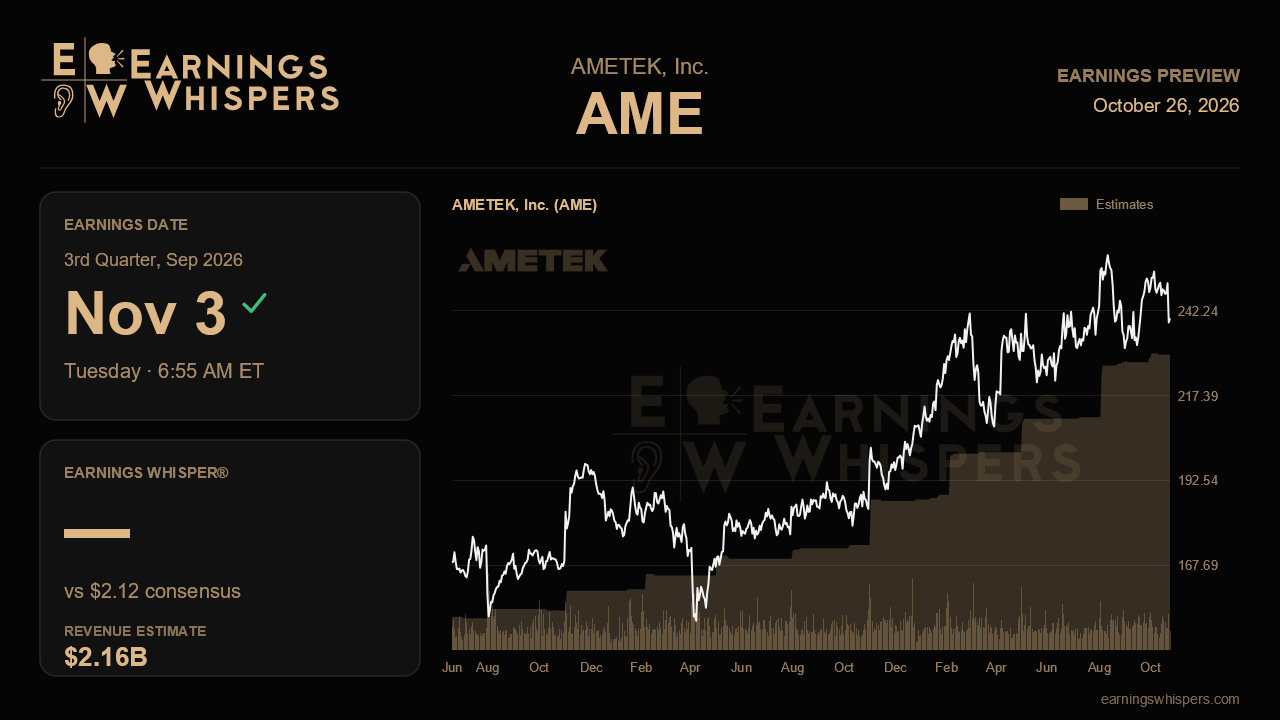
AMETEK heads into its third-quarter report with an unusual disconnect. Operationally, the company has rarely looked better: organic orders jumped a record 25% last quarter, backlog swelled to an all-time high of $4.11 billion, and management raised its full-year outlook for the second straight time. Yet the stock has slipped about 6% since that report while the S&P 500 finished essentially flat. The release before the open on November 3 is a chance to show whether the market's skepticism or management's confidence is closer to the truth.
Wall Street expects earnings of $2.12 per share on revenue of roughly $2.16 billion, which would mean growth of about 12% in profit and 14% in sales from a year ago. That is a solid step up from last quarter's $2.09 on $2.04 billion. Much of the revenue lift above the organic rate should come from acquisitions such as First Aviation, so the more telling figure will be organic growth, which management guided to high single digits after a 10% showing in the second quarter. The consensus quarterly estimate sits well above the $1.85 to $1.87 range cited in management's quarterly guidance, a gap wide enough that it more likely reflects differences in how the numbers are framed than a Street far more bullish than the company. The cleaner anchor is the full-year range of $8.20 to $8.30, raised from $7.94 to $8.14 and originally $7.87 to $8.07. That pattern of steady upgrades makes another nudge higher the implicit expectation, even if not the stated one.
The central question is conversion. Orders have accelerated for four straight quarters while organic sales only recently caught up, and a backlog that large should support shipments for several quarters. If organic growth lands at or above high single digits and backlog holds near record levels, that validates the view that the process and instrumentation recovery is durable rather than a burst of pre-ordering. A sharp drop in orders would not be alarming by itself given last quarter's extraordinary comparison, but a book-to-bill falling meaningfully below one, or a shrinking backlog, would invite questions about whether customers pulled demand forward.
Segment details matter here too. Management lifted its process outlook to mid-single digits, aerospace and defense to low double digits, and automation to high single digits. Confirmation that those ranges are holding, along with evidence that semiconductor, power grid and data center work is broadening, would support the story. The hyperscaler order for RTDS grid simulation equipment is worth tracking as an early sign of whether AI-driven power buildouts become a repeatable revenue stream. On profitability, the Electromechanical Group delivered core margin expansion of 290 basis points last quarter, down from 410 in the first quarter, helped by Paragon's medical design wins. Continued expansion, even at a more modest pace, alongside progress toward the raised $160 million productivity target, would show operating leverage is intact.
The pending Indicor acquisition, valued at about $5 billion and expected to close in the second half, adds another layer. Any update on timing, financing and the targeted 10% to 12% cost synergies will shape how investors model 2027, and could overshadow the quarter itself.
Sentiment has cooled noticeably, with bullish readings falling to 9.5% from 27.3% before the last report. The stock, at about $240, sits above its 200-day moving average but in the middle of its post-earnings range and roughly 8% below the $261 high, so it is not pressing for a breakout. That leaves room for a positive surprise. Ultimately, the report hinges on whether record orders are flowing through to sales and margins at the pace management promised. If they are, the recent selloff looks like a mispricing; if they are not, the market's caution will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-15 | |
| Aug-26 | |
| Aug-10 | |
| Aug-07 | |
| Aug-04 | |
| Aug-04 | |
| Jul-29 | |
| Jul-17 | |
| Jul-17 | |
| Jul-17 | |
| Jul-16 | |
| Jul-14 | |
| Jun-30 | |
| Jun-22 |
