Chegg's Cash Promise Faces Its First Real Test As Revenue Keeps Shrinking
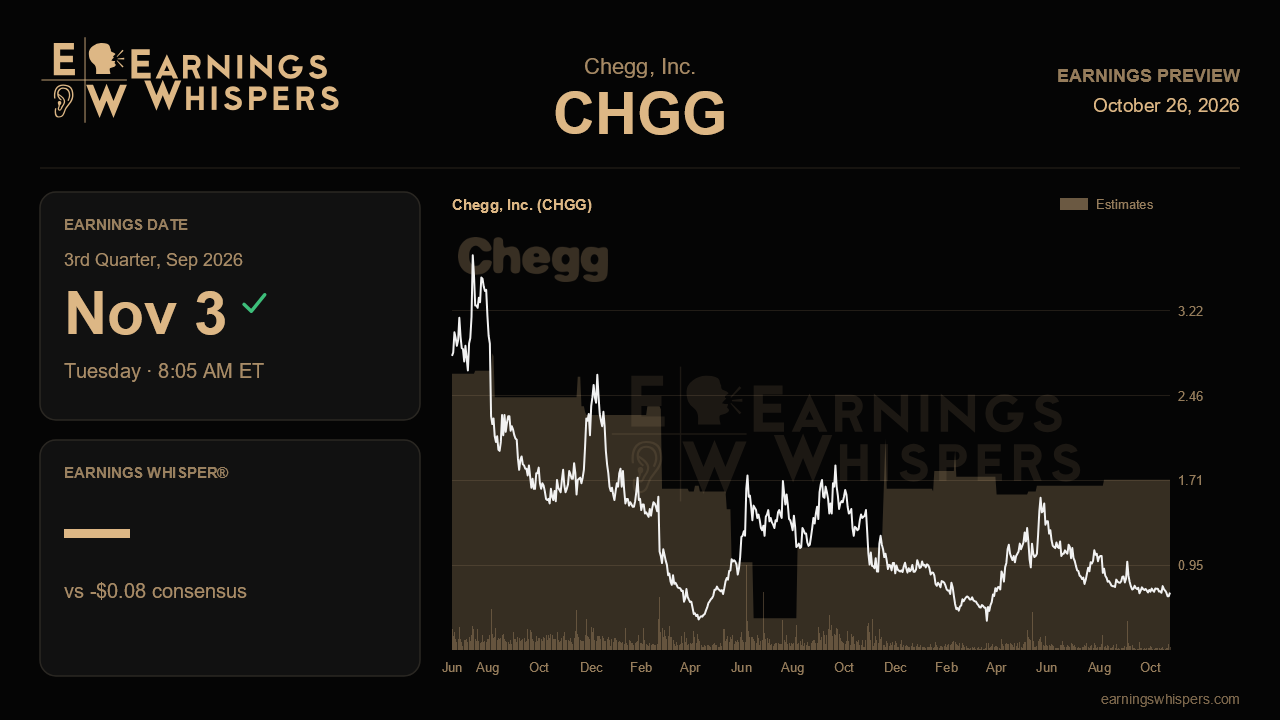
Chegg heads into its September-quarter report with a slimmer business, a stock trading well under a dollar, and less guidance than it has offered in years. Management has spent the past year arguing that deep cost cuts can turn a shrinking company into a cash-generating one. This is the first quarter of the second half of fiscal 2026, the period in which the company has repeatedly promised positive free cash flow. That makes the report less about the headline loss and more about whether the turnaround math holds once severance costs are out of the way.
The Street is looking for a loss of 8 cents a share, wider than the 4-cent loss in the prior quarter and the 5-cent loss a year ago, a 60% deterioration on a year-over-year basis. No revenue consensus is available, but the trajectory is clear enough. Sales were $51.8 million last quarter against $77.7 million in the year-ago September period, so another steep year-over-year decline looks likely. The company offered no explicit revenue, EBITDA or cash flow targets on its last call, a notable retreat from prior practice. Before that, guidance had stepped down quarter after quarter, from $70 million to $72 million for the December quarter, to $60 million to $62 million for March, to $49 million to $50 million for June. The modest beat against that last range was welcome, but the silence since then leaves investors without a yardstick.
The bull case rests on profitability. Adjusted EBITDA margin climbed from 17% to 24% over three reported quarters, non-GAAP operating expenses fell by more than half year over year, and roughly 40% of the cost base has been removed. Free cash flow turned positive at $3.1 million in the first quarter after a severance-heavy $15 million outflow. With the bulk of roughly $14 million to $15 million in severance absorbed in the first half, a genuinely positive cash quarter here would validate the claim that the leaner structure is self-funding. A wider loss paired with flat or negative cash generation would undercut it, especially since EBITDA and gross margin guidance had already been trimmed, the latter from the high 50s to the low 50s.
The growth story is shakier. Skilling, pitched as the future engine, slowed from 14% to 9% growth, short of management's double-digit ambition. The new distribution deals with Cornerstone, Wolf University's AI master's program, and the renegotiated Guild arrangement allowing multiple partners should start showing up if skilling is to reaccelerate. Academic services, still the bulk of revenue, keeps eroding under pressure from AI-driven search, though record retention offers some cushion. The relaunched internships.com employability product drew more than 10,000 beta testers, and any early adoption data would help, but management has framed it as a multi-year effort with no near-term financial contribution, so it cannot carry this quarter.
The market has delivered its verdict on the story so far. Shares have fallen 28.5% since the last report, trailing the S&P 500 by about 27 points, and at $0.70 sit below the 200-day moving average of $0.87 and closer to the post-earnings low of $0.60 than the $1.09 high. With an NYSE delisting notice outstanding and a reverse split under consideration, the sub-dollar price carries real consequences. Sentiment has cooled from faintly bullish to barely positive, suggesting few are betting on a surprise.
The central question is simple: can Chegg show positive free cash flow and stabilizing skilling growth at the same time its core revenue base continues to contract? If cash arrives as promised, the efficiency narrative survives despite the wider loss. If it does not, the absence of guidance will look less like caution and more like a warning.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-13 | |
| Oct-05 | |
| Oct-01 | |
| Sep-23 | |
| Sep-01 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-24 | |
| Jul-15 | |
| Jul-14 | |
| Jul-07 |
