Enlight's Q3 Test: Can A Planned Margin Dip Coexist With Its Raised 2026 Outlook?
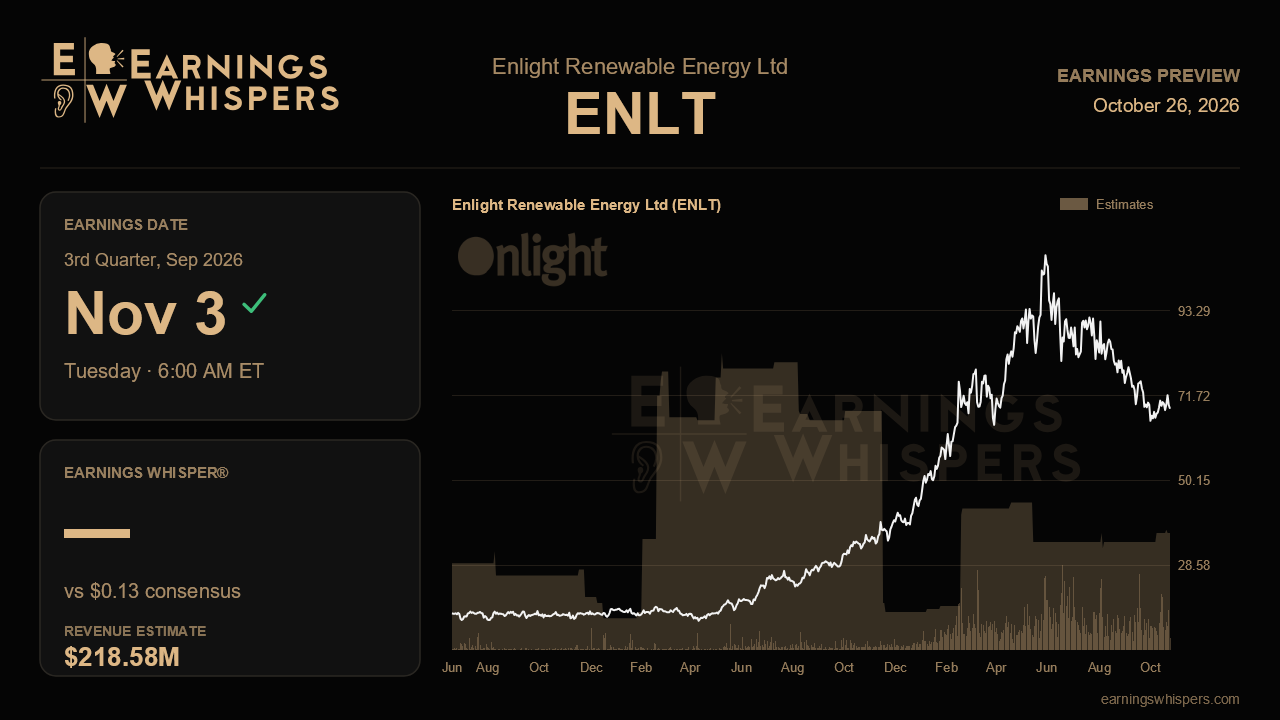
Enlight Renewable Energy heads into its third-quarter report with an unusual disconnect. Three months ago management delivered record results, raised full-year guidance for the first time this cycle and lifted its 2028 roadmap, yet the stock has since fallen about 24% while the S&P 500 went nowhere. The report on November 3 is less about whether Enlight is growing, which it clearly is, and more about whether a softer second half unfolds exactly as management telegraphed or reveals something the market fears more.
The Street expects earnings of $0.13 per share on revenue of $218.6 million. That revenue figure would be up roughly 32% from a year ago and slightly above last quarter's $209.7 million, but per-share earnings are projected to drop nearly 19% year over year and fall sharply from the $0.20 posted in the second quarter. That gap between rising sales and shrinking profit is the story in miniature. On the last call, management acknowledged that the implied second-half trajectory steps down from the first half, reflecting a growing contribution from lower-margin Israeli electricity trading and the absence of further sell-downs in the Sunlight portfolio. The second quarter alone benefited from roughly $17 million of EBITDA tied to an incremental 15% Sunlight sale, so some normalization is baked in rather than a surprise.
The guidance math gives investors a useful yardstick. Enlight now targets 2026 revenue of $790 million to $820 million and adjusted EBITDA of $565 million to $585 million, up from ranges it had merely reaffirmed in the two prior quarters. A third quarter near consensus keeps the company on a credible path toward that midpoint, but the quality of the mix matters. If revenue lands on target mainly through trading volume while adjusted EBITDA margins slip more than expected, the raise starts to look thinner. A reaffirmation of the higher ranges, or any hint of nudging toward the upper end, would validate that the step-up last quarter reflected durable operating momentum rather than one-time gains.
Beyond the income statement, the report should show whether last quarter's new catalysts are maturing. The 200 MW Google power agreement for the Solstice project in Oklahoma, the $2.6 billion COBAR financing and expansion into Finland and Romania were all framed as building blocks for a 2028 annual revenue run rate above $2.2 billion. Investors will want evidence that construction is advancing on schedule, that returns near 13% unlevered are holding and that the trimmed 2028 capacity target of about 12 factored GW does not slip further. Any update on the newly unveiled data-center pipeline of roughly 2 GW, with spending slated to begin in 2027, would add color to an option the market has not yet priced. Tariff exposure under Section 232 and the proposed inverter import ban is the main external swing factor; management downplayed near-term impact given modules already on U.S. soil and cost pass-through provisions, and confirmation of that view would remove a lingering overhang.
Sentiment has warmed modestly, moving from clearly bearish before the last report to slightly bullish now, even as the share price slid. At $68.38, the stock trades well below its 200-day moving average of $77.38 and sits closer to its post-earnings low of $64.37 than its high of $91.89, an entire range that sits beneath last quarter's trough. That suggests expectations have been reset lower, which can soften the reaction to a predictable earnings dip.
The central question is whether the second-half slowdown is the controlled, mix-driven normalization management described or the start of margin erosion. If Enlight hits its numbers, holds or improves its raised 2026 outlook and shows its U.S. pipeline and financing milestones on track, the selloff will look disconnected from fundamentals. If margins compress beyond the planned trading and sell-down effects, the market's skepticism will have found its justification.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-13 | |
| Sep-18 | |
| Aug-20 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-08 | |
| Jun-26 | |
| Jun-25 | |
| May-27 | |
| May-26 | |
| May-08 | |
| May-05 |
