First Watch Faces Its Toughest Comp As Beef Costs And Investor Day Loom
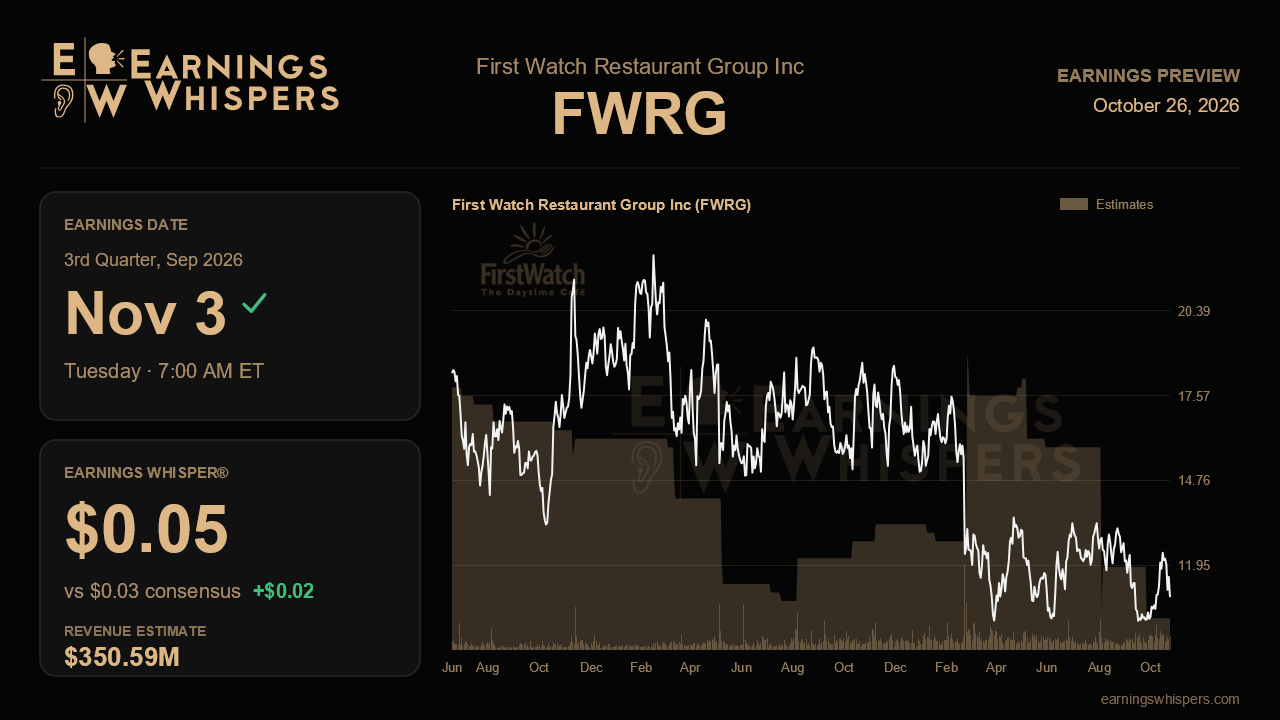
First Watch heads into its third-quarter report with an unusual problem: customers liked its premium steak specials so much that they ate into margins. Management warned last quarter that this would be the hardest comparison of the year, with same-restaurant sales likely landing at or below the low end of its full-year range. So the question is not whether the quarter looks soft on paper. It almost certainly will. The question is whether the traffic recovery that turned positive in June survived a difficult summer, and whether the beef-driven cost squeeze faded once the limited-time offer ended in mid-August.
Wall Street expects earnings of $0.03 per share, down 40% from $0.05 a year ago, on revenue of about $350.6 million, up 10.9%. That gap tells the story of this growth model. New restaurants keep lifting the top line at a double-digit clip, but profit per share is being compressed by commodity mix, the costs of opening new units and a demanding prior-year margin. Restaurant-level operating margin hit 19.7% in the year-ago quarter, the high-water mark of the recent run, so even a respectable result could look like a step back. The Earnings Whisper of $0.05 sits slightly above consensus, a hint that some investors think the beef drag eased faster than the Street assumes, though on numbers this small a couple of pennies can come from rounding as easily as from conviction.
Guidance gives useful context. Management modestly raised the low end of its 2026 revenue outlook to $1.375 billion to $1.394 billion, and the Street's $1.38 billion forecast sits in the lower half of that range. That leaves room for an upside surprise if traffic held up, but also signals that analysts are not betting on the top end. The bigger tension is adjusted EBITDA, which was trimmed to $133 million to $136 million after several quarters of margin beats. That cut was the first real crack in the profitability story. A reiterated range would suggest the beef problem was contained; another trim would raise doubts about whether menu success can be converted into earnings.
The evidence that would validate last quarter's narrative is fairly specific. Same-restaurant traffic needs to stay near flat or positive despite the tough comparison, showing that the marketing push, which lifted unaided brand awareness by more than half since early 2025, is still drawing new customers back. Check growth should keep outpacing pricing, confirming that items like the Honey Butter Biscuit Bites are driving favorable mix. And cost of goods should show improvement in the late-quarter weeks after the steak promotion ended, aided by a commodity inflation outlook that was already lowered to flat to 1.5%. A challenge to the narrative would be traffic slipping back negative or margins failing to recover even with the beef offer gone.
Sentiment has warmed noticeably, with bullish readings rising to about 57% from 37% heading into the prior report. The stock has not followed. Shares have fallen 13.1% since the last report while the S&P 500 was essentially flat, and at $10.89 the stock sits below its 200-day moving average of $12.55 and closer to the bottom of its post-earnings range of $9.88 to $13.40. The market appears to have priced in the EBITDA cut and the slower long-term unit growth plan, which shifts the company toward about 50 openings a year starting in 2027 and positive free cash flow.
That pivot is why this report matters beyond its modest earnings figure. With an Investor Day set for November 12 and a new CFO now in place, First Watch needs this quarter to show that its self-funded growth story rests on durable traffic and recoverable margins. If traffic held and cost pressure eased, the setup into Investor Day improves considerably. If not, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Aug-27 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-21 | |
| Jul-01 | |
| Jun-09 | |
| Jun-09 | |
| Jun-08 | |
| May-06 | |
| May-05 | |
| May-04 |
