Fortis Capital Plan Refresh Puts Tilbury's $2 Billion Upside And Its Funding Under Scrutiny
For a utility that rarely surprises, Fortis heads into its third-quarter report with an unusually large piece of news likely to arrive alongside the numbers. Management has promised a refreshed five-year capital plan with these results. Last quarter it handed investors a strong reason to expect a bigger one: the Tilbury 1B LNG project in British Columbia received its order-in-council. That lifts the opportunity from roughly $350 million in the current plan to about $2 billion of regulated rate base. The quarterly earnings matter, but the plan is the main event.
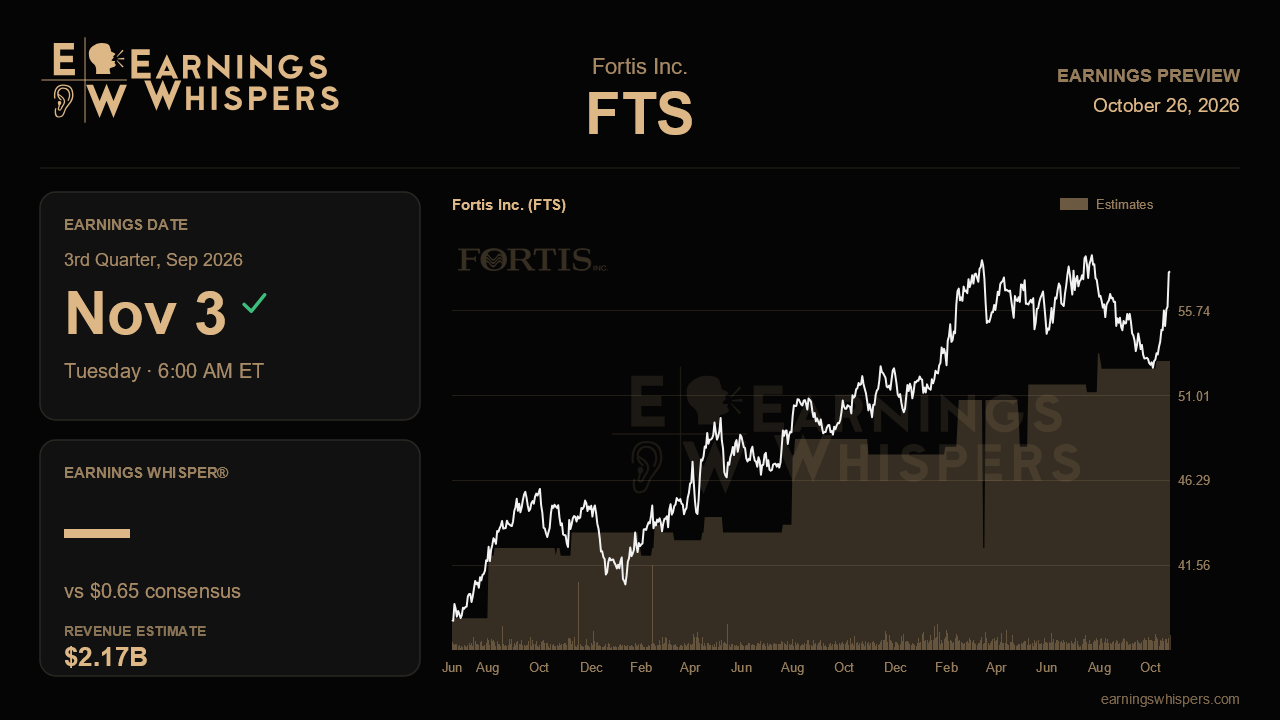
The Street expects earnings of $0.65 a share on revenue of about $2.17 billion. That would be roughly 10% earnings growth from $0.59 a year ago, on revenue up less than 2%. The gap between those two growth rates is typical of a regulated utility. The top line largely passes through fuel and commodity costs, while earnings track rate base growth and allowed returns. Double-digit growth would be a healthy result for a company that has reaffirmed 7% annual rate base growth through 2030 on every recent call. It would also help counter the impression left last quarter, when year-over-year progress looked modest.
That soft spot came largely from Arizona. Earnings at UNS were down three cents year to date because of regulatory lag on more than $700 million of rate base not yet reflected in customer rates, along with thinner wholesale margins. The Tucson Electric Power rate case was originally expected to be decided in the fall. The decision has slipped to November 17, two weeks after this report and after the state election, with TEP trimming its requested return on equity to 9.75%. Relief therefore will not show up in these numbers. Management's commentary on the case, and on possible turnover among Arizona commissioners, will shape how much of that lag investors expect to unwind in 2027.
The new capital plan will be judged on what it includes and how it is paid for. A plan that brings in the full Tilbury 1B opportunity would confirm the more confident tone on BC LNG that has built over the past several calls. So would clear progress on Tilbury 2, whose environmental assessment decision was expected this fall. Investors will also look for whether data center demand shows up as committed spending rather than optionality. That includes TEP's pursuit of an additional 300 megawatts at its first site and 500 to 700 megawatts at a second, which together imply $1.5 billion to $2 billion of new generation, and ITC's queue of roughly 8 gigawatts. ITC's bids on two MISO competitive transmission projects, with awards expected in the fourth quarter, are a further swing item. The challenge is financing. Management flagged balance sheet pressure from Tilbury and said at-the-market equity and hybrid securities are under review. A bigger plan funded by heavier dilution would be a less attractive version of the same growth story. The plan's financing details will also show how comfortable management is with its 4% to 6% dividend growth target, which underpins a 52-year streak of increases.
The market has taken a wait-and-see approach. The shares are up about 1.5% since the last report, trailing the S&P 500 slightly. Sentiment has edged up only modestly from the prior quarter. The stock does sit near a technical inflection point. At $57.95 it is pressing against its post-earnings high of $58.06 and comfortably above its 200-day moving average near $55.73. It remains below the $59.40 peak reached the previous quarter, so a convincing plan could trigger a breakout attempt.
The question for this report is whether Fortis can turn its above-plan upside into a larger capital program without straining the balance sheet. A clean quarter near consensus, a plan that captures Tilbury and large-load growth, and a funding mix that limits dilution would keep the improving narrative intact. A plan that defers that upside, or one that leans heavily on new equity, would weaken it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 3 hours | |
| Oct-05 | |
| Sep-09 | |
| Jul-31 | |
| Jul-31 | |
| Jul-31 | |
| Jul-29 | |
| Jul-23 | |
| Jul-02 | |
| May-07 | |
| May-06 | |
| May-06 | |
| May-06 | |
| Apr-29 |
