Energy Transfer's Hugh Brinson Ramp Faces Test As Street Braces For Sequential Earnings Dip
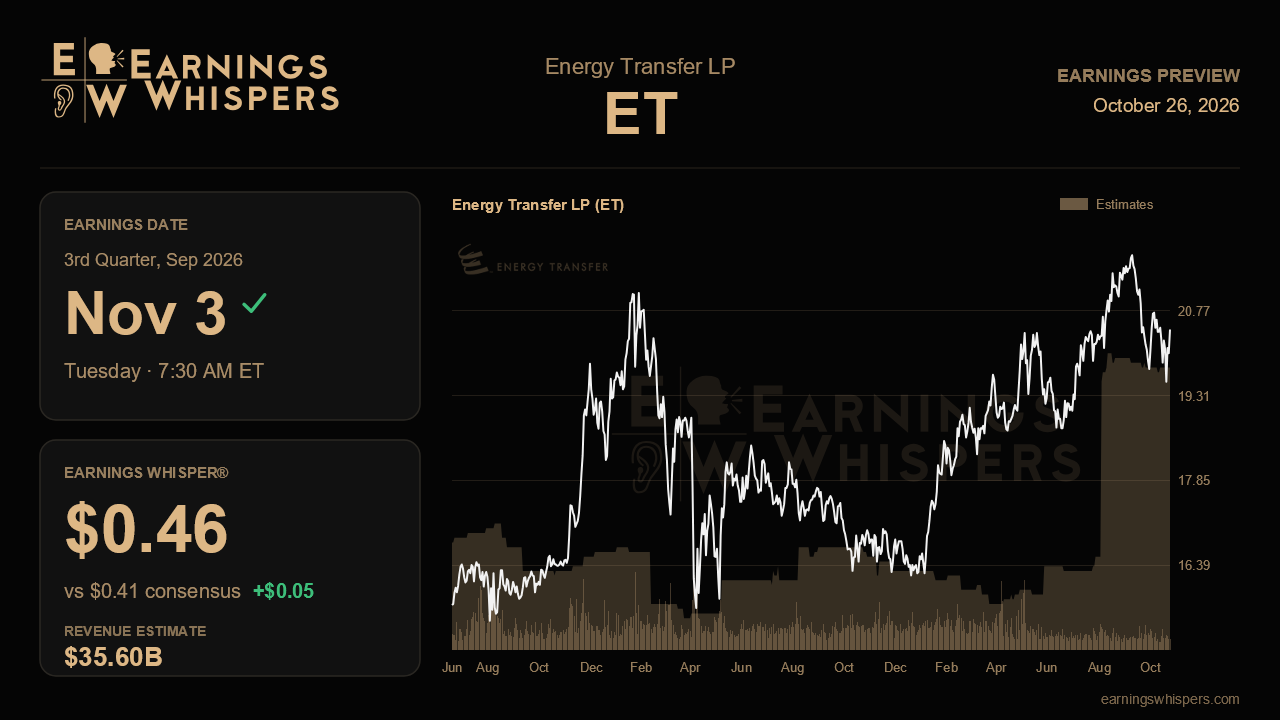
Energy Transfer heads into its third-quarter report having raised its full-year outlook twice in a row, yet the consensus forecast quietly assumes earnings will fall well short of last quarter's pace. That gap is the most interesting thing about this setup. Either the Street is sensibly baking in the fading commodity tailwinds management warned about, or it is underestimating what an early, under-budget Hugh Brinson pipeline and a busy NGL franchise can deliver.
Analysts expect earnings of $0.41 per unit on revenue of roughly $35.6 billion when the partnership reports before the open on November 3. That would represent growth of about 46% in earnings and 78% in revenue from a year ago, a strong comparison by any midstream standard. Sequentially, though, it is a step down from the $0.59 posted last quarter. The Earnings Whisper number sits at $0.46, meaningfully above consensus, which suggests the informal bar is higher than the published one and that a modest beat may already be expected.
Management's guidance frames the debate. Full-year adjusted EBITDA is now projected at $18.8 billion to $19.1 billion, up from $18.2 billion to $18.6 billion last quarter and from $17.45 billion to $17.85 billion at the start of the year. Second-quarter EBITDA of $5.1 billion was driven by beats across midstream, intrastate, crude and especially NGL and refined products. But executives also cautioned that the back half assumes little repeat of the market disruptions that juiced optimization income. That caveat is likely why consensus looks conservative, and it means the third quarter will reveal how much of the first-half strength was structural rather than opportunistic.
The operational scorecard is fairly clear. Hugh Brinson was expected to have full Phase 1 capacity of 1.5 Bcf per day available by September 1, so this report should show early volume and fee contribution, plus evidence it is filling as contracted. Mustang Draw 1, which entered service in June and was running near capacity, should add a full quarter of processing income, while commentary on Mustang Draw 2 and Fract 9 timing for late 2026 will matter for next year. Management also said NGL recontracting rates had bottomed and were turning higher, and that roughly 300,000 barrels per day of new Y-grade deals had been signed. Firming fees in the NGL segment would validate that claim. On the other side of the ledger, the interstate and intrastate gas segments softened last quarter, and a faster-than-expected narrowing of the Waha basis is eating into intrastate optimization. Another sequential decline there would not break the story, but it would confirm that Hugh Brinson's success carries a cost elsewhere in the system.
The calendar adds a further test. Management said it expected more large intrastate and interstate pipeline announcements by November, so this report arrives right on that deadline. Concrete projects, along with updates on the 250 MMcf per day of Oklahoma power demand in final negotiation and the rerouting of the Green Chile line serving Oracle, would support the case that the raised $5.6 billion to $5.9 billion growth capital budget is chasing real returns. Clarity on how the partnership is reimagining its DAPL crude strategy would also help.
The market has been unmoved. Units are down about 0.6% since the last report, roughly in line with a flat S&P 500, and trade at $20.45, above the 200-day moving average but mid-range, about 6% below the post-earnings high of $21.84. Bullish sentiment has cooled to 22.8% from 31.3% a quarter ago. Ultimately, the question is whether fee-based growth from new assets can offset the fading volatility windfall. If it can, a third guidance raise becomes plausible; if not, the Street's sequential dip may prove accurate.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-01 | |
| Oct-01 | |
| Sep-17 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 |
Texas Stock Exchange Is Close to Winning Its First Major Listing From New York
ET
The Wall Street Journal
|
| Aug-14 | |
| Aug-10 |
