Gartner's 46% Rally Puts A Third Straight Quarter Of CV Acceleration On Trial
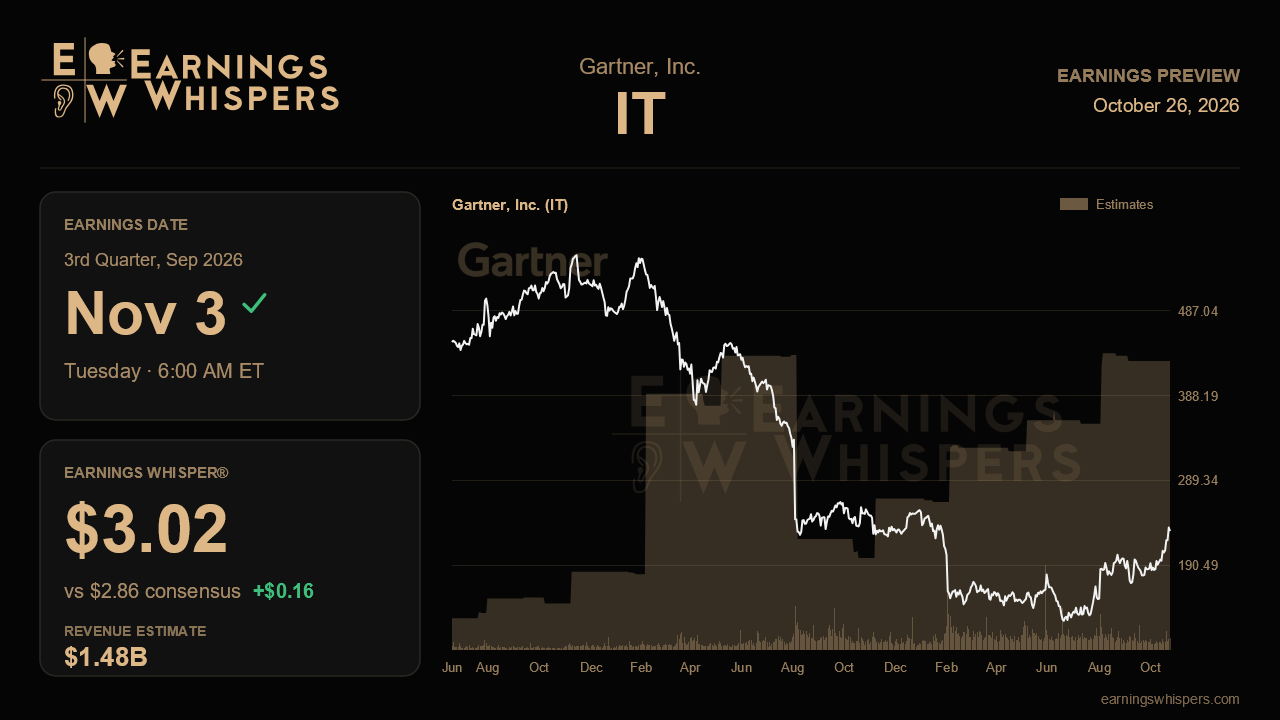
Gartner heads into its third-quarter report with a very different reputation than it had three months ago. Back then, the research firm was a show-me story still digging out from a federal spending headwind. Since then, management has delivered a second consecutive quarter of contract value acceleration, raised its full-year profit targets, and watched its shares jump about 46% while the S&P 500 went nowhere. The question for the November 3 release, due before the opening bell, is whether the operating evidence can keep pace with a stock that has already priced in a good deal of the recovery.
The headline numbers look modest on their own. Wall Street expects earnings of $2.86 a share, up roughly 3.6% from $2.76 a year ago, on revenue of about $1.48 billion, a decline of nearly 3%. The third quarter is seasonally lighter than the second, when Gartner earned $4.37 on $1.68 billion, so the sequential drop is not alarming in itself. More telling is that the earnings whisper sits at $3.02, well above consensus. That gap suggests the informal bar is closer to a clear beat than a simple match, which fits a company that has been raising expectations rather than defending them. A shrinking top line paired with rising per-share profit also reflects how much the story leans on margins and buybacks: the company cut its share count by more than 5% sequentially last quarter and lifted its repurchase authorization to roughly $1.2 billion.
The full-year framework matters here. Management raised its adjusted EPS outlook to at least $14 from at least $13.25, lifted its EBITDA target to at least $1.57 billion, and nudged its margin goal up to at least 24.6%. Revenue guidance moved the other way, trimmed to at least $6.375 billion, but management attributed that almost entirely to a stronger dollar and said insights revenue was unchanged operationally. A third-quarter revenue miss blamed on currency would be tolerable; one that hints at underlying insights softness would undercut the claim that the cut was purely optical.
The real test lies in contract value, the forward-looking measure of Gartner's subscription base. Total CV growth improved to 2% last quarter from 1%, with ex-federal growth at 3.3%, and the federal business swung back to positive net new contract value for the first time in several quarters. Management framed that federal turn as a leading indicator. Validation this quarter would look like a third straight step up in CV growth, federal holding in positive territory, and wallet retention continuing to firm as downsell stabilizes. A stall back toward 1% or a renewed federal drag would challenge the reacceleration narrative at precisely the moment the stock is pricing it in.
The softer spots deserve equal attention. New business in the Business Sales segment fell 5% year over year last quarter, worse than the prior quarter's 2% decline, and management for the first time cited artificial intelligence as a source of enterprise reprioritization alongside budget scrutiny and delayed approvals. Large enterprises and tariff-exposed industries remain under pressure, while mid-sized clients have been the bright spot. Any sign that AI uncertainty is spreading beyond a talking point into lost deals would be a meaningful negative. On the positive side, conferences grew 12% and consulting backlog rose 9%, its first year-over-year gain since early 2025, so continued strength there would broaden the recovery.
Sentiment has warmed, with the bearish lean easing to about 49% from nearly 67% a quarter ago, and the stock trades roughly 35% above its 200-day moving average and within about 2% of its post-earnings high of $234.74, testing a potential breakout. That positioning raises the stakes. If CV accelerates again and new business stops deteriorating, the improvement story holds. If acceleration stalls, a stock this extended may have little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 |
The AI Spending Boom Could Come At A Huge Cost With Trillions at Stake, Report Warns
IT
International Business Times
|
| Oct-16 | |
| Oct-16 |
