IPG Photonics Must Prove Its Margin Story Survives Without The Tariff Refund
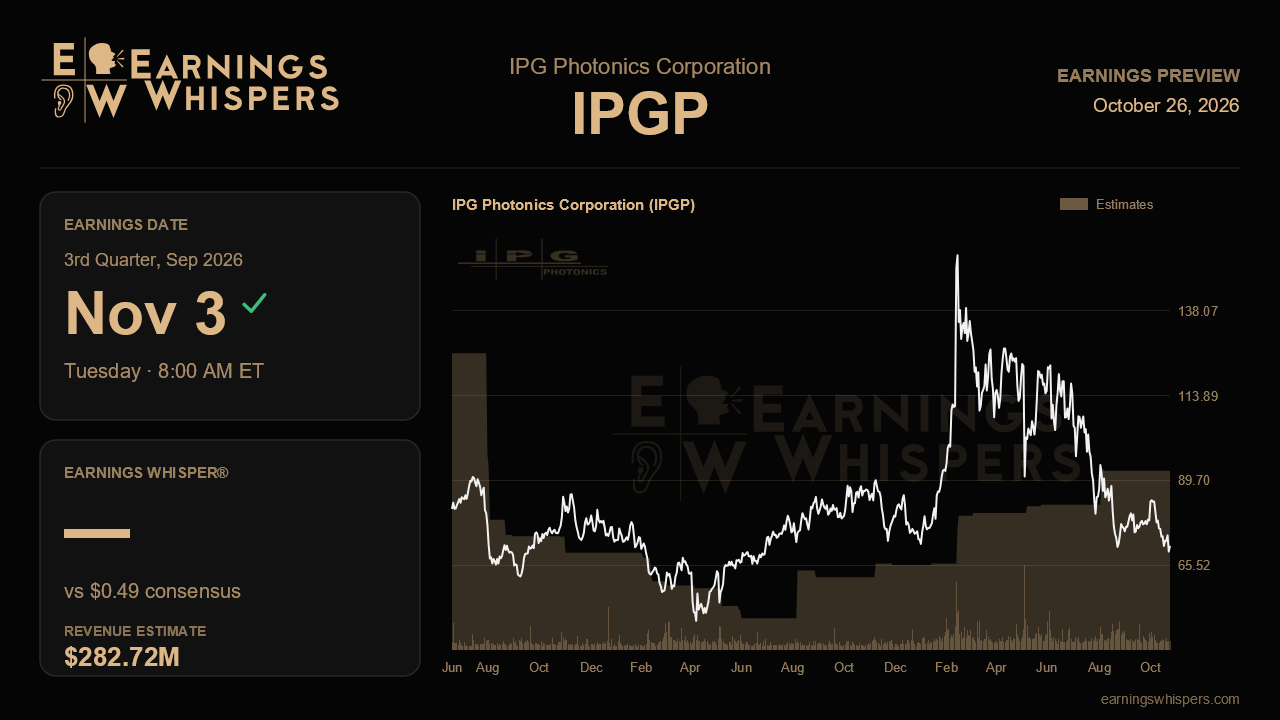
IPG Photonics heads into its third-quarter report with an awkward disconnect. The business has delivered three straight quarters of double-digit revenue growth, management raised every line of its outlook last time, and bookings keep outrunning shipments. Yet the stock has fallen about 24% since that upbeat report while the S&P 500 went essentially nowhere. The market appears to be doubting the profit side of the turnaround rather than the demand side. Monday's numbers, due before the open on November 3, are the first real test of whether that doubt is justified.
The Street is looking for adjusted earnings of $0.49 a share on revenue of $282.7 million. That would be roughly 40% earnings growth and nearly 13% revenue growth from a year ago, a healthy pace even against a softer comparison. Both figures sit in the upper half of management's guidance range of $0.30 to $0.60 and $265 million to $295 million, and consensus has drifted higher since the range was issued, when the Street was at $0.47 and about $277 million. Analysts, in other words, are not merely accepting the midpoint. They expect IPG to keep executing at or above the pace it set in the spring.
The central issue is gross margin. Second-quarter adjusted margin reached 40.7%, above the top of guidance, but about 170 basis points of that came from a one-time $4.7 million tariff refund. Strip it out and underlying margin was closer to 39%, still a real improvement over the 37.6% to 37.8% range of the prior two quarters. For the third quarter, management guided to 37.5% to 40.5% while flagging an ongoing tariff drag of roughly 150 basis points and factory absorption still short of medium-term targets. That explains why consensus earnings step down from $0.58 even as revenue edges up. A margin near or above 39% would suggest the improvement is structural, driven by mix and volume. A result near the bottom of the range would reinforce the suspicion that the spring beat was mostly accounting luck.
Mix is the lever that matters most. Emerging growth products climbed to a record 58% of revenue last quarter, and management tied that shift to battery welding for electric vehicles and data center storage, additive manufacturing, and semiconductor lithography, metrology and inspection work linked to AI chip demand. Continued gains in that share would support the margin case. The weaker pockets deserve equal scrutiny. Advanced Solutions fell 9% from a year earlier as micromachining and defense lagged semiconductors, North America slipped 2% after a 27% jump in the first quarter, and Europe remains soft on oil prices and geopolitics. Additional Crossbow shipments to Lockheed Martin, which management expected this quarter, would help steady the defense line, and any progress on the two automotive welding subsystem wins would show those awards turning into revenue.
Bookings are the other tell. A fourth consecutive book-to-bill above one would undercut the bearish view that growth is peaking. Investors will also want an update on the LumiBird Medical ophthalmology deal, which is slated to close in the fourth quarter and which management described as accretive to margins and earnings from day one.
Sentiment has soured noticeably, with bearish readings rising to about 29% from roughly 8% ahead of the last report. The stock trades near $71, around 30% below its 200-day moving average and only about 4% above its post-earnings low of $68.27, a range sitting entirely beneath the previous quarter's. That washed-out positioning lowers the bar for relief, but it also signals little patience for a margin miss. The report ultimately hinges on one question: can IPG show that its profitability gains survive without the tariff refund? If the answer is yes, the turnaround narrative remains intact despite the stock's slide.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-20 | |
| Oct-13 | |
| Oct-05 | |
| Oct-02 | |
| Oct-02 | |
| Sep-29 | |
| Aug-13 | |
| Aug-11 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-21 | |
| Jul-18 |
