Graphic Packaging Must Show Price Hikes Can Outrun $150 Million Inflation Squeeze
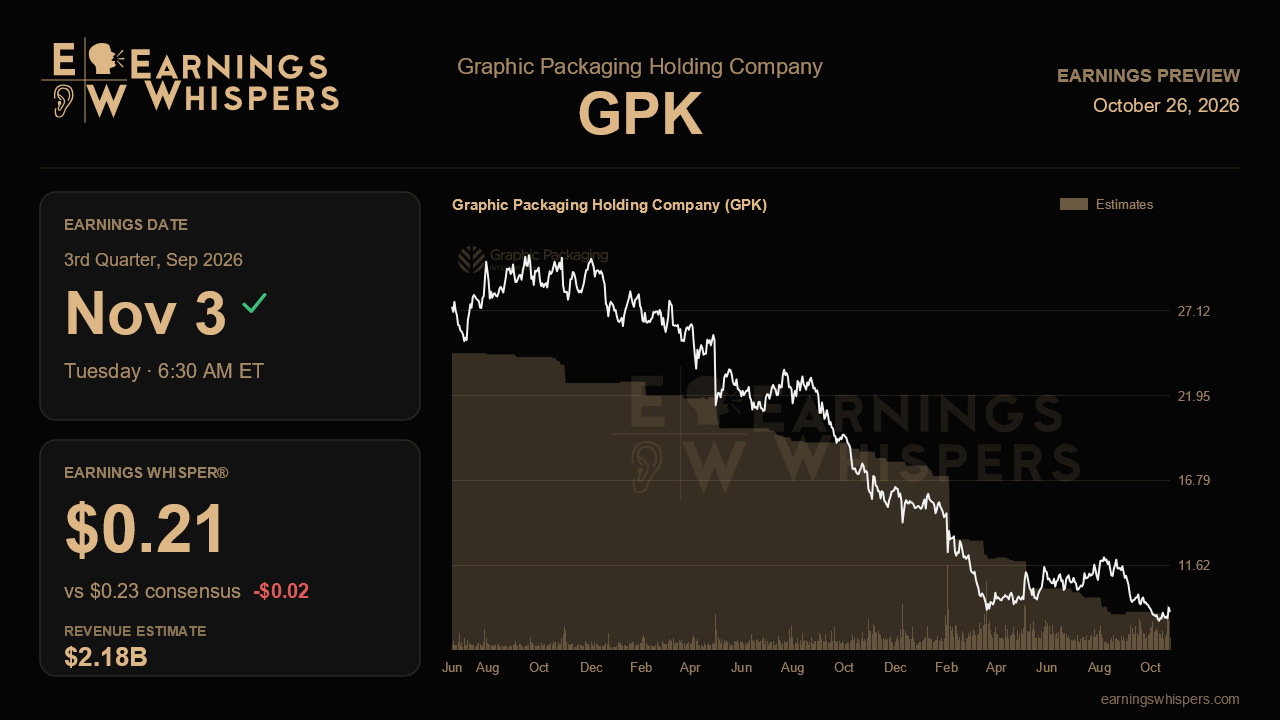
Graphic Packaging enters its third-quarter report with a straightforward question hanging over a stock that has lost nearly a quarter of its value in three months: can the paperboard price increases management pushed through over the summer start to outweigh a cost surge that more than doubled in a single quarter? Last time out, the company raised its full-year inflation estimate to roughly $150 million from $60 million to $65 million. It also cut its earnings and cash flow outlooks. The November 3 release, due before the opening bell, is the first real test of whether that reset was the bottom.
The Street is braced for a weak number. Consensus calls for earnings of $0.23 per share, down about 60% from $0.58 a year ago, on revenue of roughly $2.18 billion, essentially flat with last year. The Earnings Whisper sits a touch lower at $0.21, a small gap that suggests some traders see room for another stumble. Still, the consensus figure would be a solid step up from the second quarter's $0.14. That sequential improvement is the part of the story that has to show up. Management now guides full-year EPS to $0.65 to $0.90, down from an initial $0.75 to $1.15. The $0.75 consensus sits in the lower half of that range. It is consistent with the company's warning that adjusted EBITDA will land at the low end of its $1.05 billion to $1.25 billion target. On the top line, analysts at about $8.66 billion are slightly above the $8.40 billion to $8.60 billion range, even though management said sales are tracking to the high end. That leaves little cushion if pricing lands more slowly than hoped.
Pricing is the swing factor. Customers accepted a $60 per ton increase on cup stock and $40 per ton on folding carton in July. Management then announced a second round of roughly $120 per ton on both grades, plus $50 per ton on recycled board and another unbleached increase. The company expects about $60 million of benefit this year and a $145 million annualized run rate. Third-quarter margins should show whether those increases are sticking or being clawed back in negotiations. Second-quarter EBITDA margin improved to 11.3% from 10.8%. Another sequential gain would support management's view that 2026 is a transition year. A flat or lower margin would suggest that inflation in coatings, adhesives, resins, logistics and recycled fiber is still running ahead of price. The higher $85 million cost savings target should also start to show up in the numbers.
Cash and balance sheet discipline matter almost as much. Net leverage stood at 4.7 times, uncomfortably close to a 5.0 times covenant. The adjusted cash flow outlook was trimmed to $600 million to $700 million. Inventory reduction goals were loosened, with part of the work pushed into 2027 after production problems at unbleached mills disrupted beverage season supply. Evidence that those mills are running cleanly, that inventory is coming down, and that capital spending stays under $450 million would ease leverage worries. Any further slippage would sharpen them. Soft demand in household products and food service, which disappointed even with World Cup activity, is another place where volume could undercut pricing gains. Early traction for the new recycled board line at Waco, which has a 100,000-ton opportunity and first orders already booked, would be a welcome sign of growth.
The market has delivered its verdict on the last report. Shares fell 23.1% while the S&P 500 was flat. At $8.77, the stock sits well below its 200-day average of $10.87 and not far above its post-report low of $8.15. Sentiment remains bearish but has softened, with readings roughly half as negative as before the prior quarter. That suggests the selling may have run ahead of the fundamentals.
The narrative ultimately rests on one comparison: realized price versus inflation. If the third quarter shows margins widening and full-year guidance holding, the bear case loses momentum. Another cut, or a sign that price increases are slipping, would make the 2027 recovery story much harder to believe.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-23 | |
| Sep-17 | |
| Sep-03 | |
| Aug-27 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-29 |
