Nuveen Churchill Faces Credit Test As Shares Trade Near 61% Of Book Value
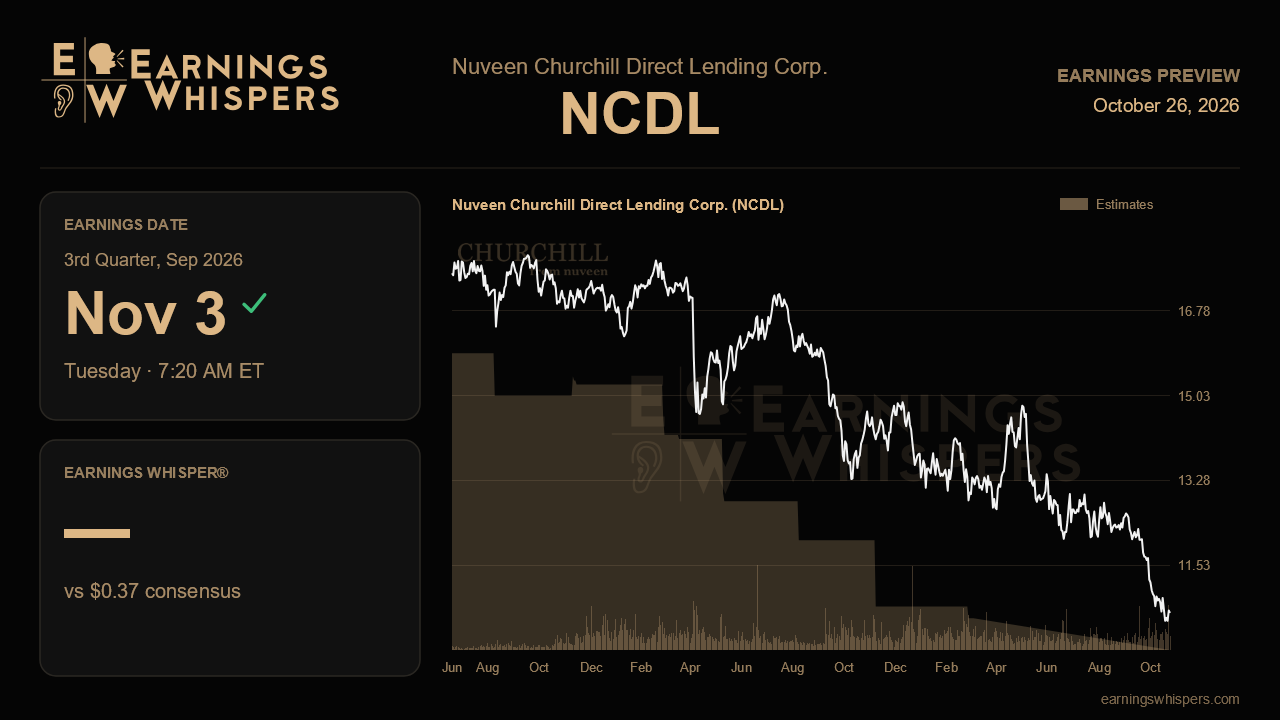
Nuveen Churchill Direct Lending heads into its third-quarter report with a stark disconnect between what its income statement says and what its stock price implies. Net investment income held steady at $0.41 a share last quarter and comfortably covered the $0.36 base distribution. Yet the shares have fallen to about $10.55, roughly 61% of the last reported net asset value of $17.19. Either the market is pricing in credit damage that has not yet surfaced, or the discount has run ahead of the fundamentals. This report should help settle which view is closer to the truth.
The Street is bracing for a softer quarter. Consensus calls for EPS of $0.37, down from $0.41 last quarter and 14% below the $0.43 earned a year ago. That estimate sits just a penny above the base dividend, which matters more than the decline itself. The company has been pairing its $0.36 base payout with a $0.02 supplemental, and a result near consensus would leave little room for extras. Management did not issue formal guidance, so the dividend math is the practical yardstick. A print at or above $0.39 would suggest earnings power is holding up better than analysts fear, while anything below $0.36 would reopen questions about a payout already reset lower from $0.45 earlier this year.
Credit is the heart of the story. Last quarter, non-accruals more than doubled to 1.5% of the portfolio at fair value and 2.7% at cost, spread across four new names in four different industries. The watch list jumped to 10.8%, its highest level in at least a year, and NAV slid for a fourth straight quarter as the company booked $0.34 a share of net losses, including realized losses on two loan amendments. Management framed the problems as idiosyncratic, with no common thread tied to software or AI disruption, and pointed to continued sponsor support. The upcoming numbers will test that framing. A stable or shrinking watch list and few new non-accruals would back the company-specific explanation. Further migration from the watch list onto non-accrual, or another meaningful NAV decline, would suggest a broader problem among more leveraged borrowers in a higher-for-longer rate environment.
On the earnings side, management laid out several offsets. The new joint venture, seeded with about $150 million of first lien loans and expected to ramp toward $300 million over roughly a year, was described as accretive, and this is the first full quarter in which it can begin contributing. The July redemption of the CLO3 facility and a $100 million add-on to the 2030 notes, fully purchased by parent TIAA, should keep funding costs near SOFR plus 188 basis points while making the balance sheet more flexible. The pressure point is portfolio size. Total investment income has fallen for several quarters, gross originations were deliberately throttled to just $12.1 million, and repayments have run well below long-term assumptions. Management said deal flow returned to normal levels in June and July, so originations rebounding meaningfully would be the clearest sign the shrinking asset base is stabilizing.
The market has been unforgiving. The stock is down 14.6% since the last report against a 1.3% slip in the S&P 500, sits well below its 200-day moving average near $12.83, and trades only about 2% above its post-earnings low of $10.31. Sentiment remains roughly 70% bearish, essentially unchanged from a quarter ago, so pessimism is entrenched rather than building.
That skepticism sets a low bar on earnings but a high bar on credit. Hitting $0.37 will matter far less than whether NAV stops falling and the watch list stops growing. If management can show the four new problem loans were isolated and the JV and refinancing are lifting income, the steep discount to book could start to look excessive. If credit slips again, the market's harsh verdict will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-15 | |
| Aug-06 | |
| Aug-06 | |
| Jul-15 | |
| Jul-10 | |
| Jul-08 | |
| May-28 | |
| May-07 | |
| Apr-15 | |
| Feb-26 | |
| Feb-26 | |
| Feb-26 | |
| Feb-24 | |
| Feb-11 |
