Lindblad's Peak Quarter Tests Whether Record Yields Can Finally Outrun Fuel Costs
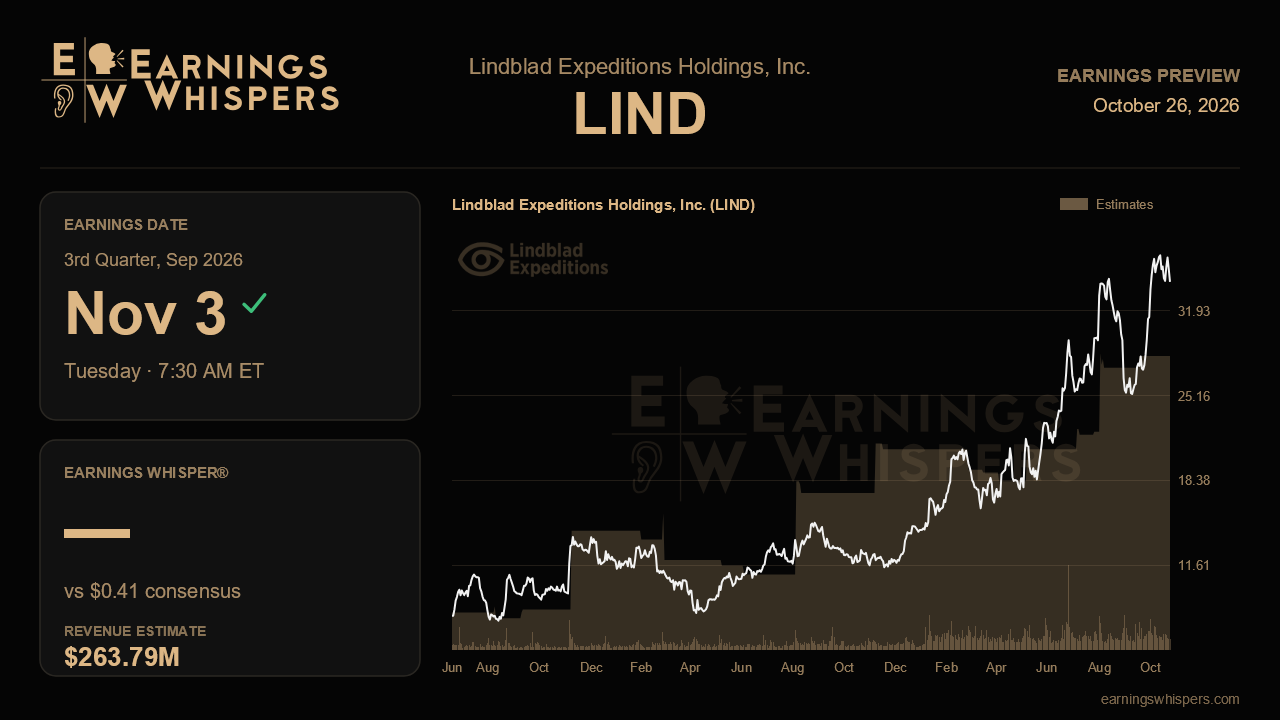
Lindblad Expeditions enters its third-quarter report with a demand story that keeps getting better and a profit outlook that has refused to budge. Management raised revenue and yield targets last quarter on record occupancy and accelerating bookings, yet left its full-year adjusted EBITDA range of $130 million to $140 million untouched for a third straight update, blaming fuel. The September quarter, the larger of the two summer-season periods judging by last year's results, is where that gap between top-line enthusiasm and bottom-line caution has to start closing.
Wall Street is looking for earnings of $0.41 a share on revenue of $263.8 million. That works out to roughly 24% earnings growth and about 10% revenue growth from the $0.33 and $240.2 million posted a year ago, a solid but not spectacular pace. The revenue math matters here. Management guided third-quarter capacity up only mid-single digits, so hitting the consensus number requires yields and occupancy to keep doing most of the lifting. A quarter that lands near the high end of the raised net yield guidance of 4.5% to 5.5%, with occupancy holding above the 90% target it has now cleared twice in a row, would confirm that the record Q2 was not merely a byproduct of the 12% capacity increase that flattered it.
The guidance picture has also shifted since the last call. With the acquisitions of White Desert and Echo Charlie, Lindblad lifted its 2026 revenue outlook to $850 million to $880 million from $830 million to $860 million. The consensus of $854.6 million sits toward the bottom of that new range, essentially where the Street was before the deal. That suggests analysts have not fully baked in the acquired businesses, which leaves room for upside if management reaffirms or nudges the range, but it also means a cautious tone on integration would land harder than usual.
The swing factor remains costs. Fuel ran up 64% year over year in the second quarter and management was modeling around $100 a barrel through year end, while the final National Geographic royalty step-up is now fully loaded into sales and marketing. Against that, Lindblad touted more than 30 cost initiatives and a 3% cut in fuel consumption despite added capacity. If those efforts show up as margin expansion in a quarter without the capacity tailwind, the case for finally raising EBITDA guidance gets much stronger. If margins stall, the Street may conclude that pricing power is simply being handed over to fuel suppliers. Fourth-quarter commentary also deserves attention, since capacity declines and accelerated depreciation tied to retiring the Seabird and Sea Lion will weigh on that period.
Forward indicators carry nearly as much weight as the quarter itself. Last call introduced Lindblad's first look at 2028, with that launch generating twice the revenue of the prior year's launch period, alongside new French Polynesia, European river and Amazon itineraries and a 44% jump in Australia and New Zealand bookings. Evidence that 2027 and 2028 booking curves are still running ahead would support the view that yield gains are durable rather than cyclical. Continued strength in the land business, which grew revenue 23% last quarter, would reinforce it.
The market has already leaned in. Shares have gained about 10.5% since the last report, outpacing the S&P 500 by roughly nine points, and at $34.24 the stock trades far above its 200-day moving average of $23.88, though still about 7% below its post-earnings high of $36.97. Sentiment remains modestly bearish but less so than heading into the prior report. The central question is straightforward: with demand evidently intact, can Lindblad show that record yields and cost discipline are strong enough to push profits higher, rather than merely absorbing fuel?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-19 | |
| Sep-15 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-20 | |
| Jul-18 | |
| May-05 | |
| Apr-29 | |
| Apr-28 | |
| Feb-26 | |
| Feb-26 | |
| Feb-26 | |
| Feb-26 |
