Knife River's Peak Season Test: Can Volume Strength Finally Reach The Bottom Line?
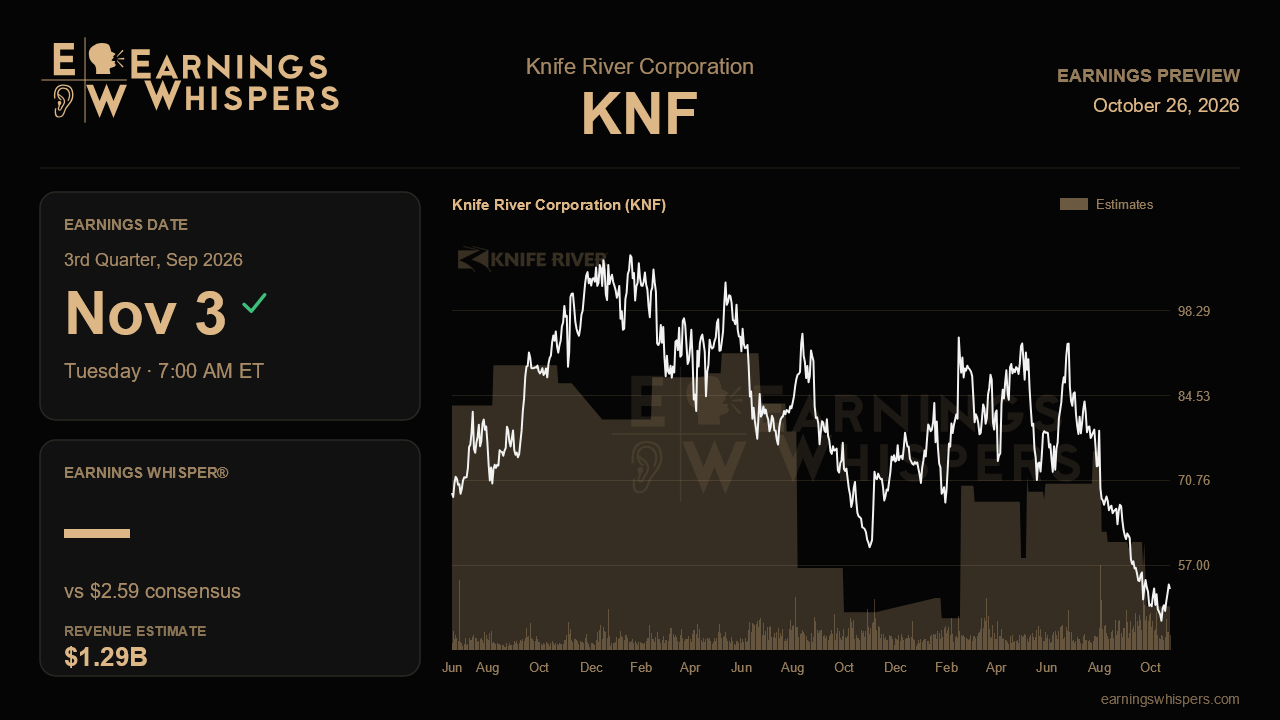
Knife River heads into its most important quarter of the year with a strange split personality. Demand looks strong: management raised its revenue outlook, lifted volume targets and pointed to record backlog conversion. Profitability has gone the other way. The company pulled back its EBITDA framing, cut its aggregates margin target in half and pushed some delayed projects into 2027. The market chose to believe the second story. Shares have fallen about 25% since the last report while the S&P 500 was essentially flat. The third-quarter release should show which narrative deserves more weight.
The Street expects earnings of $2.59 per share on revenue of about $1.29 billion. That is roughly 7% top-line growth but less than 3% earnings growth from last year's $2.52. The gap between those two numbers sums up the problem. Analysts are already assuming that more volume will not translate cleanly into profit, which fits management's warnings about diesel costs, low-margin delivery revenue and depreciation now rising at a mid-teens pace. Consensus for the full year sits near $3.39 billion, just below the low end of the raised $3.4 billion to $3.6 billion revenue range. Skeptics seem to doubt the company can convert its backlog on schedule, or they expect delays and weaker bidding in certain markets to eat into the raise. A third quarter that keeps Knife River on pace for the range would undercut that skepticism.
The bigger issue is EBITDA. Last quarter management dropped its talk of the upper half of the $520 million to $560 million range and steered toward roughly $540 million. It blamed about $24 million of headwinds: roughly $10 million of higher diesel costs, of which only $4 million was recovered; another $10 million from weather and schedule slippage in Texas, Hawaii and Alaska; and about $8 million from contracting mix and the timing of incentives. Because the third quarter is peak paving and construction season, it should show whether those were temporary bumps or the start of a pattern. Proof that fuel surcharges are catching up with costs would support the midpoint guidance. So would steady aggregates pricing near the high-single-digit gains of recent quarters and contracting margins that stop sliding. Another reset of the EBITDA target would be the clearest sign that the problem has grown.
Regional details matter too. Oregon was supposed to stabilize. Instead, weak asphalt bid lettings pushed expectations slightly lower and raised the risk of pricing competition spreading into northern California, Idaho and Montana. Low-margin legacy projects inherited in the Mountain region, particularly Utah, are also expected to drag on contracting results through the second half. On the positive side, the Strata acquisition is tracking more than 15% ahead of its original EBITDA plan. Data center work in the Central segment and a semiconductor pre-stress contract out of Spokane are newer growth stories, and updates on them would help show that demand is broadening beyond traditional public paving.
Sentiment has warmed a little, moving from slightly bearish before the last report to modestly bullish now. The stock tells a harsher story. At about $53, shares trade far below the 200-day moving average near $75 and sit in the lower part of a post-earnings range that stretches from roughly $48 to $72. That range is well beneath the prior quarter's $69 to $96 band. With that much pessimism priced in, a clean quarter could do a lot of work. A messy one, however, would confirm the market's suspicion that growth is getting more expensive to deliver.
In the end, the report has one main job: showing that Knife River's double-digit volume growth can produce earnings again. If the company holds the EBITDA midpoint, starts recovering fuel costs and tracks its aggregates margin target without new excuses, last quarter's stumble looks like timing. If not, the revenue raise will look like activity without profit.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-15 | |
| Oct-09 | |
| Sep-24 | |
| Sep-24 | |
| Sep-23 | |
| Sep-02 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-30 | |
| Jul-15 | |
| Jul-08 | |
| May-05 |
