PJT Partners Faces A Steep Bar Set Low: Can Record Mandates Offset A Forecast Revenue Slide?
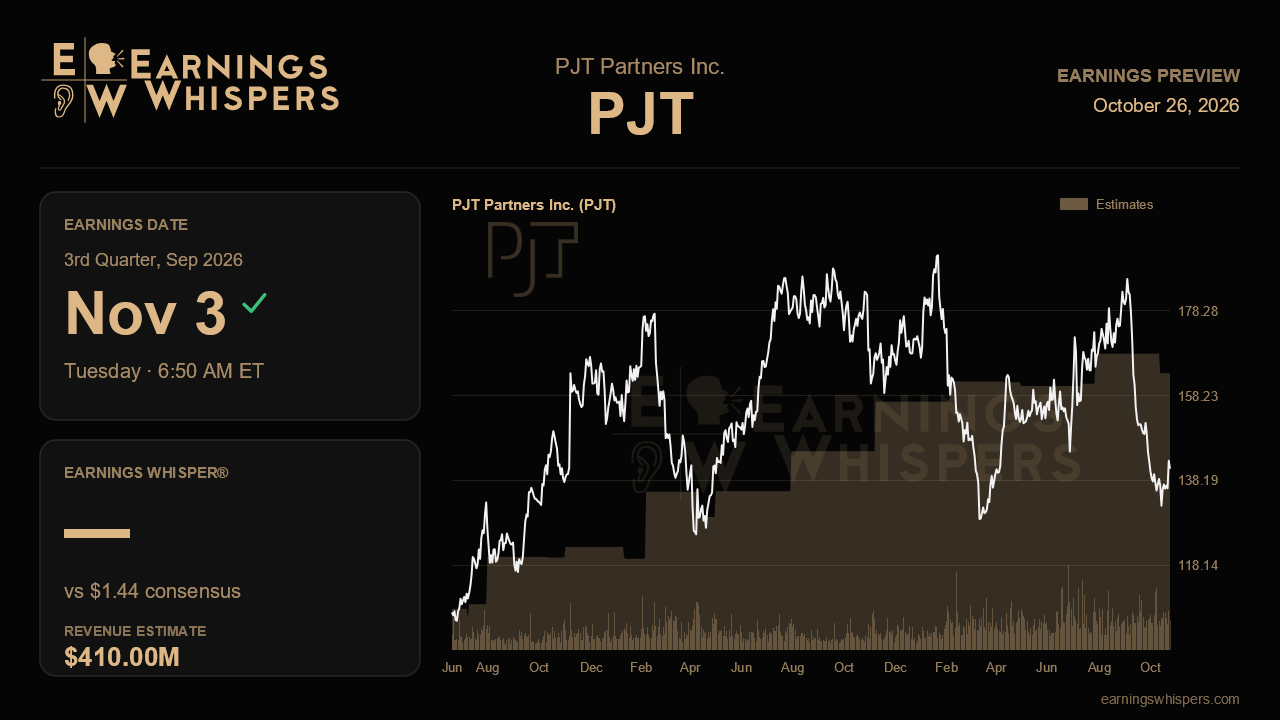
Three months ago, PJT Partners delivered the best quarter in its history and talked up a deepening M&A recovery. Since then the stock has fallen nearly 16%, trailing the S&P 500 by more than 18 percentage points, and Wall Street now expects the firm's third-quarter report to show outright contraction. That gap between management's upbeat operating narrative and the market's skepticism is what makes Tuesday's pre-market release so interesting.
Consensus calls for earnings of $1.44 a share on revenue of $410 million. That would mean a 22% drop in EPS from the $1.85 earned a year ago and an 8% decline in revenue from $447.1 million. It would also be a sharp step down from the record $486.3 million and $1.97 posted last quarter. Management did warn that full-year growth would come in below the 24% pace of the first half, so some deceleration was always coming. But a slide into negative territory is a much harsher outcome than a simple cooling off. If PJT merely slows rather than shrinks, the Street's forecast could prove conservative.
The case for caution rests largely on timing. Advisory revenue is recognized when deals close, and the announced pending-closed backlog ended the second quarter just slightly below its year-ago level. That backlog had rebuilt appreciably from the first quarter, yet it still suggests completions in the near term may struggle against a tough comparison. The more encouraging indicators sit further upstream. Strategic advisory mandates hit a record and were up more than 20% from a year earlier, accelerating from 15% growth in the prior quarter, and the pre-announced pipeline was growing even faster. The key test this quarter is whether management can report that those mandates are converting into announcements, and whether the backlog has moved back above year-ago levels. That would validate the recovery story even if reported revenue dips.
Margins are the other swing factor. Last quarter's adjusted pre-tax margin of 21.7% was two points better than a year earlier, but that came on surging revenue. The compensation accrual was held at 66.5%, and management lifted its non-compensation expense growth forecast to roughly 14% from 12%, citing travel, professional fees and AI and technology spending. Rising fixed costs against falling revenue is a recipe for deleverage, which explains why consensus EPS is falling nearly three times as fast as sales. Any sign that the comp ratio is being trimmed, or that non-comp spending is tracking below the raised guide, would help cushion the bottom line.
Restructuring and private capital solutions should provide ballast. PJT remains at the top of the restructuring league tables, and management has consistently said liability management activity should stay elevated for the foreseeable future. Secondaries strength has more than offset weak primary fundraising. Management also framed AI disruption as a net positive, pointing to take-privates, secondaries demand and data-center financings. Evidence that these themes are producing fees would broaden the bull case. This is also Arun Kalra's first report as CFO after Helen Meates stepped down on October 1, so the clarity of his commentary on costs and outlook will matter.
Sentiment has improved modestly to 17.4% bullish from 12.7% before the last report, but the stock tells a gloomier story. At $140.94, shares sit well below the 200-day moving average of $157.40 and not far above the post-earnings low of $131.37, a long way from the $187.57 high. Expectations, in other words, look subdued. The central question is whether record mandates and a rebuilding backlog still point to a durable recovery, or whether the projected revenue decline marks the start of something worse than the gentle slowdown management described.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-22 | |
| Jul-28 | |
| Jul-28 | |
| Jul-28 | |
| Jul-20 | |
| Jul-16 | |
| Jul-07 | |
| Jun-15 | |
| Jun-15 | |
| Jun-12 | |
| May-19 | |
| Apr-29 | |
| Apr-28 | |
| Apr-28 |
