Philips Needs Monitoring Orders To Return As Q4 Back-Loading Raises The Stakes
Philips heads into its third-quarter report with a story that hinges on timing. Last quarter, order intake slipped 1% for the first time in seven quarters, and management attributed the miss to large North American monitoring contracts sliding into the current period rather than to lost demand. This report is where that explanation gets tested. If those orders show up, the narrative of steady top-line acceleration holds. If they do not, the company's heavily back-loaded full-year plan starts to look considerably more fragile.
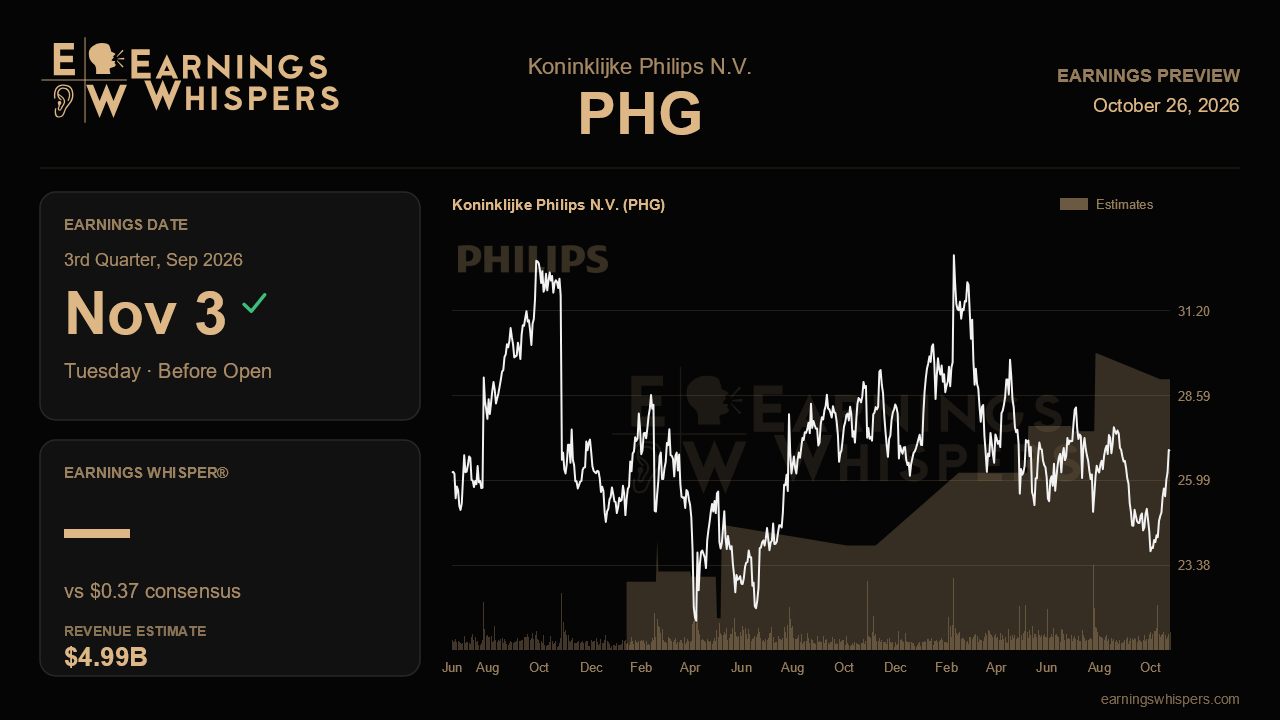
Expectations are deliberately modest. Consensus calls for earnings of $0.37 per share, unchanged from a year ago, on revenue of about $4.99 billion, down 0.8%. That is effectively a flat quarter. It also marks a sharp step down from the $0.57 posted last quarter, though that figure was flattered by a one-off US tariff refund. Management had already steered the Street lower, guiding third-quarter comparable sales to the low end of a 3% to 4.5% range and margins below the prior-year level, citing China and ultrasound headwinds. Because comparable growth strips out items that reported dollar figures include, the slightly negative consensus revenue line does not necessarily conflict with that guidance. A clean read on comparable growth near 3% would be consistent with the plan.
The more important questions sit beneath the headline numbers. Comparable sales growth has climbed from 1% a year ago to 3% and then 4.1% last quarter, with Personal Health leading on new Sonicare ranges and broader retail distribution, and Image-Guided Therapy extending a long growth streak. Investors should want evidence that this breadth survives a softer guided quarter. Margins are the sharper concern. Stripping out the tariff refund, Diagnosis & Treatment margin fell to 9.3% last quarter, down 460 basis points from a year earlier, squeezed by cost inflation, tariffs, currency and an unfavorable China mix. Management also flagged that inflation would weigh more heavily in the second half as higher-cost inventory flows through. Any sign that D&T margin is stabilizing would ease worries; another deterioration would raise doubts about the underlying 12.5% to 13% full-year margin target.
China remains a drag rather than a recovery story. Management softened its outlook to broadly stable as centralized procurement expands nationwide, lengthening conversion times and pressuring pricing on less differentiated products. Enterprise Informatics is another watch item, since its shift to cloud subscriptions is temporarily depressing recognized revenue. Europe offers the counterweight, having delivered double-digit order growth last quarter on wins such as a 200-hospital program in Poland and a region-wide hospital-at-home deal in Stockholm. Continued European order strength alongside a monitoring rebound would go a long way toward restoring confidence in the order book.
The market has already leaned toward the optimistic reading. Shares have gained 12.3% since the last report, outpacing the S&P 500 by roughly 9.5 percentage points and climbing from a post-earnings low of $23.62 toward the upper end of their range. Yet the stock, at $26.89, still sits just below its 200-day moving average and short of the $27.77 post-earnings high, and sentiment has cooled to modestly bullish from a somewhat warmer reading a quarter ago. That combination suggests investors have bought the recovery thesis but are not yet fully committed to it.
Ultimately, this quarter matters less for what it earns than for what it implies about the fourth. Management needs the final quarter to deliver upper-mid-teens margins and roughly 40% of full-year adjusted EBITDA. A rebound in orders, stabilizing D&T profitability and a reaffirmed underlying outlook would make that hurdle look reachable. Without them, the back-end loading becomes the story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 17 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-20 | |
| Oct-15 | |
| Oct-11 | |
| Oct-10 | |
| Oct-05 | |
| Sep-16 | |
| Sep-10 | |
| Sep-08 | |
| Sep-03 | |
| Aug-28 | |
| Aug-27 | |
| Aug-27 |
