Sequans Faces A Margin Test As Revenue Guidance Steps Up And Licensing Timing Looms
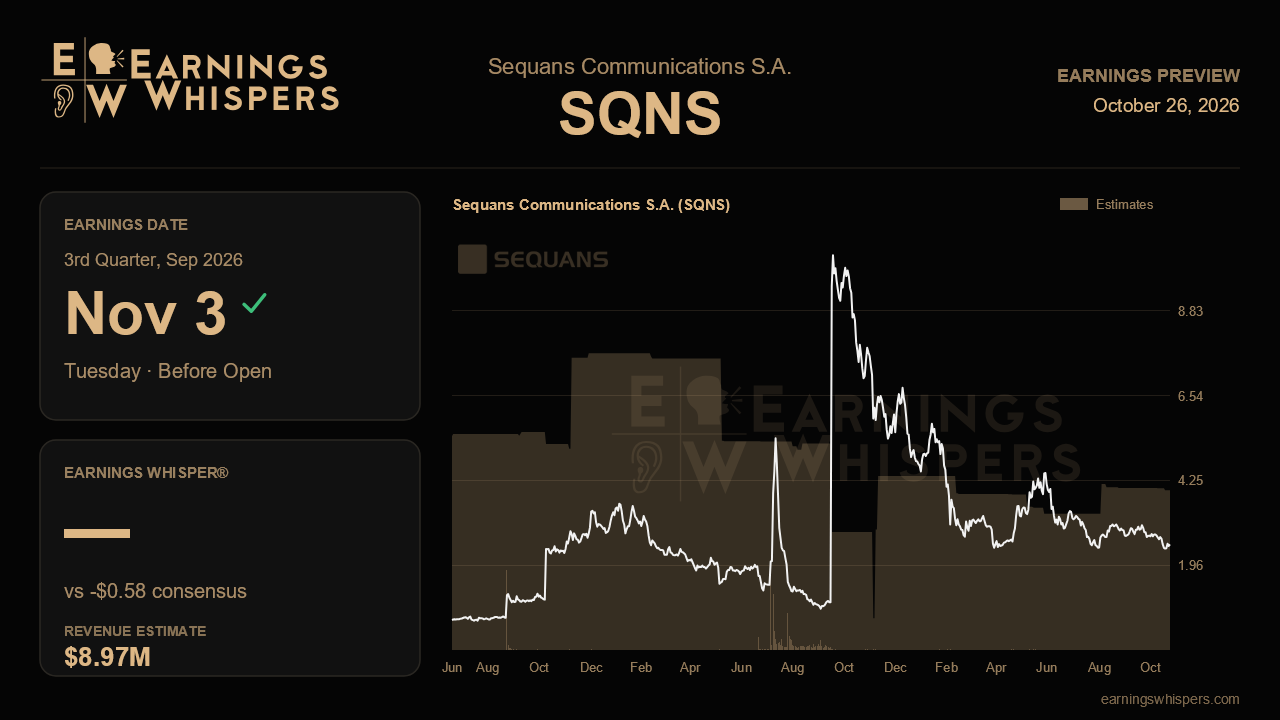
Sequans heads into its third-quarter report with a story that has improved on paper while the stock has gone the other way. Last quarter, management steered the conversation away from its Bitcoin treasury and back to the IoT chip business. It pointed to accelerating product sales, a fast-converting design-win pipeline and a higher revenue outlook. The market has not bought in. Shares have slipped 7% since that report while the S&P 500 was essentially flat. The question now is whether the operating numbers can start to outrun the skepticism.
The Street expects revenue of about $9.0 million. That would more than double the $4.3 million booked a year ago and mark another sequential step up from $7.5 million last quarter. Consensus sits a bit below the midpoint of management's $8.5 million to $10 million guide. That placement matters because management said the top of the range depends on closing a licensing deal. Analysts appear to be modeling solid product growth without fully counting on that deal. A licensing close would therefore be upside, and a miss on product shipments would be a real problem. On the bottom line, consensus calls for a loss of $0.58 per share. That is better than the $0.84 loss a year earlier but wider than last quarter's $0.30 loss. It suggests analysts are not yet assuming much operating leverage.
Margins are the most important swing factor. Gross margin fell to 32.9% last quarter from 37.7% in the first quarter and 64.4% a year earlier. Two forces drove the decline. Product sales, which carry lower margins, are making up a larger share of revenue. Sequans has also been slow to pass rising memory costs on to customers. Management said supply tightness has spread beyond memory into silicon and packaging and is likely to last beyond 2026. If gross margin stabilizes or ticks up on higher volume, it would show the company can grow without giving away profitability. Another leg down would raise doubts about how much of the revenue growth reaches the bottom line. Supply limits could also cap the product upside even if demand holds.
The pipeline metrics deserve close attention. Design wins already in production reached 55% of a pipeline worth more than $300 million, up from 44% two quarters earlier. Backlog now extends into 2027. Continued conversion would support management's view that several of its 40-plus mass-production projects can each generate more than $4 million a year from 2027. The newer RF transceiver and drone-defense story is still early. The first drone program does not ship until early 2027, so the useful evidence this quarter is pipeline growth beyond the 20-plus opportunities cited last time. Management has described that business as carrying margins of roughly 90% or more.
Costs are the other credibility test. Operating expenses of $11.9 million are still above the roughly $10 million quarterly target. Breakeven has already slipped from a fourth-quarter 2026 run rate to sometime in 2027. A visible drop in spending would help restore confidence in that timeline. Further drift would make the delay look less like a timing issue and more like a structural one. The debt-free balance sheet, with $21 million in cash plus a reduced Bitcoin position, gives the company room, but not unlimited room. The CFO transition adds a layer of scrutiny to how the new finance chief frames the outlook.
Sentiment has cooled noticeably. It was solidly bullish heading into the last report and now leans slightly bearish. The stock trades at $2.52, well below its 200-day moving average of $3.25 and near the bottom of its post-earnings range of $2.31 to $3.18. That bar is low, but not trivial. Revenue inside the guide would likely be read as table stakes. What would validate the turnaround narrative is evidence that growth is starting to translate into steadier margins and lower spending, not just more shipments.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Sep-24 | |
| Sep-24 | |
| Sep-23 | |
| Sep-08 | |
| Aug-04 | |
| Aug-04 | |
| Jul-31 | |
| Jul-21 | |
| Jun-02 |
