Teva's Austedo-Led Turnaround Faces A Margin Test As Generics Drag On Third-Quarter Results
Teva walks into its third-quarter report with an awkward split personality. Its innovative drugs are growing fast enough that management has raised product guidance three quarters running, yet the company as a whole is still expected to shrink this quarter. The question for November 3 is whether the branded engine is pulling hard enough to make the shrinking generics business and heavier launch spending look like a temporary detour rather than a ceiling on earnings.
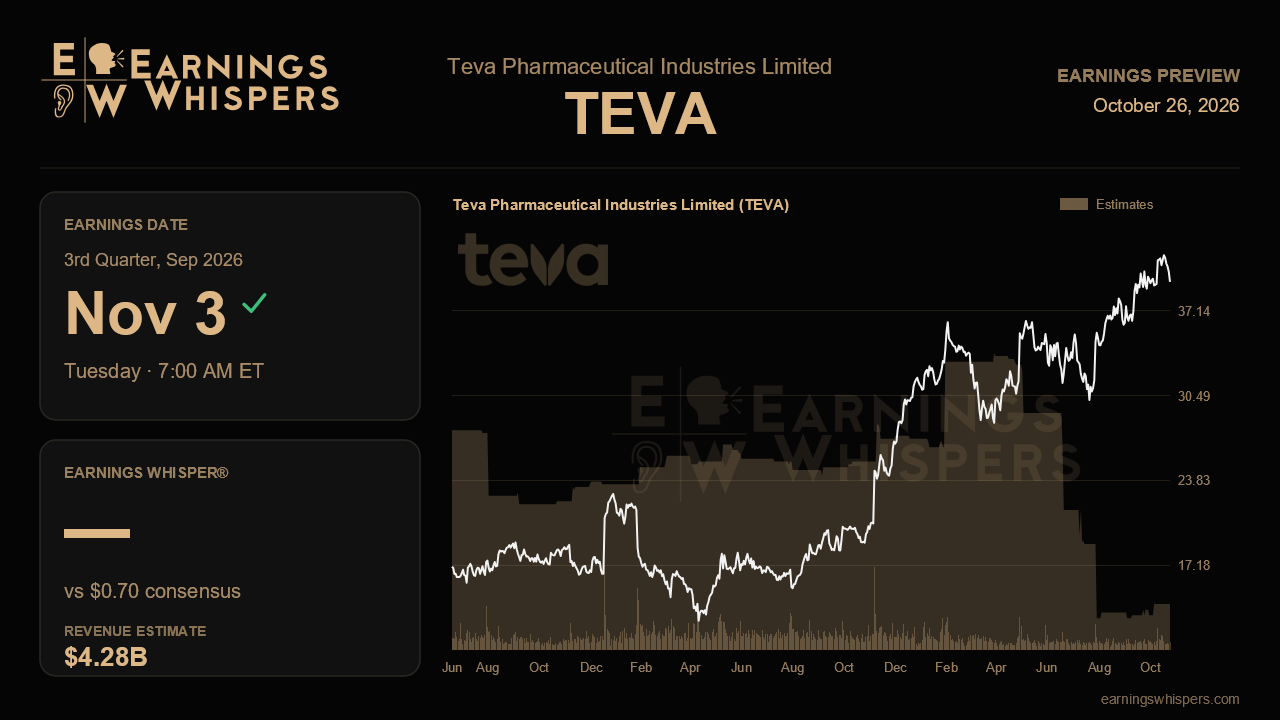
Wall Street expects earnings of $0.70 per share on revenue of $4.28 billion, which would mean a 6.7% decline in profit and a 4.5% drop in sales from a year ago. That is contraction, not stagnation, and it mostly reflects the continued erosion of Revlimid, a roughly $1.1 billion headwind this year. Sequentially the picture is better: revenue would rise from $4.14 billion last quarter, and the bottom line should look far cleaner after the second quarter's breakeven result was flattened by a one-time charge of about $725 million tied to the Amilex acquisition. Full-year guidance calls for $1.91 to $2.11 per share on revenue of $16.50 billion to $16.85 billion. The Street's $1.98 estimate sits slightly below the midpoint of that earnings range, while its $16.71 billion revenue forecast lands a touch above the revenue midpoint. In other words, analysts believe the top line but are hedging on how much of it reaches profit, which is a sensible reading of last quarter's call.
That call set up the central tension. Management lifted Austedo to $2.45 billion to $2.6 billion, Ajovi to $850 million to $870 million and Uzedi to $270 million to $290 million, pushing the trio toward roughly $3.7 billion, up about 17%. Innovative revenue jumped 43% in the second quarter and gross margin widened 80 basis points to 55.4%. Yet operating profit, EPS and free cash flow targets were merely reaffirmed, with operating expenses steered to the high end at about 28% of revenue because of launch investment and less helpful currency. This quarter should show whether gross margin gains can keep absorbing that spending. Another step up in gross margin with expenses holding near 28% would validate the story; slipping margin alongside rising costs would suggest the revenue raises are being bought rather than earned.
Austedo deserves particular scrutiny. Management warned that fourth-quarter sales will likely fall year over year as purchasing patterns and pricing shift ahead of Medicare negotiated pricing in January 2027, and that elevated channel inventory had not fully drained, with normalization pushed into the second half. A clean third quarter with inventory moving down would make that Q4 dip look orderly. Any sign the drawdown is lumpier than expected would revive worries about the 2027 transition. Generics, down 15% last quarter and now guided flat to down low single digits excluding Revlimid and Japan, need to at least stabilize, while growth in a biosimilar lineup that expanded to 15 products would help. Updates on the olanzapine long-acting injectable, with an FDA decision and launch expected in the fourth quarter, the TAPI sale and tariff exposure round out the agenda.
The market has been generous. Shares are up 17.1% since the last report, beating the S&P 500 by more than 14 points, and at $39.41 they trade comfortably above the 200-day average of $34.36, though about 6% shy of the post-earnings high of $42.02. Curiously, sentiment has cooled sharply, sliding from 43.4% bullish to barely positive at 4.8%, suggesting that after the rally, conviction has thinned even as the price climbed.
Ultimately, the report hinges on operating leverage. If Teva can show branded growth translating into margin expansion that outpaces generics softness and launch costs, the turnaround narrative stays intact and the reaffirmed profit targets start to look conservative. If revenue beats again but earnings merely hold the line, investors may conclude the acceleration phase is real at the product level but still unproven at the bottom line.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-21 |
Sanofi & Tevas IBD drug prompts long-term clinical remission in Phase IIb trial
TEVA
Clinical Trials Arena
|
| Oct-20 | |
| Oct-12 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-02 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-28 | |
| Sep-23 |
