AudioEye Beats As AI Efficiencies Drive Margins And First GAAP Profit, But Revenue Growth Slows To 7%
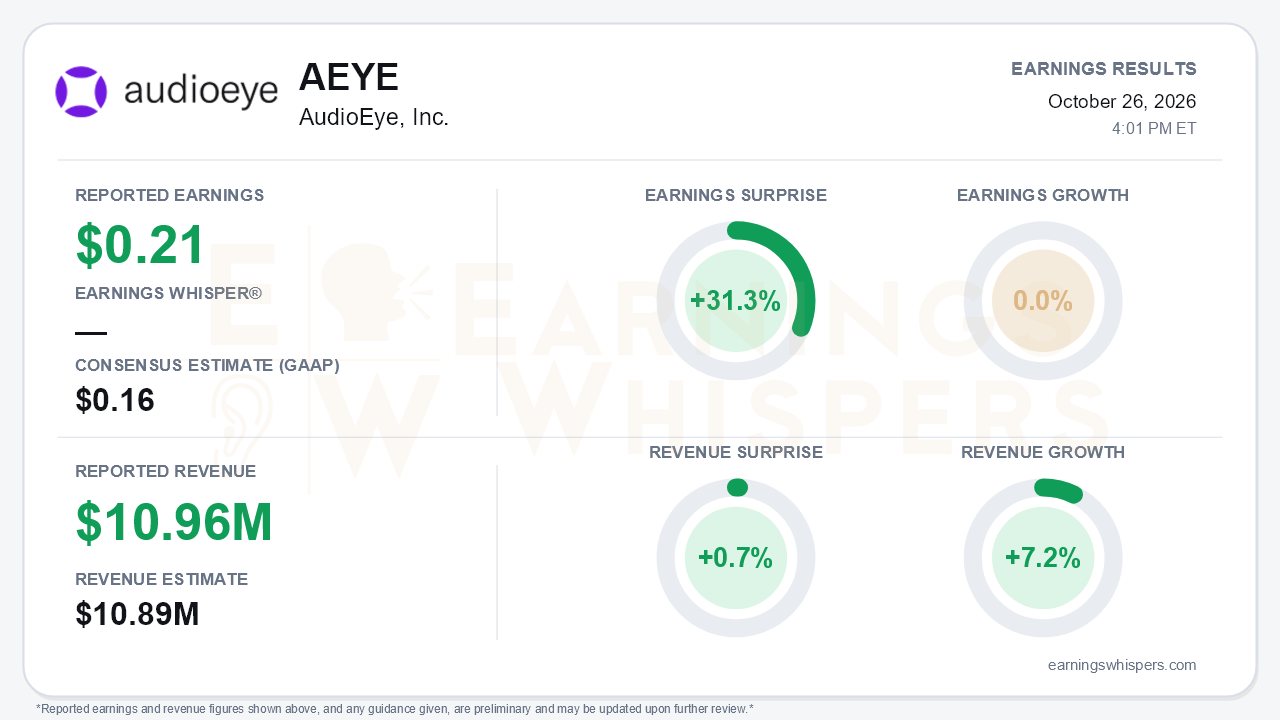
AudioEye (NASDAQ: AEYE) delivered a quarter defined by margin expansion more than top-line momentum. Earnings Whispers recorded third-quarter earnings of $0.21 per share, beating the $0.16 consensus by 31.3%. Revenue of $10.96 million rose 7.2% year over year and edged past the $10.89 million estimate by 0.7%. On that normalized basis, earnings were flat versus a year ago. The company's own figures tell a stronger story. GAAP net income was $990,000, or $0.08 per diluted share, compared with a loss of $0.04 a year earlier. Management's adjusted EPS rose to $0.30 from $0.19. Because the consensus is described as GAAP-based while the company reported both $0.08 GAAP and $0.30 adjusted, investors should be aware that the three per-share figures are not directly comparable. The central tension is that profitability is improving quickly while revenue growth is not.
The quality of the beat comes mostly from costs. GAAP gross margin jumped to 83% from 77% a year ago and 79% in the second quarter. Adjusted gross margin reached 88%. Cost of revenue fell 19% as AI tools absorbed work previously done by people. Operating expenses declined 5%, with selling and marketing and R&D both lower. Adjusted EBITDA of $3.9 million rose 58% at a 35% margin, up from 28% in Q2 and 22% in Q1.
The GAAP turn deserves some scrutiny. Litigation expense of $492,000 is still excluded from the adjusted figures, and the company remains at a $2.0 million GAAP loss for the first nine months. Still, litigation costs fell roughly 50% sequentially after a roughly 40% drop in Q2, and management expects further declines. That suggests the gap between GAAP and adjusted results should keep narrowing.
The revenue picture is where bears have legitimate ammunition. Year-over-year growth slowed to about 7% from 9% in Q2 and 8% in Q1. Enterprise revenue was flat as the company deliberately moves away from non-recurring work. The customer base grew by only about 1,000 sequentially to roughly 130,000. Management also narrowed full-year revenue guidance to $43.6-$43.8 million from $43.5-$44.0 million, leaving the midpoint marginally lower.
The recurring-revenue mix offers a credible counterargument. ARR reached $43.3 million, up 12% year over year, accelerating from 11% in the first half and 9% at the end of 2025. Enterprise ARR growth doubled to 10% from 5% in Q2. Fourth-quarter revenue guidance of $11.4-$11.6 million implies roughly 20% annualized sequential growth. If that holds, the deceleration in reported revenue is largely a mix shift rather than weaker demand.
The forward catalysts lean toward profitability and capital return. Full-year adjusted EBITDA guidance was raised for a fourth straight time:
- It now stands at $13.4-$13.6 million, about 50% growth and above management's original 30-40% aspirational target.
- The fourth-quarter annualized run-rate target rose to more than $17 million from $15 million.
- Free cash flow climbed to $3.5 million from $2.6 million in Q2.
The new $15 million buyback, roughly 15% of shares at current prices, signals confidence. It is ambitious, however, relative to $9.3 million in cash and about $16.2 million in term debt, so execution depends on sustained cash generation.
On products, Agentic Audits and the SDK MCP launched in October, but management said their revenue uplift cannot yet be quantified. Regulation is a potential tailwind, with Hawaii's Act 257 and EU adoption of WCAG 2.2. Concerns about AI-native competitors persist, though management said it has not encountered any so far.
The market had already priced in much of the improvement. Shares rose 30.5% from the $6.19 open after the August report to $8.08 ahead of this release. That leaves the stock 14% above its 200-day moving average and about 5% below its inter-earnings high of $8.50, set just days after the prior report. Investor sentiment improved meaningfully, from -0.34 to -0.12, but remains net negative. That points to skepticism easing rather than investors turning outright bullish. The Earnings Whispers trend signals are mostly positive, with sequential growth, momentum and AVWAP all favorable, while the price trend is neutral.
The bottom line is that AudioEye is executing well on margin expansion and cash generation, with a first GAAP profit, repeated EBITDA guidance raises and a sizable buyback. The open question is whether accelerating ARR and the guided Q4 sequential ramp can reverse slowing reported revenue growth. With the stock entering the report near its quarterly highs, the margin story is largely recognized. The next leg likely depends on revenue growth catching up to profitability.
Read our earnings preview for AudioEye, Inc.: https://www.earningswhispers.com/article/AEYE/20816
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 5 hours | |
| 5 hours | |
| Oct-20 | |
| Oct-20 | |
| Oct-08 | |
| Sep-30 | |
| Sep-24 | |
| Sep-11 | |
| Aug-27 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Jul-30 | |
| Jun-25 |
