Bank Of Hawaii Narrowly Misses EPS Estimates As Its 10th Straight Margin Gain Is Overshadowed By Deposit Outflows, A Credit Blip, And A Dropped NIM Target
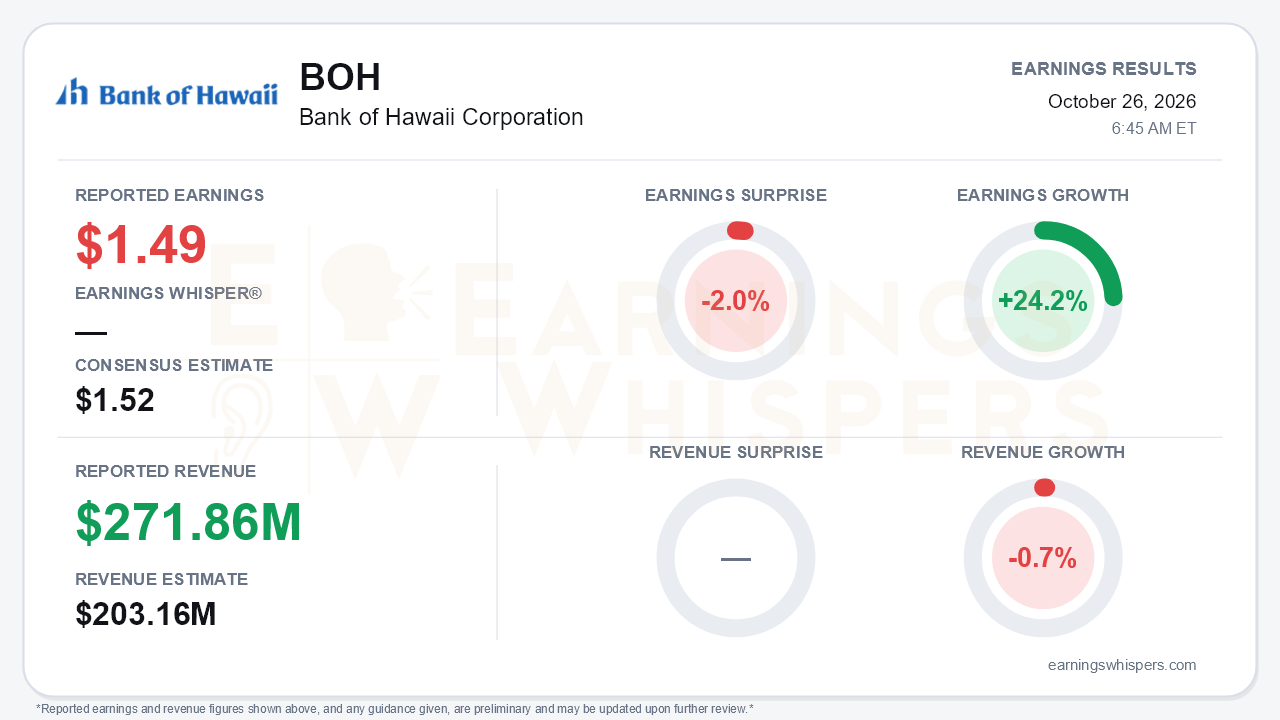
Bank of Hawaii (NYSE: BOH) reported third-quarter earnings of $1.49 per share. That was 2.0% below the $1.52 consensus, but earnings still grew 24.2% from a year earlier. The year-over-year comparison remains strong because net interest income rose to $156.1 million from $136.7 million and the efficiency ratio improved to 56.5% from 61.5%. The sequential picture is different. EPS rose only two cents from $1.47 in the second quarter, after a 17-cent jump from the first quarter's $1.30. The engine is still running, but it is no longer accelerating. That is the central tension: a tenth consecutive quarter of margin expansion arrived alongside deposit outflows, a single-loan credit spike, and a missing margin target, all of which leave the forward story less certain.
The revenue figures need context. Earnings Whispers recorded revenue of $271.86 million, a 33.8% beat against a $203.16 million consensus and a 0.7% decline from a year ago. That revenue figure includes gross interest income. The more familiar bank measure, net interest income plus fees, was about $198.8 million, up from roughly $182.6 million a year earlier. The revenue 'beat' therefore says more about how revenue is defined than about any upside surprise in operations. The EPS miss also had a non-operating component. Pretax income rose 1.9% sequentially, but the effective tax rate climbed to 23.24% from 22.31% because of valuation allowances on low-income housing investments. Fee income slipped 1.4%, and adjusted expenses rose 0.5%. Pre-provision net revenue increased just 0.9% from the linked quarter.
The call explained the slowdown. Net interest margin rose 4 basis points to 2.82%, helped by fixed-rate asset repricing and new loans originated at a 5.89% weighted average rate. However, management had cited a pace of roughly 5 basis points per quarter on the prior call. It also had not repeated the roughly 2.90% year-end NIM target, which had been stated on each of the three previous calls. Funding is the reason to watch closely. Period-end deposits fell $411 million. That drop included about $200 million of deliberate runoff of high-cost public funds, but commercial deposits also declined about $190 million. Noninterest-bearing deposits slipped to 26.5% of the total. The unfavorable mix shift continued for a second quarter and accelerated. Other debt jumped to $853 million from $508 million. CD costs have also turned: certificates are now maturing near 2.90% and rolling over near 3%. Management expects a deposit beta of about 34% as rates rise, so higher rates help now but turn into a headwind once deposits fully reprice. Management said sustained growth will require more organic deposit, loan, and fee contribution rather than repricing alone. Loan growth slowed to 2.4% annualized from 2.6%, and Hawaii was described as a stable but modest-growth market with mixed tourism trends.
Credit headlines look worse than the underlying detail. Non-performing assets more than tripled to $43.4 million, or 30 basis points of loans, because of a single $32.5 million commercial mortgage. Management says a sale is pending and expects any loss to be immaterial and already reserved. Criticized assets improved to 2.37% from 2.81%, and net charge-offs were a modest 9 basis points. Bears do have one smaller data point to cite: consumer loans 90 days or more past due rose to $16.6 million from $14.1 million, led by residential mortgages. Book value is another pressure point. A larger accumulated other comprehensive loss reduced tangible book value per share to $36.97 from $38.01 and cut tangible common equity to tangible assets to 6.09% from 6.30%.
The positives are real. The Board added $200 million to the buyback authorization, and $20 million of repurchases are planned for the fourth quarter. The normalized fee guide rose to about $44 million, wealth fees are up 11.5% year to date, and expenses are tracking near the low end of guidance. Management also expects the full-quarter effect of the September rate hike and the public-funds runoff to support fourth-quarter yields.
The market had already turned skeptical before the release. Shares fell 15.1% from the $83.20 opening price after the July report to $70.60, which is 7.6% below the 200-day moving average of $76.38. The stock bottomed at $65.07 on October 14 and sits 8.5% above that low, but remains well below the $84.22 quarterly high. Investor sentiment swung from moderately positive (0.30) to mildly negative (-0.12), a meaningful shift. The Earnings Whispers price and AVWAP trend readings are negative, consistent with the selling pressure of the past quarter.
The bottom line is that Bank of Hawaii's repricing story is intact but maturing. Margins and earnings are still rising, and the expanded buyback signals confidence. However, a slower NIM pace, deteriorating deposit mix, rising borrowings, and the unmentioned 2.90% target suggest the easiest gains are behind it. With the stock well below its 200-day average and sentiment now negative, the next leg depends on whether deposits stabilize, not on another few basis points of asset repricing.
Read our earnings preview for Bank of Hawaii Corporation: https://www.earningswhispers.com/article/BOH/20631
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-03 | |
| Oct-02 | |
| Aug-04 | |
| Jul-27 | |
| Jul-27 | |
| Jul-27 | |
| Jul-27 | |
| Jul-15 | |
| Jul-06 | |
| Apr-21 |
