UL Solutions Must Prove Consumer Rebound And Margin Gains Can Outrun A 15% Selloff
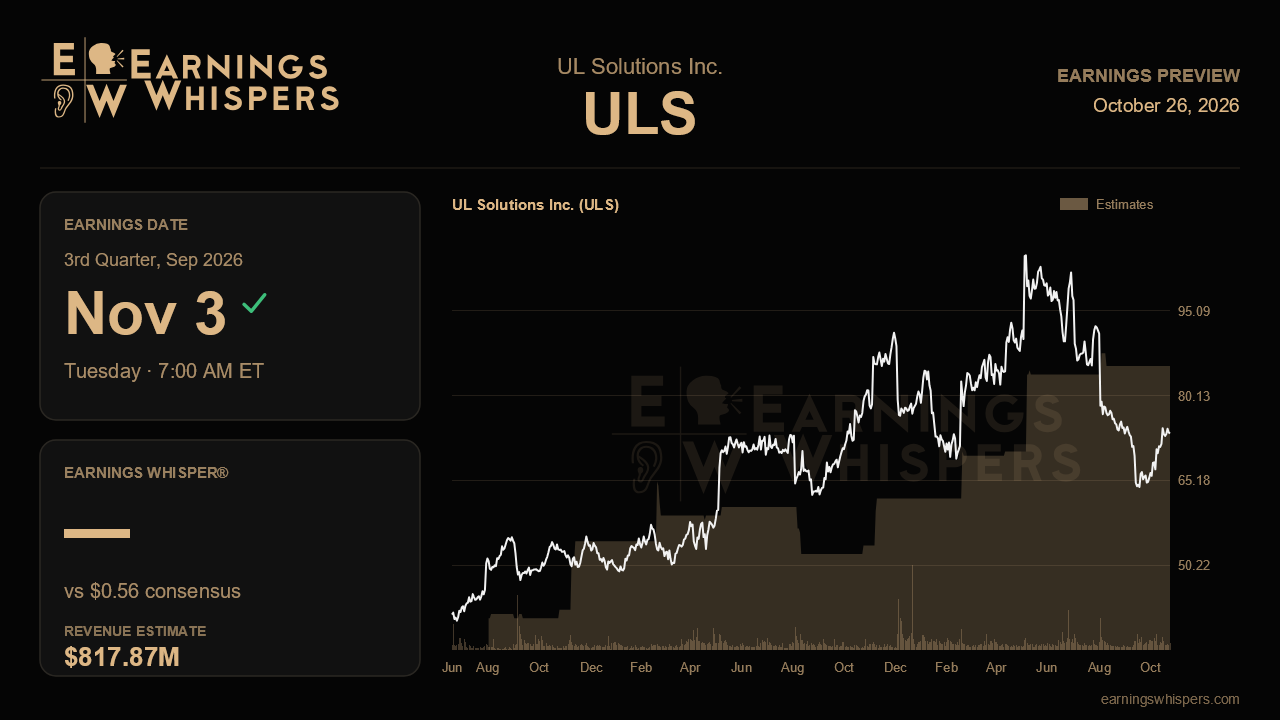
UL Solutions heads into its third-quarter report with an awkward disconnect between its operating story and its share price. Last quarter the safety science company posted record revenue, record adjusted EBITDA and a sharp rebound in its consumer business, yet the stock has dropped 15.5% since then while the S&P 500 barely moved. The November 3 release, due before the opening bell, needs to show whether the market has spotted a real crack in the narrative or simply marked down a business that is still executing.
The Street is looking for adjusted earnings of $0.56 a share on revenue of about $817.9 million. That implies roughly 16.7% earnings growth from $0.48 a year ago on revenue growth of only 4.5%, so the quarter is again expected to be a margin story more than a top-line one. Revenue would be essentially flat with the second quarter's record $816 million, which is a modest bar, but reported growth is being held down by the April divestiture of the EHS software business. The organic figure will be the more honest gauge. Management last affirmed full-year guidance for mid-single-digit organic growth and an adjusted EBITDA margin near 27%, and consensus appears consistent with that outlook rather than stretching beyond it.
The consumer segment is the first test. Organic growth there jumped to 6.2% in the second quarter from 3.0% in the first, and segment margin climbed to 21.3%, helped by exits from low-margin work, restructuring and demand tied to AI data centers, particularly power supplies and HVAC and cooling equipment. One strong quarter after a weak one could be noise. A second quarter of mid-single-digit organic growth with margins holding near the low 20s would suggest the mix shift is durable; a slide back toward the first quarter's 3% pace would undercut the most encouraging part of the prior call.
Industrial is the opposite question. It remains the highest-margin, fastest-growing segment, but organic growth eased to 7.2% from 8.2%, and management warned that advisory weakness tied to US solar and wind work would likely persist through the second half. Further deceleration toward the low single digits would be more troubling than a mild drift. Cost discipline matters too: SG&A rose $23 million last quarter on heavier incentive pay and professional fees, and if those costs keep climbing, the operating leverage behind the earnings forecast gets harder to deliver.
Capital allocation offers a quieter signal. Management lifted planned capital spending to about 8.5% of revenue from a prior 7% to 8% range, pointing to new labs such as the Toyota City automotive EMC center as evidence of demand worth building for. Trailing free cash flow of $436 million gave it room to do so. Continued strong cash conversion despite the heavier spending would validate that confidence, while any update on the pending Eurofins E&E acquisition and the planned DQS sale will shape expectations for integration costs in the fourth quarter.
Sentiment has soured, with bearish readings roughly doubling from the prior quarter. The stock sits at $73.44, below its 200-day moving average of $82.80 and well under the entire range it traded in before the last report, though it has recovered from a post-earnings low of $63.17. That reset lowers the bar somewhat. Ultimately, the report hinges on whether consumer strength and margin expansion can offset slowing industrial advisory work. If the company again delivers its mid-single-digit organic growth with margins tracking toward 27%, the selloff will look overdone; if consumer momentum fades just as industrial cools, the market's skepticism will have been early rather than wrong.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-12 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-24 | |
| Sep-23 | |
| Sep-17 | |
| Sep-16 |
