Accel's First Chicago Readout Meets A Skeptical Market And A Lower Earnings Bar
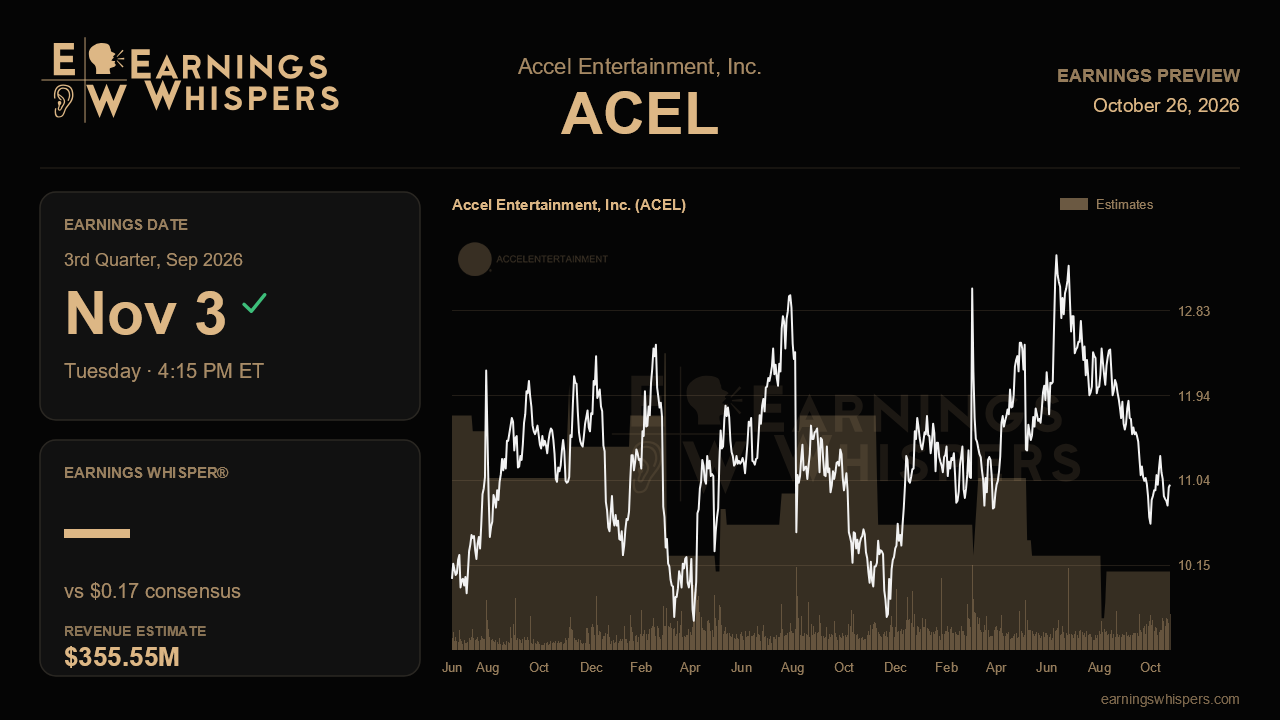
Last quarter, Accel Entertainment pulled forward its most important growth story by roughly a year. Management said Chicago, long framed as a late 2026 or early 2027 opportunity, would see its first establishments go live within weeks, and that Accel already held 17 of the 39 licenses the city had approved. Since then, the stock has fallen 11.6%, trailing the S&P 500 by about nine and a half points. The September-quarter report, due after the close on November 3, is the first chance to see whether the Chicago launch is real revenue or still a promise. It is also the first report under Mark as CEO, after Andy moved to chairman in August.
The Street is not asking for much on the bottom line. Consensus calls for earnings of $0.17 a share, down about 19% from $0.21 a year ago, on revenue of $355.6 million, up 7.8%. That revenue figure sits below the $368.1 million Accel posted last quarter, so analysts are effectively modeling a sequential step down even as the year-over-year growth story holds. Accel does not provide numeric guidance, which leaves the earnings line especially exposed to noise. Last quarter's $0.15 absorbed a $2.5 million equipment write-off and a $5 million mark-to-market loss on contingent earn-out shares, both added back to adjusted EBITDA. That makes adjusted EBITDA the cleaner scorecard. It climbed from $51 million in the year-ago quarter to a record $59 million last quarter, and holding something in the high $50 millions would argue the operating trend is intact regardless of where reported EPS lands.
Chicago aside, the narrative rests on Illinois quality. Hold per day rose to $992, up 9% from a year earlier, and the location count grew sequentially for the first time in about two years. Management presented this as the end of a pruning cycle and the start of growth led by better locations. Another sequential gain in hold per day alongside stable or rising location counts would validate that view. A slip back toward location losses would suggest the turn was premature. Developing markets matter too: Nebraska grew 55% and Georgia 47% last quarter, and management now describes them as genuine EBITDA contributors rather than just revenue adders.
Nevada is the known soft spot. Hold per day there fell nearly 16% as Accel rapidly expanded into convenience stores, including the roughly 600-terminal Green Valley Grocery route, which carry lower hold than participation bars. Management described a six to twelve month quality upgrade, so continued dilution would not be alarming, but signs that the decline is narrowing would help. Cash flow deserves a careful read as well. The $17 million green tax credit purchase that management said would shift into this quarter should weigh on reported operating cash flow, so the comparison that matters is whether underlying conversion keeps improving from last quarter's 45%. Capital spending should track the reaffirmed $60 million to $70 million annual range, well below the $89 million spent in 2025.
Sentiment has soured notably. Bearish readings roughly doubled from the prior quarter, and the stock at $11 sits below its 200-day moving average of $11.71 and near the bottom of its post-earnings range of $10.59 to $12.85, a range that has shifted lower from the prior quarter's $11.16 to $14.00. That combination of improving fundamentals and a declining share price leaves room for a positive reaction if the numbers confirm the story, but it also shows how little benefit of the doubt the market is extending.
The decisive question is whether Chicago has moved from licenses to live terminals generating revenue, and whether management can describe a credible ramp. If that evidence arrives alongside steady Illinois hold and record-level EBITDA, last quarter's inflection narrative holds. If Chicago remains largely prospective, the skeptics will have more time to make their case.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-07 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-20 | |
| Jul-14 | |
| Jul-08 | |
| Jul-07 | |
| Jun-03 | |
| May-07 | |
| May-05 | |
| May-05 | |
| May-04 |
