Xometry's Q3 Test: Can Marketplace Margins Catch Up To Its Accelerating Growth?
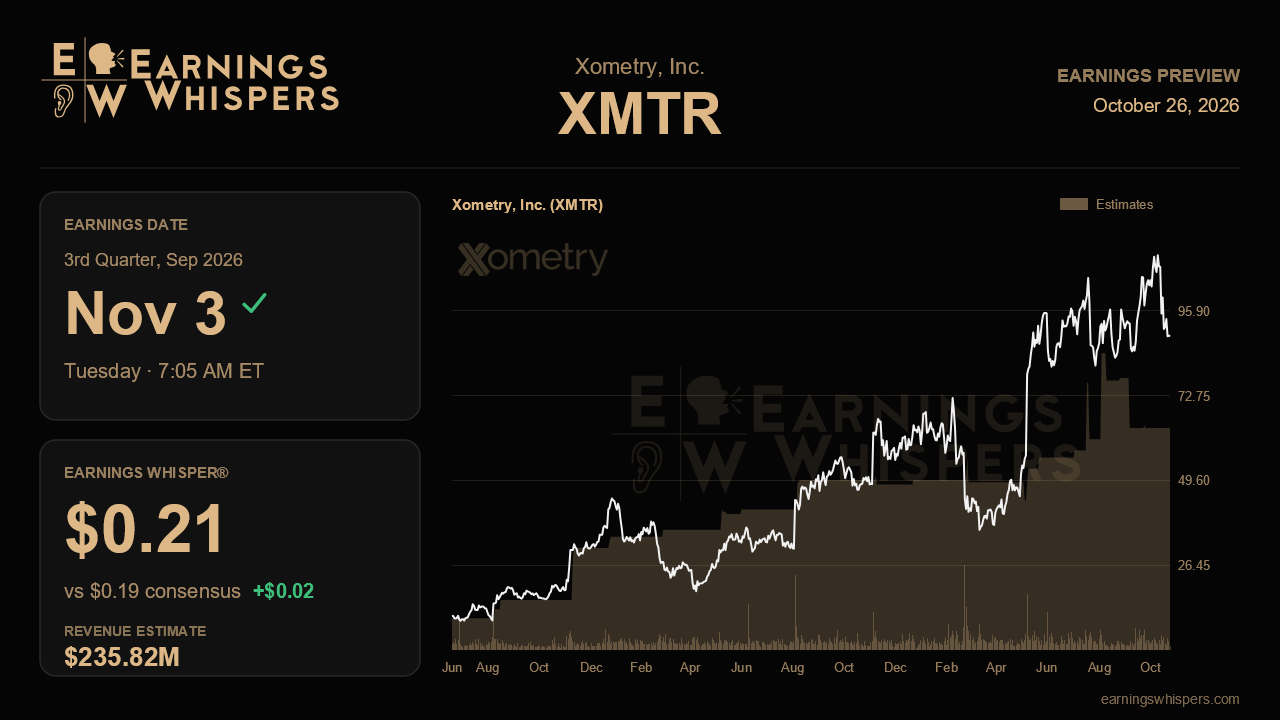
Xometry heads into its third-quarter report with a peculiar problem for a company on a hot streak. Management has raised its full-year outlook twice in a row, revenue growth has accelerated for four straight quarters, and yet the stock has gone nowhere since the last report. The November 3 release, due before the opening bell, will show whether that disconnect reflects skepticism about how long the acceleration can last or simply a market waiting for proof that profitability can keep pace.
The Street is looking for non-GAAP earnings of $0.19 a share on revenue of $235.8 million, which would be roughly 30.5% growth from a year ago. That is strong by any industrial standard, but it is a clear step down from the 41% pace posted in the second quarter. The deceleration is baked into management's own numbers. The company guided third-quarter revenue to $234 million to $236 million, and consensus sits at the top of that range, so analysts are effectively assuming Xometry delivers its usual upside without much room to spare. The Earnings Whisper of $0.21 is a touch above consensus, hinting that the more aggressive expectations lean toward a modest beat rather than a blowout.
The full-year math sharpens the picture. Xometry lifted its 2026 revenue outlook to roughly $913 million to $920 million from about $872 million to $879 million, and set adjusted EBITDA guidance at $60 million to $62 million. With first-half EBITDA of about $24.6 million, the back half needs to produce roughly $35 million to $37 million, or around $18 million a quarter versus $14.1 million in the second quarter. That is the real test of operating leverage. Revenue growth slowing to around 30% while EBITDA steps up sharply only works if gross margin improves and marketing efficiency holds.
That is why marketplace gross margin may matter more than the top line this time. It was stuck at 34.7% in both the first and second quarters, still below the 35.7% peak from a year earlier, even as management promised expansion into its 35% to 40% target range in the second half. A reading above 35% would validate that pledge and suggest the improved AI pricing models, which management said sharpened CNC cost accuracy by about 15%, are translating into better spreads. A flat or lower print, especially with Siemens-related product costs layered into the second half, would raise questions about whether growth is being bought with price. Advertising spend, which fell to a record low 3.4% of marketplace revenue, is the other efficiency gauge; any meaningful rebound would undercut the leverage story.
Demand signals deserve close attention as well. Active buyer net additions hit a 10-quarter high last period and accounts spending $50,000 or more posted a record 175 net adds, while revenue per buyer climbed 21%. Continued strength there, along with commentary on robotics and defense customers, would support the idea that the slowdown in guidance reflects conservatism rather than fading momentum. Investors should also want early color on the Siemens Design Center integration, which management framed as a 2027 contributor, plus any progress narrowing losses in the international segment and reviving the modest-growth Thomas services business.
Sentiment has cooled, slipping from mildly bullish before last quarter to mildly bearish now, and the stock's 0.3% dip roughly matches the broader market. At $88.88 it sits above its 200-day moving average but in the lower half of its post-earnings range, well below the $112.94 high. That combination suggests the market has not fully priced the raised outlook. The central question is whether Xometry can show margin expansion alongside 30%-plus growth. If it can, the case for another guidance raise strengthens; if margins stall, the acceleration narrative starts to look like it has peaked.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Oct-09 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Sep-19 | |
| Sep-15 | |
| Sep-13 | |
| Sep-09 | |
| Sep-08 | |
| Aug-25 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
