Alamar Biosciences Faces A Higher Bar On Growth As Bearish Sentiment Builds
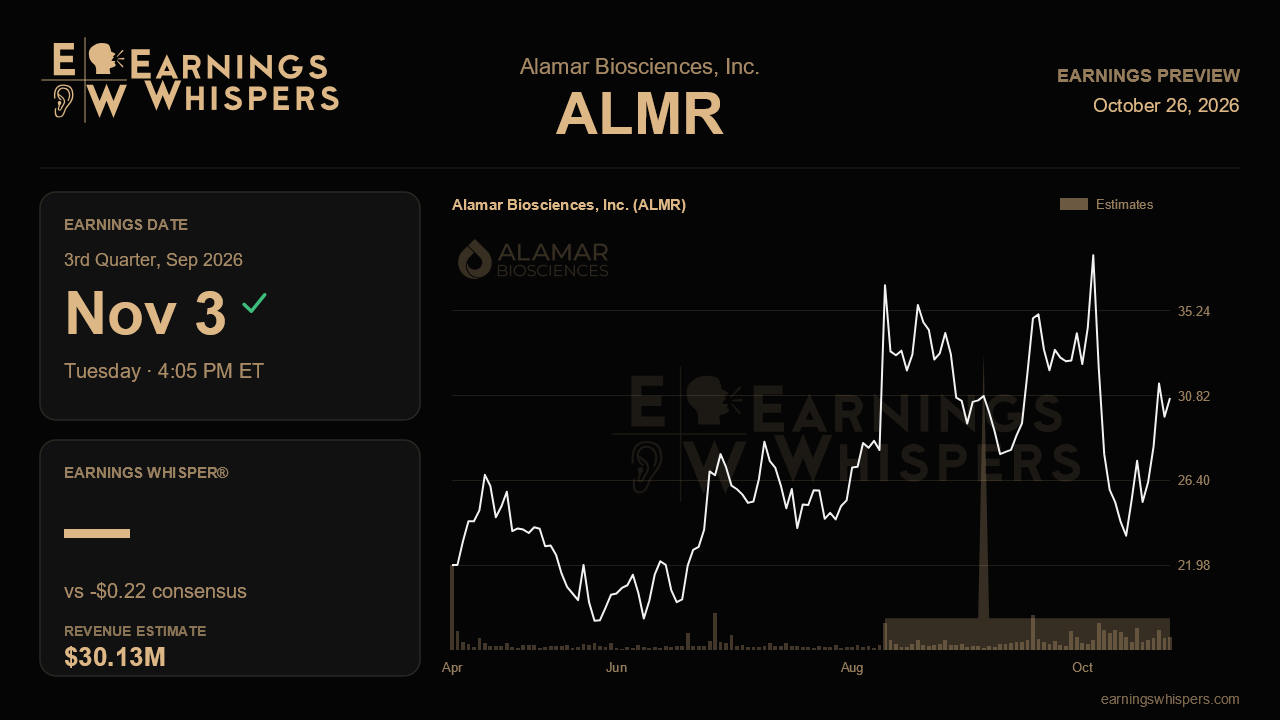
Alamar Biosciences heads into its September-quarter report with an unusual split between the stock and the mood around it. Shares have gained nearly 6% since the last report while the S&P 500 slipped about 2%. At the same time, sentiment has turned sharply more skeptical. That combination makes the November 3 release, due after the close, less about whether the proteomics company can hit a modest set of numbers and more about whether it can show that its commercial story is gathering speed.
The Street's bar is not demanding on its face. Analysts expect a loss of $0.22 per share, identical to the loss posted last quarter, on revenue of about $30.1 million. That would be roughly 2% sequential growth from the $29.4 million reported in the prior period. For a commercial-stage company trying to establish its protein detection platform as an industry standard, a quarter of only incremental top-line progress with no improvement in per-share losses would be acceptable but hardly inspiring. Management has not issued explicit guidance that frames these estimates. Without year-ago comparisons to lean on, the market has little outside reference beyond the consensus itself, which puts more weight on how the quarter's results are explained.
That explanation matters because flat losses on slightly higher revenue raise an obvious question about operating leverage. If revenue grows while the loss per share holds steady, spending is rising roughly in step with sales. That can be perfectly reasonable for a young platform company investing in its commercial footprint and product development. But at some point investors want to see the gap narrow. A result that beats on revenue while holding expenses in check would support the idea that each additional dollar of sales is becoming more profitable. A revenue shortfall paired with an unchanged loss would suggest the cost base is outpacing demand. Equally important will be the quality of revenue. Some sales recur as customers keep using the platform, while others come from one-time purchases. Any color management offers on that mix, on customer adoption and on the pace of new placements will tell investors more about durability than the headline figure alone.
The expectations picture is where this report gets interesting. Bearish sentiment has climbed to roughly 46% from about 7.5% heading into the prior quarter, a meaningful shift in tone even as the shares outperformed. Part of that may reflect the stock's volatility. Since the last report it has traded between about $23 and nearly $40, a much wider and higher band than the prior quarter's range of roughly $19 to $29. At $30.69 the stock sits comfortably above its 200-day moving average of $26.72, which points to an intact longer-term uptrend. It is also well off its post-earnings peak, so it is nowhere near a breakout. The market has rewarded the name, but it has also shown it can give back gains quickly.
That leaves a setup in which a clean quarter could catch skeptics offside, while any wobble could feed the caution already building in sentiment. The central issue is whether Alamar can show that revenue is scaling faster than its cost structure. Steady sequential growth, signs of recurring demand and a loss that at least holds the line would keep the growth narrative intact. Stalled sales or widening losses would hand the bears a more concrete argument than the one they appear to be making now.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-28 | |
| Oct-26 | |
| Oct-08 | |
| Oct-05 | |
| Sep-24 | |
| Sep-01 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-05 | |
| Jul-28 | |
| Jul-15 | |
| Jul-14 |
