Astera Labs Must Prove Its 40% Scorpio-Driven Revenue Leap As Shares Sink Toward Lows
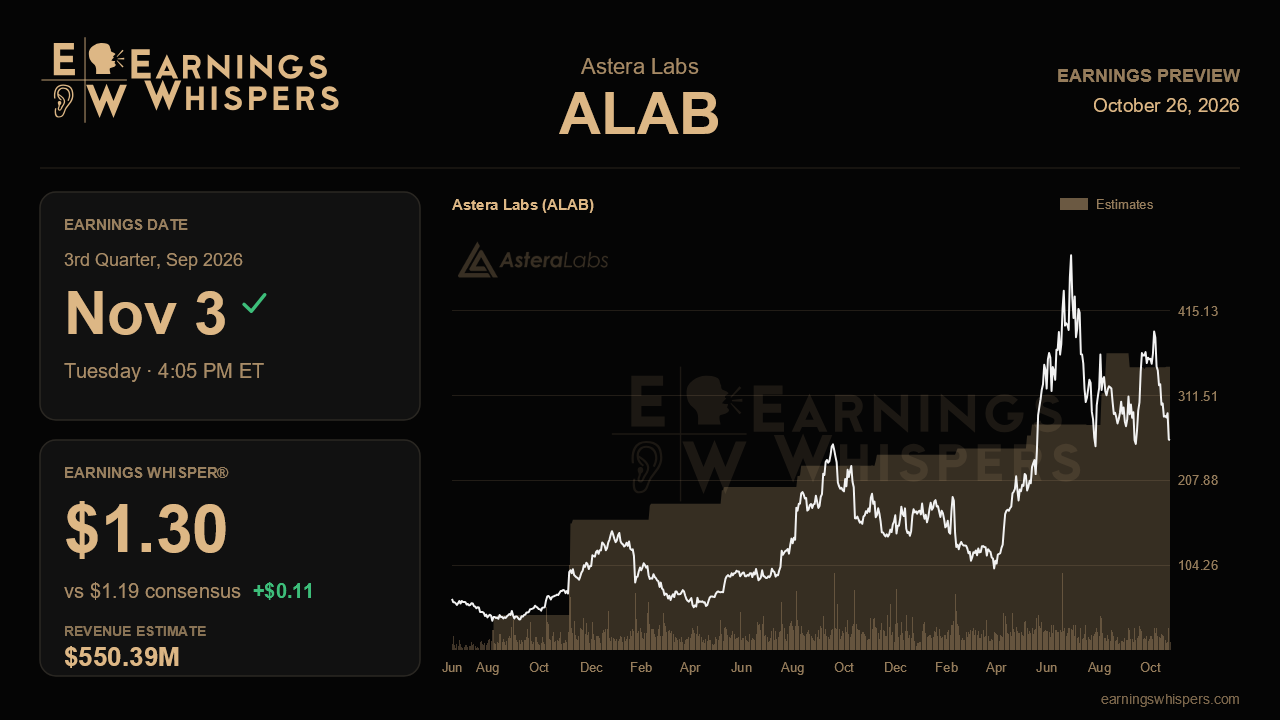
Few semiconductor companies have handed investors a forecast as aggressive as the one Astera Labs delivered last quarter. The market's response has been puzzling. Management guided third-quarter revenue up roughly 40% sequentially on the back of its Scorpio X switch reaching volume production. Since then, the stock has fallen about 26%, while the S&P 500 slipped only 2%. That gap between operating momentum and share price sets up the November 3 report, due after the close, as a test of whether the growth story is real and durable or whether the market is right to doubt it.
Wall Street expects non-GAAP earnings of $1.19 per share on revenue of $550.4 million. Revenue would be up about 139% from the $230.6 million reported a year ago. Both figures sit almost exactly at the midpoint of management's guidance, which called for $1.16 to $1.21 per share on revenue of $540 million to $560 million. Analysts have adopted the company's outlook wholesale rather than leaning above it. The whisper number of $1.30 is more ambitious. It sits well above the top of the guided range, so the informal bar is a clean beat rather than simple delivery. Astera has built that habit: its second-quarter revenue of $392.4 million cleared its own guidance of $355 million to $365 million.
The core of the quarter is Scorpio. Last quarter, management said the Scorpio family would become its largest product line in the third quarter, a full quarter earlier than previously signaled. It also expected Scorpio X to overtake Scorpio P for the first time. Confirmation of both milestones would validate the claim that the switch ramp is broad rather than tied to one program. So would evidence that Astera's more than ten Scorpio X customers are expanding toward additional ramps by year end. Commentary that the ramp is lumpy or concentrated in a single hyperscaler would undercut the step-up. The same goes for any hint that fourth-quarter growth flattens after the third-quarter surge. Investors should also look for PCIe 6 to keep climbing beyond the more than half of revenue it reached in the second quarter. Aries, the retimer franchise that set a record last quarter, needs to hold up as Scorpio takes the lead.
Margins are the one acknowledged soft spot. Non-GAAP gross margin fell from 76.4% in the first quarter to 73.7% in the second. Guidance points to about 72% as switches and modules dilute the mix, with a non-cash Amazon warrant charge costing roughly 200 basis points. Management has framed 70% as the long-term destination, so a print near 72% is not a problem. A sharper drop would raise questions about pricing on the newer products. The offset is operating leverage. Operating expenses are guided up to $156 million to $160 million, yet operating margin is expected to expand to about 43% from 39.1%. Hitting that figure is likely where any upside to the whisper would come from.
Sentiment has warmed only slightly, moving from mildly bearish before the last report to essentially neutral. That is a muted reaction to a quarter that brought pulled-forward milestones and a large guidance raise. At $257.16, the shares sit just above the 200-day moving average of $252.06. They are within about 2% of the post-earnings low of $251.63, far beneath the $401.74 high. The stock is resting on support, and a disappointing outlook could break it.
The secondary catalysts deserve updates too: the new Leo CXL win at a US hyperscaler, the 800G Taurus cable module ramp in the second half, and the firming optical roadmap for 2027. Still, the verdict rests on one question. Can Astera show that the Scorpio X ramp extends into the fourth quarter at scale? Guidance implying further sequential growth, alongside margins holding near plan, would argue the selloff priced in a slowdown that is not happening. A guide that stalls would suggest the market saw the peak coming first.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 30 min | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-25 |
