Astera Labs Beats And Raises Again, But The Lead Scorpio X Ramp Is Maturing As Growth, Margins And Spending Shift
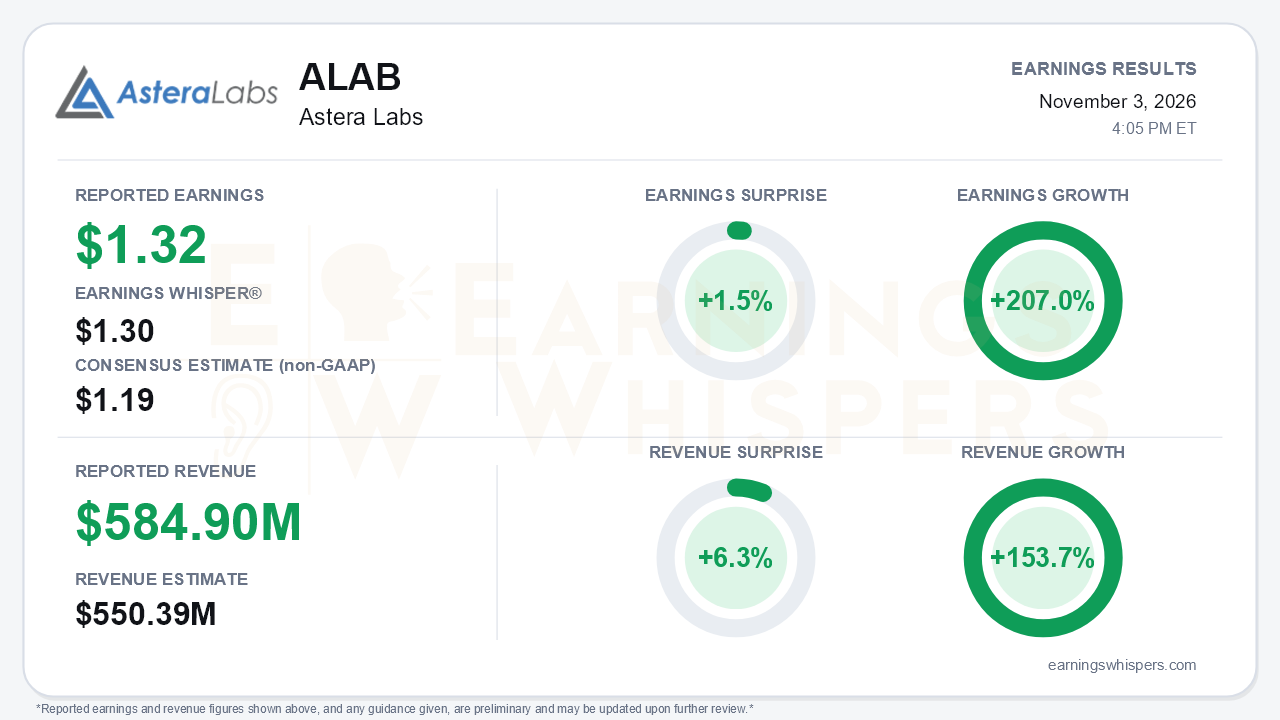
Astera Labs delivered another beat-and-raise, but the quarter answered one question and opened another. Non-GAAP earnings of $1.32 per share topped the $1.19 consensus and edged past the $1.30 Earnings Whisper number, a 1.5% surprise. Revenue reached a record $584.9 million, 6.3% above the $550.39 million consensus. Earnings grew 207.0% year over year on revenue growth of 153.7%. Guidance for fourth-quarter revenue of $730 million to $750 million, with non-GAAP EPS of $1.62 to $1.66, again landed above estimates. The central tension is that sequential growth peaked this quarter. Revenue rose 49% from Q2, after a roughly 27% step-up the prior quarter. The Q4 midpoint implies about 27% again. Management also conceded that the first Scorpio X platforms have largely completed their initial ramps.
The quality of the beat holds up better than the narrow EPS surprise against the whisper suggests. Revenue cleared the company's own $540 million to $560 million guide by a wide margin. Non-GAAP operating margin expanded to 44.7% from 39.1% in Q2 and 41.7% a year ago. GAAP operating income roughly doubled sequentially to $179.1 million. GAAP EPS of $0.99 understates that leverage because Q3 carried a tax provision, while Q2 benefited from a $50.3 million tax benefit. Operating cash flow hit a record $179.2 million. Beneath the headline, though, non-GAAP gross margin slid to 72.4%, from 73.7% in Q2 and 76.4% a year ago, reflecting mix and Amazon warrant contra-revenue. Receivables more than tripled since December to $284 million, and inventory climbed to $201 million. Those are consistent with a steep ramp but worth monitoring as growth normalizes.
The product mix is shifting quickly. Scorpio fabric switches became the largest product family and passed a $1 billion annualized run rate. The X-Series overtook the P-Series, as management had previewed last quarter, and the P-Series still grew double digits with similar growth expected in Q4. Scorpio X is now shipping in pre-production to a second hyperscaler, with Q4 backlog from additional customers. That matters because the CFO's remark about initial deployments implies 2027 Scorpio X growth must come from new platforms and new customers. When an analyst raised concern that the lead customer's current-generation build peaks around 1Q27, management declined to comment. Bears have legitimate ammunition there.
Management's answer was a much broader roadmap, delivered with a more expansive tone that recast Astera as a rack-scale infrastructure platform rather than a fabric supplier. Orion, a compute-agnostic rack reference architecture, carries more than $100,000 of Astera content per 80-GPU rack and reaches customers through OEM and ODM partners beginning in Q1 2027. Management expects it to be margin-accretive but deferred revenue sizing to the next call. Several other vectors followed:
- First optical products sample in Q4, with revenue expected in the second half of 2027.
- Leo 2 is shipping in pre-production volumes, with a volume ramp expected mid-2027.
- Custom silicon engagements have grown to more than 10, with volume in 2028.
- Management introduced a framework of doubling silicon content per accelerator each generation, from more than $1,000 today.
The credible growth story comes with a timing gap. Most of these vectors are not revenue-material until late 2027 or 2028. Meanwhile, non-GAAP operating expenses jump to $194 million to $200 million in Q4 from about $162 million in Q3, and gross margin is guided toward a 70% long-term target. Industry constraints in wafers, power and memory, along with optical consolidation such as Marvell-Lumentum, add further risk.
The market setup is more complicated than the surprise implies. Shares were $229.67 heading into the report, down 34.1% from the $348.36 open after the August release. They sat roughly 10% below the 200-day moving average and just 1.6% above the inter-earnings low of $226.00, set the day before the report. That low came less than a month after a quarter high of $401.74 on October 6, so the stock gave back nearly 43% in a matter of weeks. Investor sentiment improved from modestly negative to roughly neutral, a meaningful but not euphoric shift. The Earnings Whispers trend readings lean positive on sequential growth and momentum, while AVWAP remains negative, reflecting the damage in price.
The bottom line is that Astera Labs again outran expectations on revenue, operating leverage and guidance, and the selloff suggests investors were braced for worse. The debate now shifts from whether the Scorpio ramp is real to what replaces it. Decelerating sequential growth, eroding gross margin and rising spending must carry the story until Orion, optics, Leo and custom silicon begin contributing in 2027 and beyond.
Read our earnings preview for Astera Labs: https://www.earningswhispers.com/article/ALAB/21542
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-30 | |
| Oct-27 | |
| Oct-26 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 |
