Assurant's Record Run Meets A Tougher Third Quarter As Street Braces For Earnings Dip
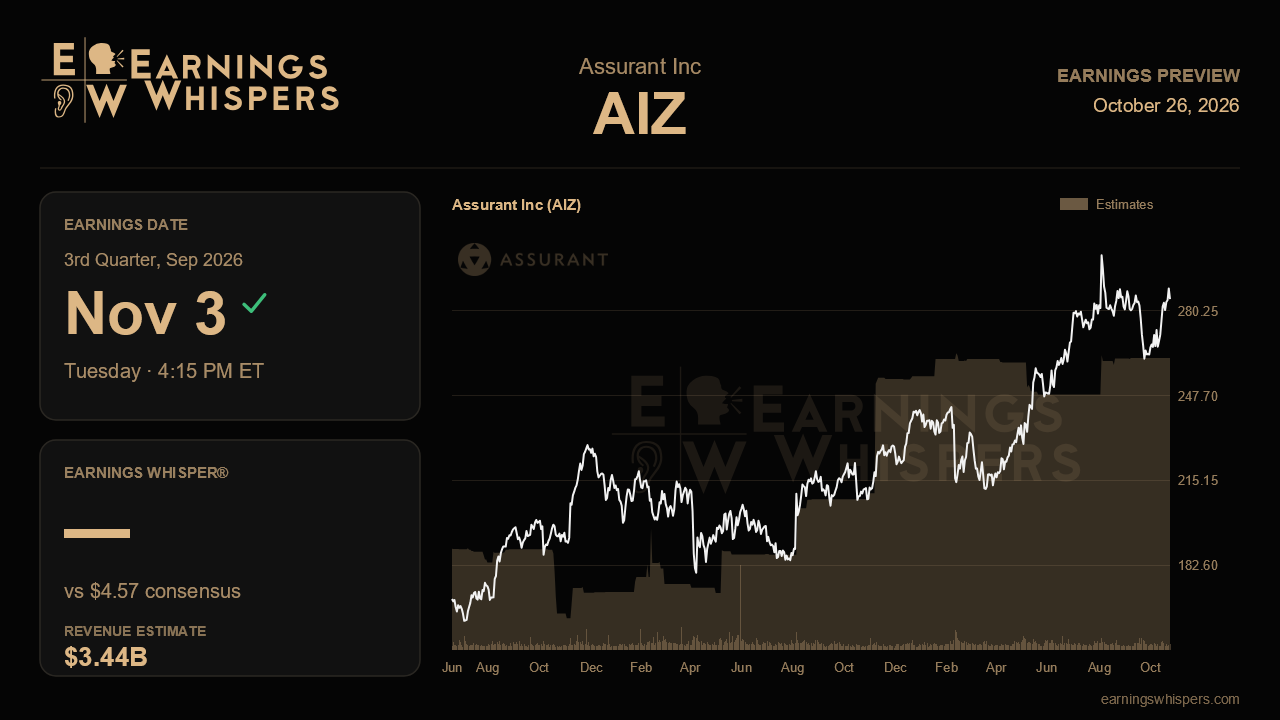
Assurant heads into its third-quarter report with an unusual split between what management has been saying and what Wall Street is modeling. Over the past three calls, the company has lifted its full-year outlook each time, and last quarter it described a second straight quarter of record earnings with momentum running across every business. Yet the consensus calls for a quarter of contraction. When results arrive after the close on November 3, the question is whether that gap reflects a sensible allowance for seasonal risk or a sign that the bullish narrative has run ahead of reality.
Analysts expect earnings of $4.57 per share, about 20% below the $5.73 posted a year ago and well under the $6.41 delivered last quarter. Revenue tells a healthier story, with the Street looking for roughly $3.44 billion, up 6.5% from a year earlier and essentially flat with the prior quarter. Top-line growth alongside a sharp drop in profit points to a heavier expected loss load rather than a weaker franchise. Management's guidance excludes catastrophe losses, and the third quarter overlaps peak storm season for a company with large lender-placed homeowners exposure. That means a headline miss or beat could hinge on weather as much as execution, so the ex-catastrophe figures deserve more attention than the reported per-share number.
On that underlying basis, the bar is high. Management raised its full-year adjusted EBITDA growth target, excluding catastrophes, to mid-single digits, or roughly 10% on an underlying basis, from low single digits a quarter earlier and flat before that. Global Lifestyle is now guided to low double-digit growth, with Connected Living up 24% and Global Auto up 15% through the first half. The housing outlook flipped from a modest decline to modest growth, helped by cheaper catastrophe reinsurance and a low non-catastrophe loss ratio near 35%. A fourth consecutive raise, or at least a firm reaffirmation, would validate that confidence. Merely holding guidance after three raises could be read as a plateau.
The specific operating evidence matters. Connected Living faces tougher comparisons in the second half, so continued double-digit growth there would show the device protection and supply chain engine is more than a easy-comp story. In housing, the Freedom Mortgage lender-placed win, covering about 2.6 million loans and ramping over twelve months, should start showing up in policy counts. The placement rate is the counterweight: it slipped to 2.02% last quarter after a client moved a higher-placement block to another servicer, and the moderating voluntary homeowners market limits upside. Stability or improvement would support management's view that the underlying rate is steady. Further erosion, combined with the shrinking cushion from favorable prior-year reserve releases, a $71 million headwind this year, would challenge the housing upgrade.
The market has not been eager to pay for the good news. Shares have slipped 3.2% since the last report, slightly worse than the S&P 500, and sentiment has turned more bearish than it was heading into the prior quarter. At about $285, the stock sits comfortably above its 200-day moving average and near the top of last quarter's range, but roughly 6% below its post-earnings high of $303.94. That leaves room in either direction without a clean breakout setup. Capital return offers support, with buybacks guided to the upper end of $300 million to $350 million.
Ultimately, the report turns on whether ex-catastrophe earnings keep tracking toward roughly 10% underlying growth while Lifestyle absorbs tougher comps and housing converts its new client win into volume. If that holds, a lower headline number driven by storms should matter little to the longer story. If underlying growth stalls just as the guidance escalator stops, the cautious mood around the stock will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-05 | |
| Sep-22 | |
| Sep-21 | |
| Aug-31 | |
| Aug-27 | |
| Aug-13 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-23 | |
| Jul-23 | |
| Jul-06 |
