AIG's Margins Face A Real Test As Growth Cools And Casualty Reserves Draw Scrutiny
American International Group heads into its third-quarter report with an awkward split personality. Revenue is expected to jump sharply, yet earnings are expected to shrink. That gap captures the question hanging over the company since its last call: can strong underwriting margins and expense discipline offset a fading growth tailwind, a deepening property soft market and the first crack in casualty reserves?
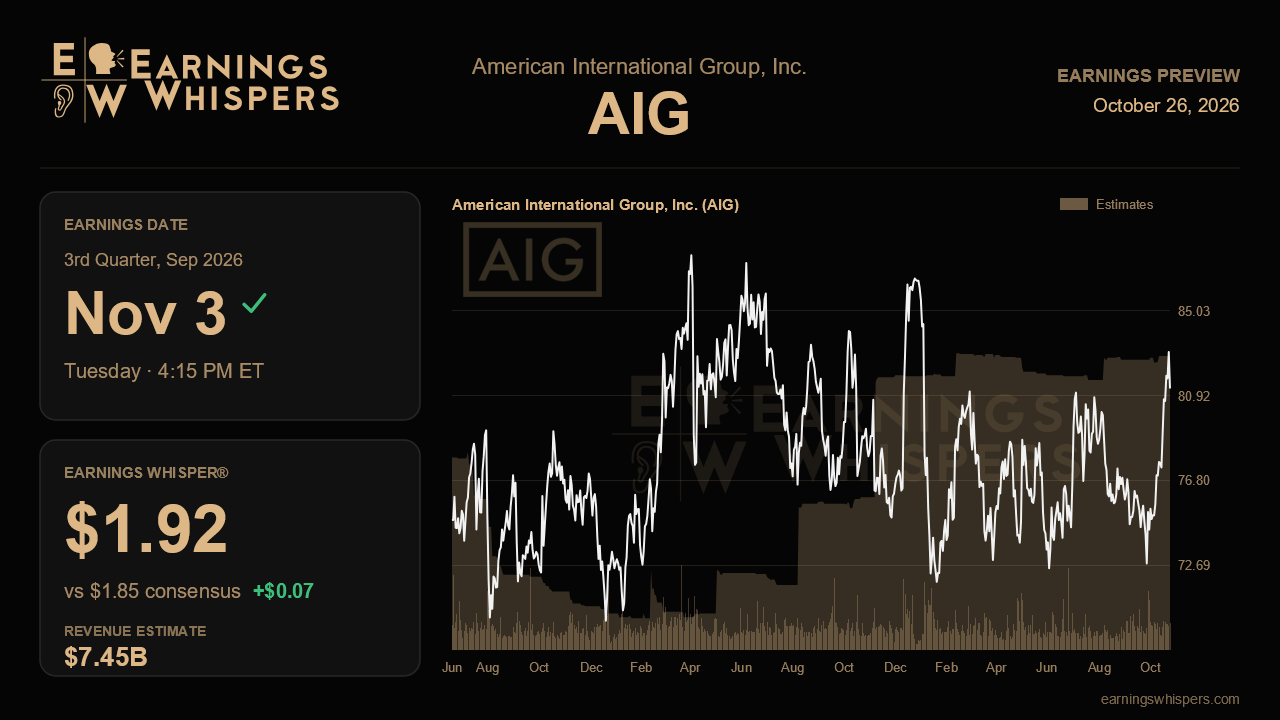
Wall Street expects earnings of $1.85 per share on revenue of about $7.45 billion when AIG reports after the close on November 3. That implies revenue growth of roughly 17% from the year-ago $6.35 billion, while earnings per share are projected to fall nearly 16% from $2.20. The estimate also sits below the $2.00 AIG earned last quarter. The Earnings Whisper of $1.92 is modestly above consensus, which suggests the more informed bar is slightly higher than the published one, though not by enough to signal a blowout is expected. AIG offered no fresh formal guidance, and notably did not reaffirm its low-to-mid teens net premiums written growth target on the second-quarter call. Management's cautious framing hinted that the low end, or something below it, is more realistic.
The top line is the first test. Net premiums written growth slowed to 9% in the second quarter from 18% in the first as the reinsurance-related boost faded, leaving organic growth in the low-to-mid single digits. Consensus revenue growth looks robust largely because of transactions and ramping arrangements such as the Convex whole-account quota share and the ongoing conversion of Everest renewal rights. The more telling number is underlying growth. If organic premium expansion holds in that low-to-mid single-digit range while Lexington continues shedding underpriced property, the narrative of disciplined cycle management stays intact. A further slide would suggest AIG is shrinking into the soft market faster than its new capabilities can replace.
Pricing is the second swing factor. North American casualty remained firm last quarter, with retail up about 10% and excess casualty up 14%, but international commercial pricing worsened to a 6% decline and global energy fell 15%. Another step down overseas would confirm that international markets are copying the U.S. property softening. Stabilization, along with continued strength in political violence lines, would ease that worry. Margin mix matters too, since a shift from property toward casualty tends to carry higher loss ratios.
The most sensitive item may be reserves. The second quarter brought $74 million of strengthening in U.S. excess casualty for accident years 2016 and 2023, the first adverse charge in recent quarters, and management conceded social inflation is not easing. Favorable releases in workers' comp and property offset it, but a repeat or expansion of casualty strengthening would challenge confidence in the quality of earlier underwriting gains. On the positive side, Global Personal posted a first-half combined ratio of 91.2%, and the expense ratio has been trending toward the sub-30% goal for 2027. Continued progress on both would cushion softer growth. Alternative investment income, which collapsed to $13 million last quarter from $137 million a year earlier, is another wildcard that helps explain the expected earnings decline.
The market has been forgiving. Shares have gained 2.7% since the last report while the S&P 500 slipped 1.4%, and sentiment has swung to mildly bullish from bearish a quarter ago. At $81.26, the stock trades comfortably above its 200-day moving average and within about 2% of its post-earnings high of $83.07, putting a breakout within reach if results reassure. That also means a stumble would meet a stock priced for steadiness.
Ultimately, this report hinges on whether AIG can prove that slower growth is a deliberate choice rather than a symptom of eroding franchise economics. Clean casualty reserves, stable margins and credible organic growth would validate the new leadership's measured approach. Additional reserve charges alongside worsening international pricing would suggest the softening tone was only the beginning.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-15 | |
| Oct-09 | |
| Oct-02 | |
| Oct-01 | |
| Sep-29 | |
| Sep-23 | |
| Sep-22 | |
| Sep-21 | |
| Sep-16 | |
| Sep-16 | |
| Sep-08 | |
| Sep-04 | |
| Sep-02 | |
| Sep-02 |
