Angi's 45% Rally Puts Margin Gains And A Narrowing Revenue Slide To The Test
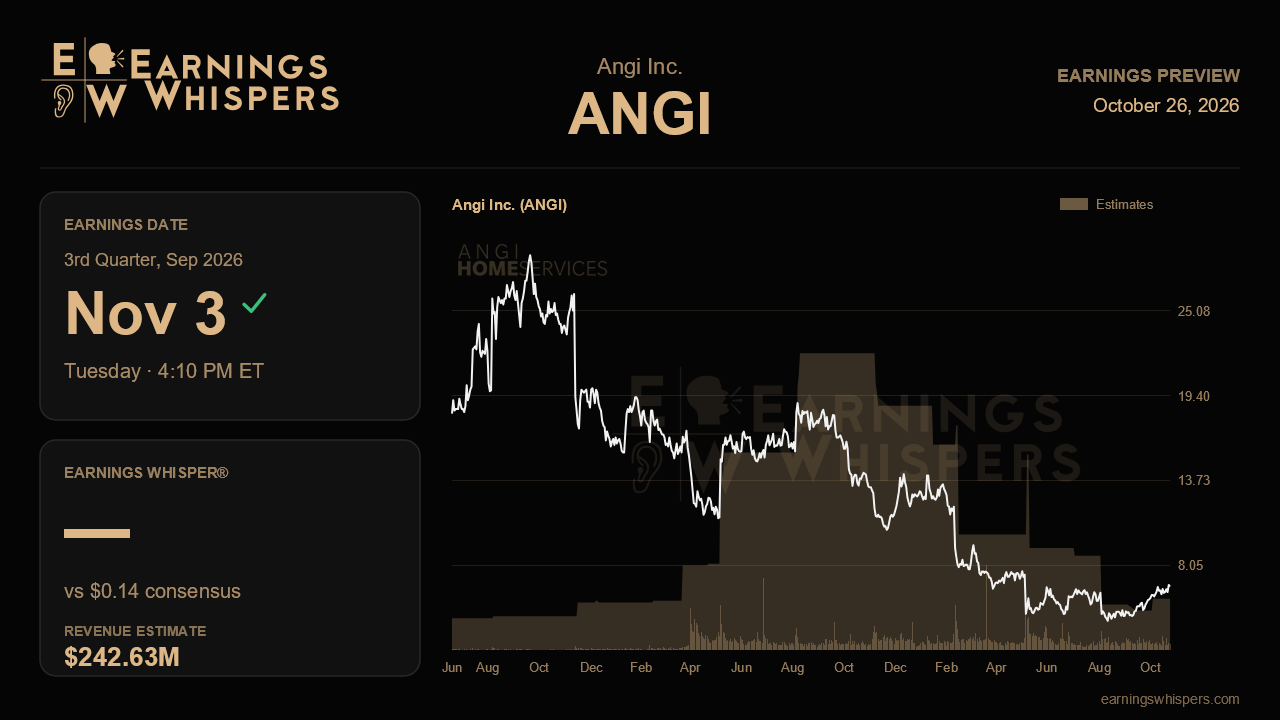
Angi heads into its third-quarter report with a stock that has behaved as if the worst is over, even though the business has not yet said so. Shares have climbed roughly 45% since the last report while the S&P 500 slipped about 2%, despite a summer call in which management deepened the revenue decline, kept guidance withdrawn and pushed any return to growth into 2027. The rally amounts to a bet that improving unit economics and AI product traction matter more than the top line. This report will show whether that bet has evidence behind it.
The Street expects earnings of $0.14 per share on revenue of $242.6 million. That would mean an 8.7% revenue decline and a 39% drop in EPS from a year ago, so this is still a contraction story. The nuance is that an 8.7% decline would be a modest improvement on the 11% drop posted last quarter, even though the revenue estimate sits slightly below the $248 million reported in the second quarter. EPS, by contrast, is expected to rise from $0.11. In other words, consensus is pricing in a business that shrinks in dollars while earning more on each one. With no reinstated guidance to anchor forecasts, the company's own commentary carries unusual weight, and investors will be listening closely for any sign of whether management is ready to put numbers back on the table.
The margin case is the most testable part of last quarter's narrative. Management said July's EBITDA margin ran about 700 basis points above the second-quarter level, helped by redirecting roughly $6 million of television spending that was not working, and that sequential revenue gains had dropped through to EBITDA at about a 50% rate. If that profitability held through August and September, the EPS estimate looks reachable. If July proves to have been a one-month bump, the earnings story gets thin quickly.
The demand side carries more uncertainty. Service requests fell 6% and leads 13% last quarter after the March energy price shock pushed homeowners away from large jobs such as roofing and HVAC, where Angi has most of its pro capacity. Encouraging signs were pro capacity recovering from down 13% in the first quarter to roughly flat by July, revenue per lead turning slightly positive, and win rates up about 20%. Confirmation would look like stabilizing lead volumes, capacity edging into growth, and the large-pro segment sustaining its better than 20% expansion as the sales team ramps toward 30 sellers. Continued deterioration in requests would challenge the idea that the macro hit was temporary, as would network revenue shrinking faster than its 34% decline.
There are also balance sheet and accounting watch points. The October annual impairment test could produce another non-cash charge on top of the $235 million taken last quarter, although the stock's rebound since then may ease that pressure. Any progress on refinancing bonds that come due within a year, which management called its top capital priority, would remove a real overhang. Updates on the AI front desk agent, the homeowner agent and the profitable ChatGPT channel will likely be framed as previews of the November 17 investor day.
Sentiment has swung from decidedly bearish before the last report to roughly neutral now, and the stock at $6.62 is testing the top of its post-earnings range near $6.78 while still sitting below its 200-day average of $6.99. That makes the setup more demanding than it was three months ago. The central question is whether Angi can show that margin expansion and stabilizing demand are durable enough to justify a rally that has already looked past a shrinking top line.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Sep-28 | |
| Sep-22 | |
| Sep-16 | |
| Sep-15 | |
| Aug-12 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| Jun-09 | |
| May-14 |
