Ceribell Heads Into Q3 With Street Forecasts Still Below Its Raised Revenue Guidance
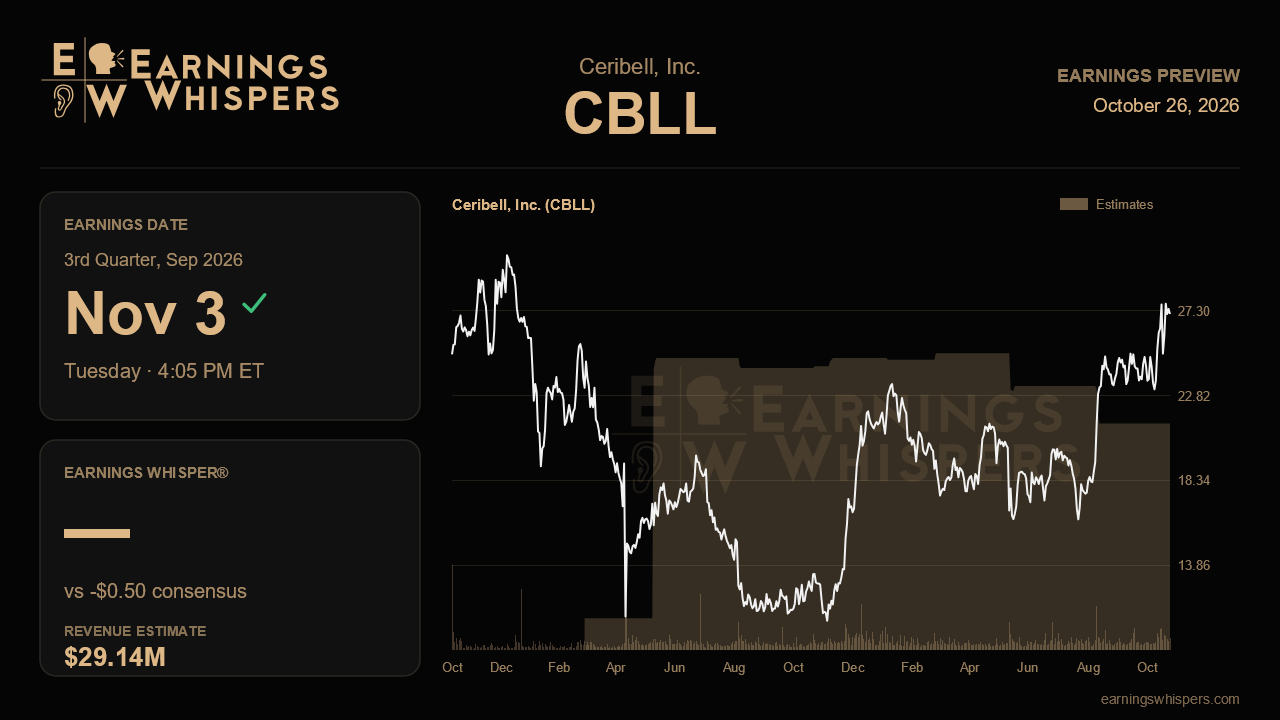
Ceribell has raised its full-year revenue outlook twice in a row. The Street still has not fully caught up. Analysts' full-year revenue estimate of roughly $113.9 million sits just under the low end of management's latest $114 million to $117 million range. That gap, combined with a stock that has rallied hard since the last report, frames the third-quarter release due after the close on November 3. The company needs to show that its reacceleration was durable rather than a one-quarter bump, and that the next leg of growth, led by delirium monitoring, is arriving on schedule.
The quarterly bar itself looks reachable. Consensus calls for revenue of about $29.1 million, up 29% from $22.6 million a year earlier and only modestly above the $28.1 million posted last quarter. That would mark a step down from the 33% growth Ceribell delivered in the second quarter. Because the Street's annual number trails guidance, a result meaningfully above $29 million would push estimates higher and could open the door to a third raise. On the bottom line, analysts expect a loss of 50 cents a share, roughly in line with last quarter's 51-cent loss but wider than the 37-cent loss a year ago. That widening is a reminder that spending is still running ahead of sales.
The most useful evidence will come from the operating details behind the top line. Last quarter's growth was driven by stronger-than-expected same-store usage despite seasonally softer ICU census, and it leaned less on VA accounts than prior periods. Continued account additions near the recent pace of 30-plus per quarter, building on the 712 active accounts reported in the second quarter, would support the case that adoption is broadening. Gross margin needs careful reading. The second quarter's record 92% figure included a $1.6 million tariff refund, and the underlying rate was closer to 89%. A third-quarter margin in the high 80s would be consistent with management's upgraded full-year target and the faster-than-planned Vietnam manufacturing ramp. A dip toward the mid-80s would raise questions about how much of the improvement was structural.
Cost discipline is the main counterweight to the bullish story. Operating expenses grew 37% last quarter, outpacing revenue, and adjusted EBITDA losses have hovered near $10 million. Management said legal costs tied to the Natus patent dispute, which were $3.9 million in the second quarter after peaking at $5.6 million in the first, should ease in the back half of the year. Visible moderation there would help the loss line and lend credibility to the company's goal of reaching breakeven on existing cash, a goal that still carries no firm timeline.
Then there are the catalysts. Final CMS approval of add-on reimbursement for delirium took effect October 1. Management pulled the commercial launch into the fourth quarter. Early commentary on hospital interest, pricing and launch execution will matter more than any revenue contribution, since delirium, neonatal and pediatric opportunities remain excluded from 2026 guidance. Updates on the newly cleared algorithms and the next-generation hardware platform will shape views of 2027.
Expectations have clearly firmed. The stock is up nearly 36% since the last report while the S&P 500 slipped about 2%. At around $27, it trades well above its 200-day average near $20.69 and within a few percent of its post-earnings high of $28.11. Sentiment remains on the bearish side but has improved sharply from where it stood before the prior report. That combination means a simple in-line quarter may not be enough. The narrative stays intact if Ceribell shows that core growth remains near 30% with high-80s margins and easing legal costs, while confirming that the delirium launch is underway as promised.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Sep-30 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-29 | |
| Jul-28 | |
| Jul-20 | |
| Jun-08 |
