Simpson Manufacturing Beats On Cost Discipline, But Fading Price, Surging Steel And A Weak Implied Q4 Cloud The Setup
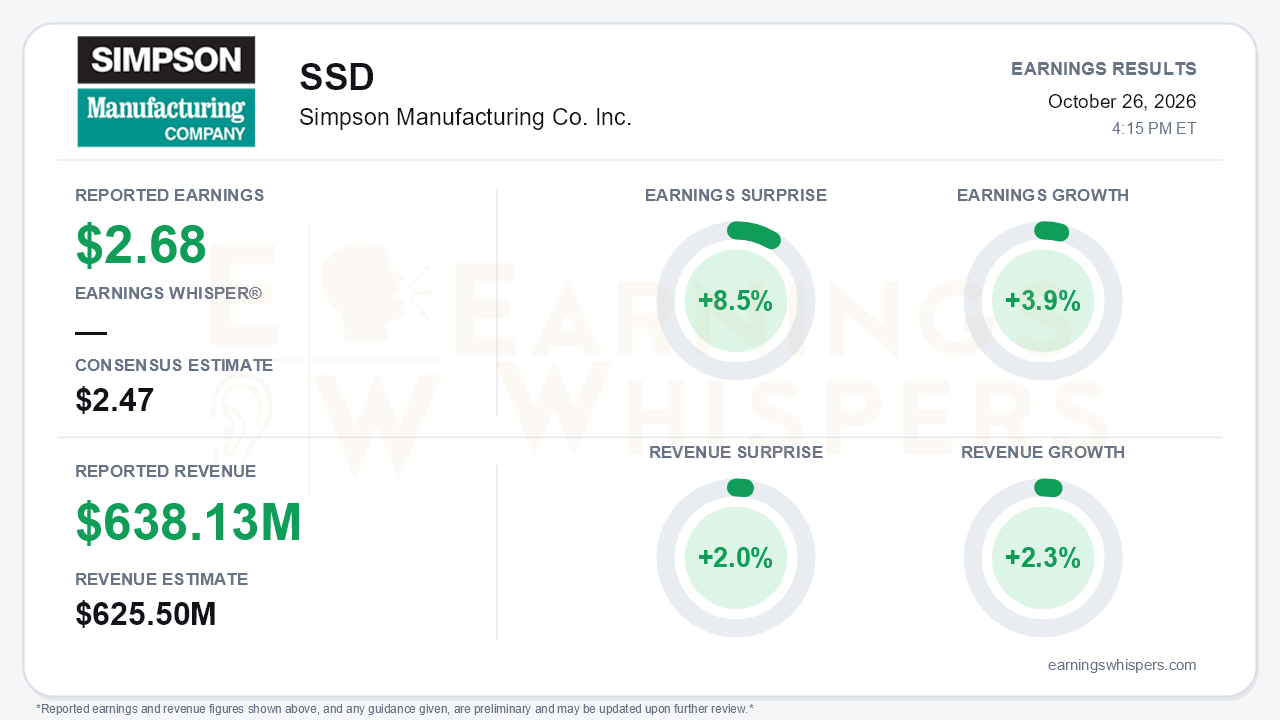
Simpson Manufacturing (NYSE: SSD) delivered a clean third-quarter beat: diluted EPS of $2.68 topped the $2.47 consensus by 8.5%, and revenue of $638.13 million came in 2.0% ahead of expectations. Beneath the beat, however, growth slowed sharply. Earnings rose just 3.9% year over year and revenue grew only 2.3%, down from 6.3% in the second quarter and 9.1% in the first. The quarter was won on cost control and capital allocation rather than demand. That is the central tension: the beat looks solid, but the forward drivers are weakening.
The quality of the beat holds up better than the flat operating line suggests. Income from operations was essentially unchanged at $141.0 million (+0.2%), but the year-ago quarter included a $14.1 million gain on asset disposals. This year's comparable gain was negligible, and the roughly $11 million Stockton land gain slipped from the third quarter into the fourth. Excluding those items, operating profit improved meaningfully. Adjusted EBITDA rose 7.4% to $167.2 million. The improvement came from expenses, not gross profit. Operating expenses fell 6.3% to $150.5 million, with SG&A headcount down about 6%. Gross margin slipped 40 basis points to 45.7%, a sharp reversal from Q2's 47.4%, which had been up 100 basis points year over year. Higher interest income and a share count about 2.3% lower also added to per-share growth.
The segment detail shows a clear split. North America sales grew 3.8%, and operating margin expanded to 27.3% from 25.9% on lower personnel, professional-fee and bad-debt costs. Volume outperformed single-family starts by roughly 400 basis points on a trailing basis. Several end markets improved from Q2:
- Residential volumes returned to low-single-digit growth.
- Commercial swung to high-single-digit growth on data center and cold-formed steel wins.
- OEM grew double digits.
Europe moved the other way. Sales fell 3.4% on a 5% volume decline, and gross margin dropped to 36.1% from 37.9%. Operating margin fell to 11.8% from a record 13.7% in Q2. Management cut its 2026 European market outlook to flat-to-slightly-down, citing political and fiscal uncertainty in France.
The forward picture is where bears have legitimate ammunition:
- **Pricing fade:** the price contribution fell to about 2.5% from 5-6% and is expected to drop below 1% in the fourth quarter.
- **Steel costs:** steel is up more than 50% year over year at a four-year high, and availability is tightening.
- **Volume:** consolidated volume was flat and is guided down slightly for the rest of the year.
- **Housing:** management flagged risk that the decline in U.S. starts could widen toward mid single digits, and it is planning for a flattish or worse 2027.
- **Other weak spots:** national retail fell mid single digits, component manufacturer growth should moderate during a software transition, and Gallatin fastener supply problems persist.
Full-year operating margin guidance was narrowed to 20.0%-20.5% from 19.7%-20.5%, which reads as a raise. Yet the range implies a fourth-quarter operating margin of only about 13%-14%, even including the land gain. New price increases announced for early January will arrive with a lag behind steel costs.
Management answered with capital. The board approved a $1.0 billion repurchase authorization with no expiration, replacing a $200 million program, and buybacks could rise above 50% of free cash flow. The balance sheet supports it: net cash reached $183.3 million versus $113.8 million in Q2 and $9.9 million at year-end 2025. On the product side, the next-generation cloud truss software launched at BCMC drew strong customer interest and is a longer-dated catalyst.
Investors were already braced for trouble. Earnings Whispers sentiment fell from roughly neutral (-0.06) to clearly negative (-0.35), a meaningful deterioration. Shares sat at $184.36, down 6.9% since the open after the July report. That is about 12% below the July 28 inter-earnings high of $209.32 and 9.3% above the October 1 low. The stock entered the print almost exactly on its 200-day moving average of $185.14, a sign the market lacked conviction in either direction. The company bought back stock during the quarter at an average of $188.25, close to current levels. The trend readings are mixed: price trend is negative while AVWAP is positive.
The bottom line is that Simpson beat by executing well on costs, not by growing. Expense discipline, North American margin gains and an aggressive new buyback offset a business losing its pricing tailwind just as steel costs spike and Europe softens. With sentiment already sour and the stock near its 200-day average, the beat may ease near-term fears. The investment case now depends on whether January pricing can catch up with steel before the fourth-quarter margin trough becomes the 2027 baseline.
Read our earnings preview for Simpson Manufacturing Co. Inc.: https://www.earningswhispers.com/article/SSD/20668
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| Oct-23 | |
| Oct-12 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-24 | |
| Jul-13 | |
| Jun-15 | |
| Jun-03 | |
| May-07 | |
| Apr-27 |
