Rambus Beats And Raises As Product Revenue Accelerates, But Royalty Erosion And Margin Pressure Complicate A Battered Stock
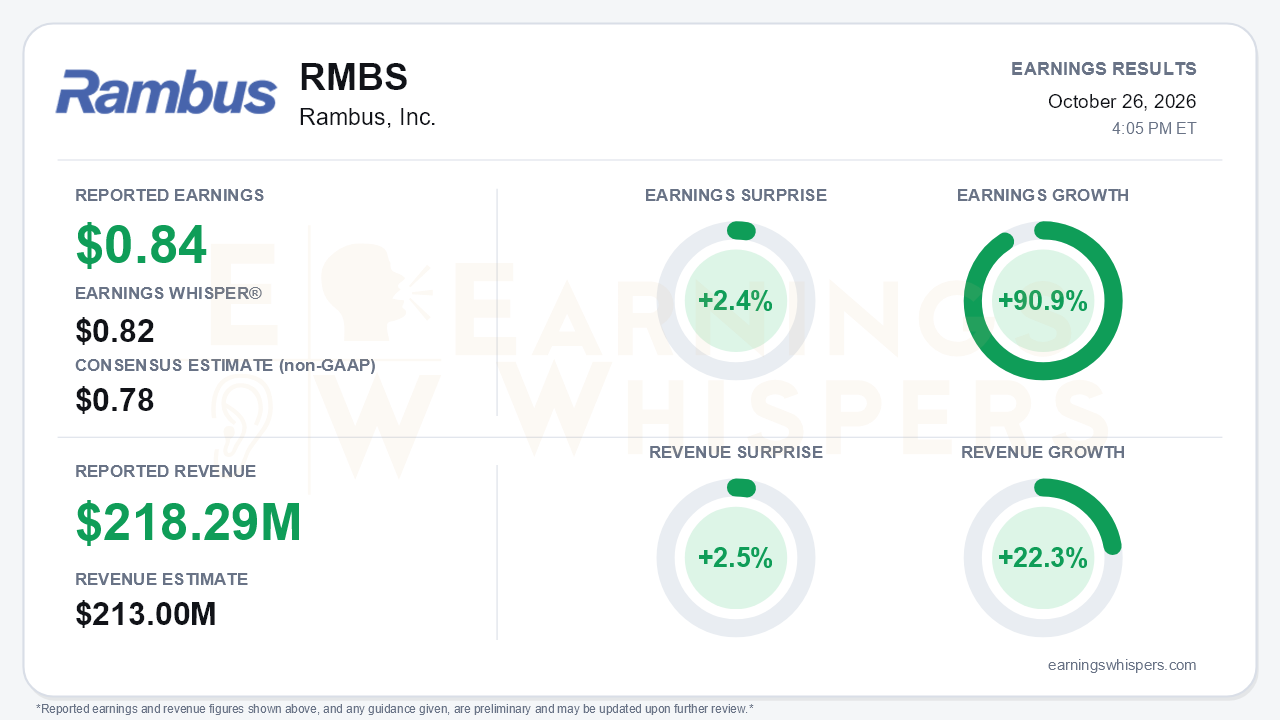
Rambus delivered its second consecutive beat-and-raise quarter. Non-GAAP earnings of $0.84 per share topped the $0.78 consensus and the $0.82 Earnings Whisper number, a 2.4% surprise. Revenue rose 22.3% year over year to a record $218.29 million, beating the $213.0 million consensus by 2.5% and clearing the top of management's $210 million to $216 million guidance range. Earnings Whispers' normalized data shows earnings growth of 90.9%. The company's own comparisons are more modest: non-GAAP EPS rose to $0.84 from $0.62, and GAAP EPS rose to $0.69 from $0.44. On either basis, profits grew well faster than revenue. The more important development is the shape of the outlook. Fourth-quarter guidance calls for product revenue to accelerate sharply while royalties keep shrinking. That mix shift is the central tension in the Rambus story.
The quality of the beat is solid. Product revenue reached a record $114.3 million, up 15% sequentially and 22% year over year. That extends a clean progression from roughly $88 million in Q1 and $99.2 million in Q2. Contract and other revenue jumped 35% to $27.0 million. Non-GAAP operating margin widened to 47% from 44%. Operating cash flow hit a record $102.5 million, up from $61 million in Q2 and $83 million in Q1. Royalties were the soft spot. They rose year over year to $77.0 million but fell from $84.2 million in Q2. Fourth-quarter royalty guidance of $68 million to $74 million implies further erosion.
The call marked a clear shift in management's tone. In Q2, executives spoke of 'confidence building' and took a quarter-by-quarter approach. This quarter, they described demand as strengthening into 2027 and said customers are placing orders earlier, which improves backlog visibility. Fourth-quarter product guidance of $127 million to $133 million implies roughly 34% growth at the midpoint, a meaningful acceleration from the low-20s pace of the past two quarters. Silicon IP is now tracking toward the high end of its 10% to 15% growth range, helped by new tier-one design wins for next-generation HBM IP. Companion chips continue to grow sequentially. Total Q4 guidance of $227 million to $233 million in revenue and $0.84 to $0.92 in non-GAAP EPS came in above estimates.
The pipeline of catalysts is deep:
- broad sampling of Gen6 DDR5-9600 RCDs;
- an LPDDR6 SOCAMM2 PMIC with higher content than first-generation parts, though management pegs that market around 2028;
- Caliptra-compliant root-of-trust IP;
- a strategic investment in agentic-AI design firm ChipAgents.
Bears still have legitimate ammunition. Product gross margin slipped to about 60.4%, the low end of the 60% to 63% band, because of supply-chain input cost inflation. Lengthening supplier lead times are expected to keep supply tight into 2027. As lower-margin product revenue displaces royalties, margin leverage gets harder to sustain. Management also characterized the MRDIMM ramp as shallower than prior RCD ramps, acknowledged that a competitor won the first-generation MRDIMM platform, and flagged memory despecking as a headwind. Inventory roughly doubled to $87.2 million from $44.1 million at year-end. That is consistent with preparing for a Q4 ramp, but it bears watching. Cash fell $48 million to $776.9 million after $135.4 million of buybacks, including a completed $100 million accelerated repurchase under a new framework of returning 40% to 50% of free cash flow.
The market had not been rewarding the fundamentals heading into the print. Shares closed at $85.65 on October 23, down 6.0% from the open after the July report. That price is 20.7% below the $108.00 200-day moving average. The stock peaked at $113.28 on October 2 and now sits 24.4% below that high, just 7.1% above the September 14 low of $80.00. That steep give-back, after the peak came weeks after the prior report, suggests investors were already discounting margin and royalty concerns. Investor sentiment entered the report negative and drifted slightly lower, from -0.281 to -0.310, a modest deterioration rather than capitulation. The Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price and AVWAP remain negative.
The bottom line is that Rambus produced a quarter that looks stronger than the 2.4% surprise implies. Product momentum is accelerating, the guide is above estimates, cash generation hit a record, and management's tone has turned more confident. The investment debate now centers on mix and margins rather than demand. Royalties are fading, product gross margin is pinned at the low end of its range, and MRDIMM expectations have been tempered. With shares well below the 200-day average and sentiment still negative, Q4 must deliver both the product acceleration and stable margins for the narrative to win back a skeptical market.
Read our earnings preview for Rambus, Inc.: https://www.earningswhispers.com/article/RMBS/20667
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Oct-13 | |
| Oct-05 | |
| Sep-16 | |
| Aug-06 | |
| Aug-05 | |
| Jul-28 |
