Clearwater Paper Narrows Its Loss As Price Hikes Stick, But Augusta Failures And A Weaker Q4 Guide Cloud The Recovery
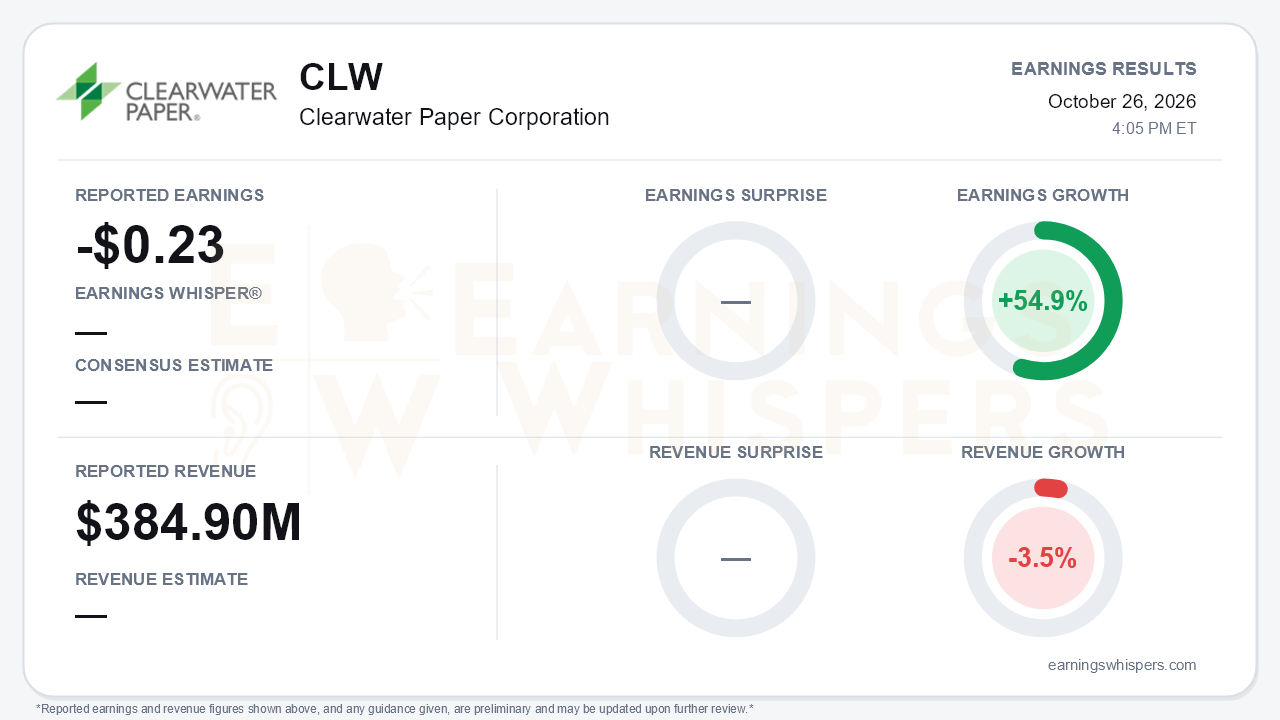
Clearwater Paper (NYSE: CLW) reported an adjusted third-quarter loss of $0.23 per share on revenue of $384.9 million. That loss is 54.9% narrower than the $0.51 adjusted loss a year earlier, while revenue fell 3.5% year over year. There was no consensus figure to measure against, so the story rests on trajectory rather than a beat or miss. The trajectory is real. Adjusted EBITDA from continuing operations reached $24 million, inside the $20-30 million range management set on the second-quarter call. That compares with negative $8 million in Q2 and $2 million in Q1. Pricing is finally reaching the income statement, and the balance sheet has been de-risked. The central tension is that Augusta's operating failures, rising cost headwinds and a Q4 EBITDA guide of $10-20 million show the recovery will not be a straight line.
The quality of the quarter deserves scrutiny. On a GAAP basis, the loss from continuing operations was $0.10 per share, compared with a $3.34 loss a year ago that included a $48 million goodwill impairment. The year-over-year EBITDA gain also owes a lot to timing. The Lewiston major maintenance outage fell in Q3 2025 but in Q2 2026, which flatters the comparison against weaker pricing. Paperboard net selling price was $1,111 per ton, still down 4% from a year ago, though up $34 per ton sequentially, worth about $8 million. More importantly, CEO Arsen Kitch said the Augusta disruption late in the quarter was largely offset by a portion of the representation and warranty insurance (RWI) settlements, including the $17.5 million received in Q3. Those recoveries are now exhausted at $73 million of a $105 million policy, with further recourse uncertain. A cushion that helped this quarter will not repeat.
The call kept a credible pricing story intact.
- **First increase:** The first $60-per-ton increase is fully implemented. Management now values it at more than $70 million annualized, up from $50-60 million on the Q2 call, with roughly $50-55 million carrying into 2027.
- **Second increase:** A second $60-per-ton increase is being implemented and could add $30-40 million in 2027 if recognized by the RISI price index.
- **Further upside:** Management said RISI's forecast for another $100 per ton by end-2027 would imply about $200 million of EBITDA run-rate uplift if fully realized.
- **Industry supply:** Capacity cuts have grown to about 800,000 tons annualized, up from roughly 300,000 cited in Q2. SBS shipments are up 6%, and operating rates are expected above 90% by year-end.
On the cost side, SG&A fell to 5.2% of sales, comfortably below the 6-7% target. The product pipeline also advanced. A CUK solution at Cypress Bend moves to launch by year-end for only about $3-5 million of capex, versus a $60 million framing in Q1. Circa CRB is in customer trials.
Bears have legitimate ammunition, however.
- **Augusta reliability:** The mill suffered electrical and mechanical failures that carried into October and has run 10-15% below capacity.
- **Maintenance costs:** The January 2027 outage now costs $12-15 million, up from $10-11 million. A second 2027 outage adds $7-10 million, and total 2027 maintenance expense is about $50 million.
- **Capex deferral:** The FY26 capex cut to $55-60 million, from $65-75 million, is largely a deferral, so 2027 capex will rise.
- **Conflict costs:** Middle East conflict costs were raised to $28-32 million for the year, from $20-25 million, and are now expected to persist into 2027 rather than ease in Q4.
- **Imports:** European imports have proven resilient, down only 1% year to date versus the 11% decline cited in Q2.
- **Other headwinds:** The CFO is departing. Interest expense will rise to about $25 million a year at an 8.25% effective rate after the refinancing.
That refinancing remains the quarter's cleanest win. A $275 million Farm Credit term loan and a $200 million revolver push maturities to 2031, closing an item that had hung over the story since late 2025. Net debt has fallen $56 million year to date to $260.7 million. Full-year free cash flow is now expected to be positive, versus a break-even target in Q1, aided by tax refunds, insurance and working-capital reductions.
Investor expectations shifted meaningfully into the report. Earnings Whispers sentiment moved from -0.32 after the July release to +0.09, a swing from clearly negative to modestly positive. The stock tells a more restrained story. At $19.29, shares were up just 2.0% from the open after the prior report. They sat 12.1% above the 200-day moving average but 18.2% below the 52-week high of $23.59 set on August 7, and only 7% above the October 15 low. Much of the early-quarter enthusiasm had already been surrendered. Sequential growth trends read negative, which fits a Q4 guide that steps down from Q3.
The bottom line is that Clearwater delivered the pricing inflection and the balance-sheet fix investors were waiting for. The narrower loss is a genuine improvement, not merely an easy comparison. Even so, the quarter leaned on non-recurring insurance offsets and favorable outage timing. Meanwhile, Augusta's reliability, higher 2027 maintenance and capex, persistent conflict costs and a softer Q4 push the earnings payoff further out. The thesis now depends on whether the second price increase and RISI's forecast hikes arrive fast enough to outrun those costs.
Read our earnings preview for Clearwater Paper Corporation: https://www.earningswhispers.com/article/CLW/20648
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-12 | |
| Sep-22 | |
| Sep-21 | |
| Sep-08 | |
| Aug-11 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-24 | |
| Jul-23 |
