Coupang's Revenue Rebound Faces A Margin Test As Fire And Fines Cloud The Quarter
Coupang heads into its third-quarter report with a split personality. Last quarter, the customer side of the business finally looked like it had healed from the data incident, with membership back above pre-crisis levels and constant-currency growth re-accelerating. The profit side has not followed. Margins remain deeply compressed, free cash flow has nearly evaporated on a trailing basis, and a July fulfillment center fire added a new unknown. The stock has been priced as though the bad news matters more than the good, and Tuesday's report after the close will test whether that judgment is too harsh.
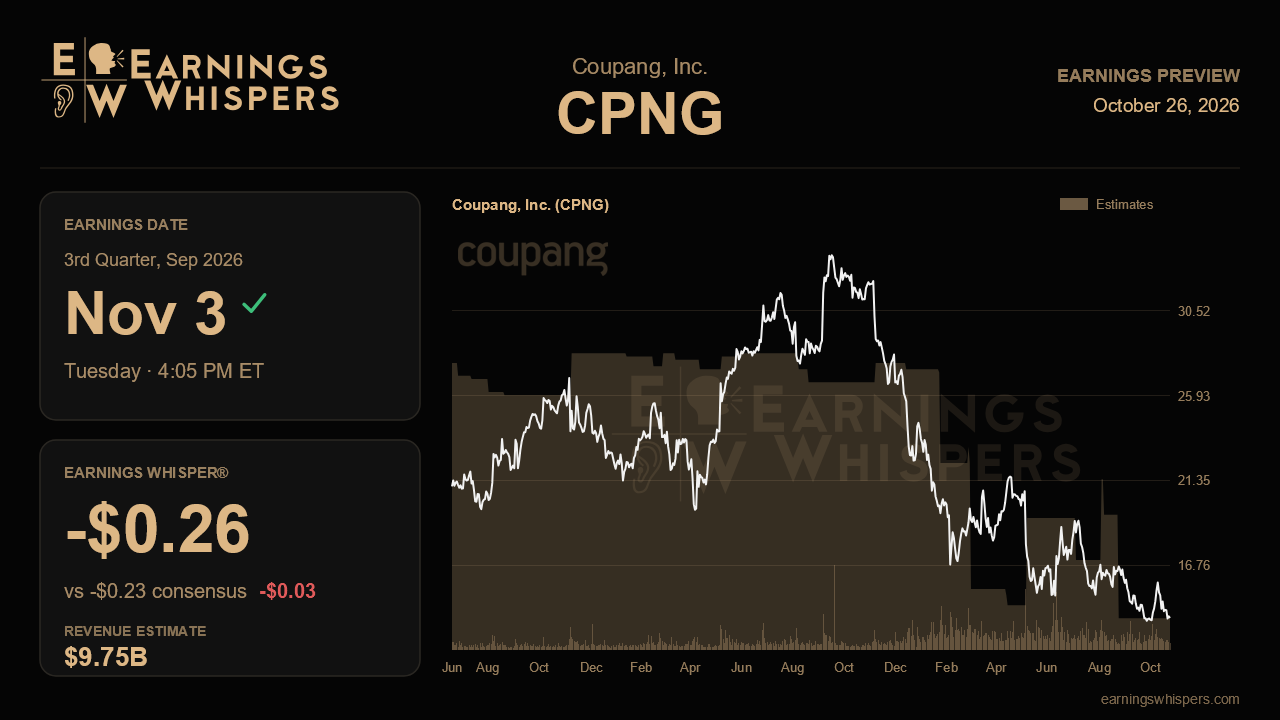
The Street is looking for a loss of $0.23 per share on revenue of about $9.75 billion. That revenue figure implies growth of roughly 5% from the year-ago $9.27 billion, which is modest and a notch below what management guided on a constant-currency basis. The gap is mostly currency. The Korean won sits near its weakest level in more than 15 years, so reported dollar growth will understate local momentum. Management pointed to product commerce constant-currency growth easing to roughly 6% to 7%, down from 8% last quarter, and attributed the slowdown to the Chuseok holiday shifting on the calendar rather than to softer demand. The earnings picture is starker. A year ago Coupang earned $0.05 a share, and the consensus now calls for a loss wider than last quarter's $0.09. The whisper number of a $0.26 loss is slightly below consensus. That gap is small, but it suggests the market is bracing for a bit more damage rather than hoping for upside, possibly from fire-related charges whose size management had not yet determined.
The core question is whether last quarter's recovery story holds up once the holiday distortion is stripped out. Management said customers outside the cohort that left during the incident are increasing their spending about 16% year over year, close to pre-incident rates. It also described record WOW membership as a leading indicator that shows up in revenue with a lag. Continued growth in active customers from the 24.7 million reported last quarter, along with commentary that membership gains are converting into order volume, would support that thesis. A stall in active customers, or constant-currency growth below the 6% to 7% range, would suggest the rebound depended more heavily on promotions than management let on.
Margins are the other half of the test. Management guided to a further 300 to 400 basis points of year-over-year EBITDA margin contraction this quarter and does not expect product commerce margins to return to pre-incident levels until mid-2027. Coming in at the better end of that range would show that marketing spend to win customers back is starting to taper. Gross margin offers a related signal, since it improved slightly from the first quarter to the second. Developing offerings also matter. After that segment's loss narrowed by $110 million sequentially, any slippage against the $950 million to $1 billion full-year loss guide would undercut one of last quarter's brighter spots.
Sentiment has improved, though it remains negative, with bearish readings roughly half as intense as before the last report. The stock has not shared that optimism. Shares are down nearly 15% since the last report, about 13 points worse than the S&P 500, and at $13.90 they trade well below the 200-day moving average of $17.49. The price sits only a few percent above the post-earnings low of $13.35, and the entire trading range has shifted down from the prior quarter's.
That sets up an asymmetric test. Revenue alone is unlikely to move the stock much, because the holiday-driven slowdown is already flagged. What matters is evidence that margins have stopped deteriorating faster than guided, together with a clear accounting of the fire's cost and some stabilization in cash flow. If Coupang can show that its revived customer engagement is beginning to translate into operating leverage, the recovery narrative stays intact. If it cannot, the market will likely keep treating mid-2027 as a promise rather than a plan.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-20 | |
| Oct-05 | |
| Sep-22 | |
| Sep-21 | |
| Aug-18 | |
| Aug-18 | |
| Aug-12 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-30 |
