Everus Heads Into Q3 Needing Backlog Conversion To Answer A 35% Post-Guidance Slide
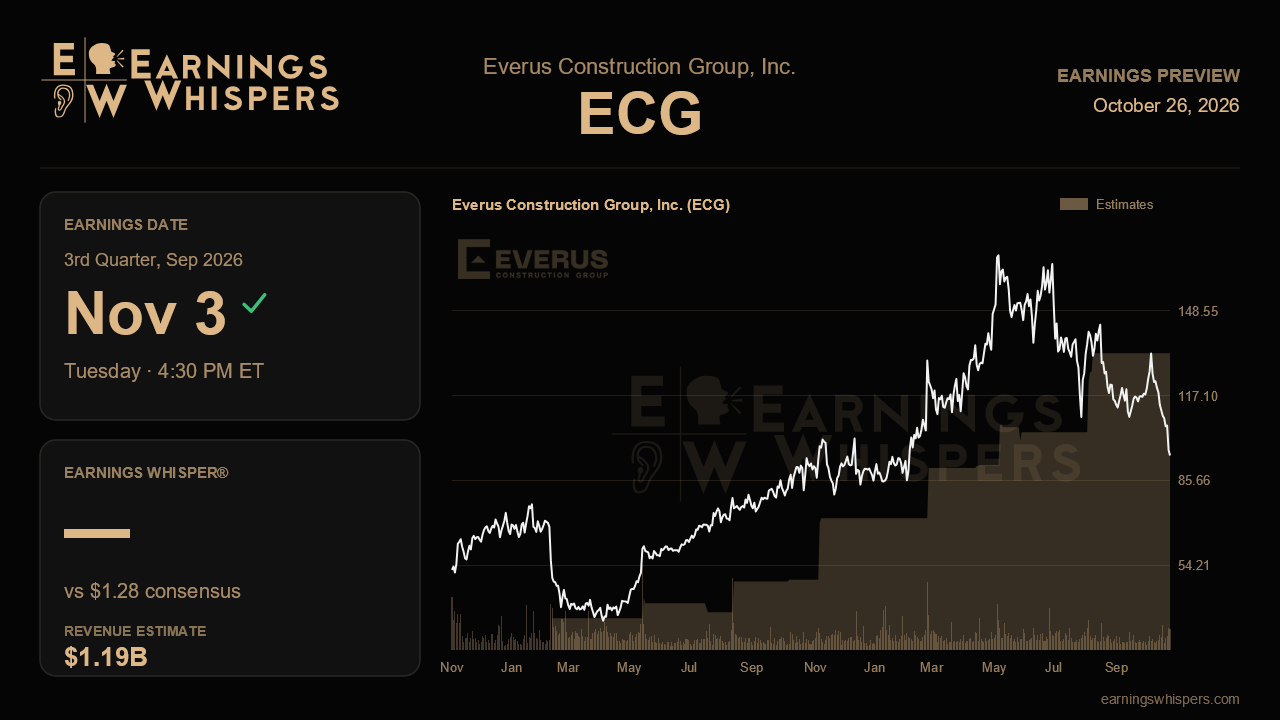
Few contractors have given the market more good news in a shorter span than Everus Construction Group, and few have been treated worse for it. Since its last report, when management raised full-year guidance for the second straight quarter, posted record revenue and unveiled a second acquisition, the stock has fallen 35.5% while the S&P 500 slipped only about 2%. That disconnect frames the third-quarter release due after the close on November 3. The business narrative is about as strong as it gets. The market appears to be pricing in either an approaching peak or a risk it believes management is underplaying.
The Street is looking for earnings of $1.28 per share on revenue of $1.19 billion, up 15.3% and 20.6% from a year ago. That is still strong growth, but both figures sit below the second quarter's $1.64 and $1.23 billion. Management has effectively told investors to expect that. It lifted 2026 revenue guidance to $4.5 billion to $4.7 billion, up from $4.3 billion to $4.4 billion a quarter earlier and $4.1 billion to $4.2 billion at the start of the year. It also raised EBITDA guidance to $410 million to $425 million. With roughly $2.27 billion booked in the first half, the range implies about $1.12 billion to $1.22 billion per quarter in the back half, so the quarterly revenue estimate sits comfortably inside it. The full-year consensus of $4.38 billion, however, still sits below the bottom of the new range. That suggests some forecasts have not fully caught up, or that a portion of the Street doubts the raise.
Margins are the likely swing factor. Management assumed a back-half EBITDA margin of about 8.5%, raised from roughly 8%, against the 10.4% delivered in the second quarter. That gap builds a meaningful cushion into guidance. A result that holds anywhere near the high 9% range would suggest the electrical and mechanical segment's 190 basis points of margin expansion reflects better pricing and execution rather than a favorable project mix. Landing right at 8.5% would simply match the plan. Falling below it would undercut the logic behind two consecutive raises.
Backlog will be scrutinized just as closely. It reached $4.55 billion last quarter, up 53% from a year earlier and accelerating from 20% growth in the first quarter. Management stressed that most of the sequential gain did not come from data centers, which remain the company's largest single concentration. Continued backlog growth that holds up across commercial, industrial and semiconductor work would ease that concentration worry. Investors should also look for progress on the semiconductor project in a new geography, which management said was ramping as planned. A flat or shrinking backlog, or a renewed tilt toward data centers, would feed the bearish case. Cash flow deserves attention as well. First-half free cash flow of $167 million benefited from working-capital timing that management expects to reverse, so a softer third quarter on that line would not be alarming by itself.
On deals, the SC&M integration should be well established by now. Any update on the closing timeline for Epsilon Industries, the off-site modular builder that is not yet in guidance, would matter because it expands Everus into Florida, Texas, the Mid-Atlantic and the Northeast. Net leverage of 0.3x leaves room for more acquisitions. Management's decision to keep its long-term targets of 5% to 7% organic growth and 7% to 9% EBITDA growth, despite calling them conservative, hints that it views the current boom as cyclical. Sentiment has shifted from modestly bullish to 16.4% bearish, and the stock trades near its post-report low of $91.39, well beneath its 200-day average of about $125.
The central question is whether Everus can show that its record backlog is turning into durable, broad-based earnings power rather than a data center windfall. If margins hold above the guided pace and backlog keeps broadening, the selloff will look like overreach. If either cracks, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Sep-16 | |
| Sep-02 | |
| Sep-01 | |
| Aug-05 | |
| Aug-04 | |
| Jul-31 | |
| Jul-22 | |
| Jun-18 |
IPO Stock Of The Week: AI Data Center Leader Everus Construction Eyes Latest Buy Point
ECG
Investor's Business Daily
|
| Jun-01 | |
| May-19 | |
| May-05 | |
| Apr-22 | |
| Apr-07 |
