Summit Hotel Properties Must Show Its Rate-Driven Rebound Outlasts The World Cup Boost
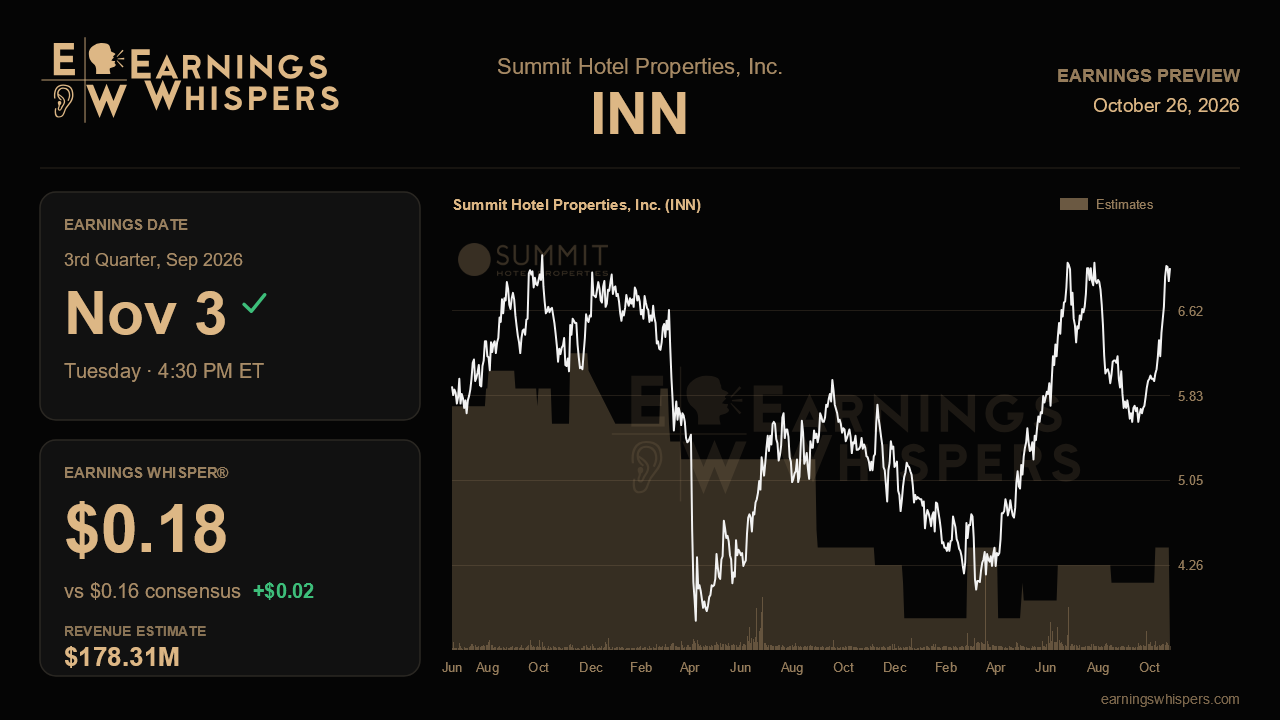
Summit Hotel Properties heads into its third-quarter report with a story that has improved four quarters in a row, and the November 3 release will test how much of that progress is durable. Management raised every major piece of its 2026 outlook last quarter, pointed to roughly 6% RevPAR growth in July and said the quarter was pacing up in the mid-single digits. It also conceded that part of the recent strength came from one-time World Cup demand. The question now is whether the momentum holds once that event-driven lift fades.
Wall Street's bar is modest. Consensus calls for earnings of $0.16 per share, about 5.9% below the $0.17 posted a year ago, on revenue of $178.3 million, essentially flat at 0.7% growth. The Earnings Whisper of $0.18 sits a couple of cents above consensus, suggesting more confident observers expect a small beat rather than a stumble. The flat revenue forecast also stands out against management's mid-single-digit pacing commentary. Some of that gap likely reflects the hotels Summit has sold, including the Arlington pair it disposed of for $19 million, which shrinks the reported revenue base even as the remaining portfolio performs better.
The guidance comparison is where the setup gets interesting. Management narrowed its 2026 adjusted FFO range to $0.79 to $0.85 per share by lifting the bottom end from $0.75, yet the full-year consensus FFO estimate sits at $0.75. That leaves analysts below the company's entire range. Either the Street doubts the second-half ramp management described, or estimates have not caught up with the improved outlook. A solid third quarter that keeps the company on track for its range would put pressure on analysts to move higher.
Several details from last quarter's call will show whether the improvement is real. The first is the mix of demand. Government business swung to an 8% gain in the second quarter after falling as much as 25% through 2025, and business transient travel, including AI-related tech demand, was helping push rates higher. Continued strength in those segments, along with the planned shift away from lower-margin online travel bookings, would support the case that growth is driven by pricing rather than one-off events. September should be the clearest evidence. Management called it the strongest month of the quarter, and it falls outside the World Cup window. Margins are the second test. Second-quarter hotel EBITDA flow-through of 54% helped management upgrade its full-year margin view to roughly flat, despite a persistent property-tax drag of about 25 basis points. Holding that trend would confirm that higher rates are reaching the bottom line. Updates on dispositions also matter, since management described a thawing transaction market that could support more asset sales at attractive pricing.
Sentiment has cooled noticeably despite the better fundamentals. The bullish reading has fallen to about 0.20 from roughly 0.54 ahead of the last report. The stock is essentially unchanged since then, though it has edged out a declining S&P 500 by about a percentage point. At $6.90, shares trade well above the 200-day moving average of $5.52 and in the upper part of the post-earnings range, a bit under 4% below the $7.17 high. That positioning suggests investors already credit much of the recovery without fully embracing it.
Ultimately, the report comes down to whether Summit's rate-led recovery stands on its own. Strong September results, steady segment trends and a reaffirmed or raised FFO range would validate management's more confident tone and make the Street's below-range estimates look stale. Softness once the World Cup boost passes would suggest last quarter's optimism leaned too heavily on a single event.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Sep-23 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 | |
| Jul-01 | |
| Jun-30 | |
| Jun-12 | |
| Apr-30 | |
| Apr-30 | |
| Apr-23 | |
| Mar-25 | |
| Mar-06 | |
| Feb-28 |
