Modine's Margin Repair Faces Its First Test As Stock Sits Near Post-Earnings Lows
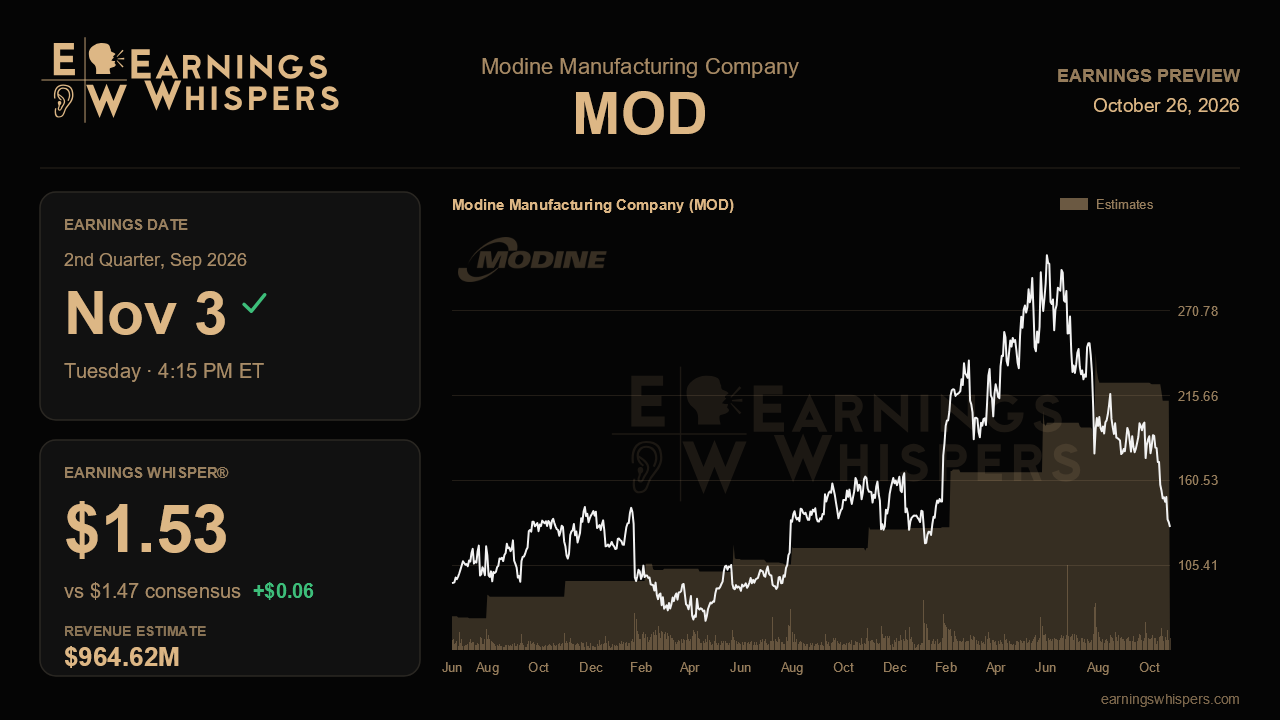
Modine heads into its fiscal second-quarter report with a split personality. Demand for its data center cooling equipment has never looked stronger, yet the stock has lost roughly a third of its value since the last report, trailing the S&P 500 by more than 36 percentage points. The reason is margins. Component shortages pushed data center profitability well below where management said it should be, and this release is the first real chance to show that the damage was a passing problem rather than a lasting one.
The Street expects earnings of $1.47 a share on revenue of about $964.6 million, which would mean growth of roughly 39% and 31%, respectively, from a year ago. That is a strong growth quarter by any measure, and it also implies about 10% sequential revenue growth from the $874.1 million reported last time. The Earnings Whisper sits at $1.53, modestly above consensus, suggesting some investors expect an upside surprise despite the selloff. It is worth remembering that last quarter's $1.53 was helped by a tax benefit, so matching that figure on cleaner operating results would say more than the headline number alone. For the full fiscal year, management reaffirmed revenue of $3.83 billion to $4.29 billion, along with adjusted EBITDA of $650 million to $680 million. Consensus of $4.04 billion sits comfortably inside that range, just a hair under the midpoint, so analysts are not asking for heroics.
The heart of the story is data center margin. Adjusted EBITDA margin in that segment fell to 14.8% last quarter from a run rate near 19% to 20%, with excess labor, plant downtime and poor overhead absorption accounting for most of the hit. Management insisted the problem was timing, not structure, and said margins had already recovered to normal levels by June. If that claim holds, the September quarter should show a clear step back toward the high teens, putting the promised return above 20% in the second half within reach. A margin that merely inches higher would make the reaffirmed EBITDA guide look stretched, since hitting it now requires a steep back-half improvement. Total company gross margin, which slid 340 basis points to 20.8%, is the broader gauge of whether the recovery is real across all three segments.
Revenue mix matters too. Data center sales slipped sequentially last quarter because of a customer program delay on a modular product and missed end-of-quarter shipments. A rebound would show those delays were truly deferred rather than lost. Backlog more than doubled on a third straight record for order intake, and the first purchase orders arrived under the $4 billion hyperscaler capacity agreement. Additional orders against that deal, progress on supplier long-term agreements and any update on bringing a critical component in-house would support the view that Modine is fixing its supply chain ahead of the 2027 ramp. Commercial HVAC, where margins fell on acquisition mix and footprint consolidation, needs to show the new leadership's restructuring is gaining traction.
Sentiment has soured noticeably, with bearish readings roughly doubling since the prior quarter, and the stock trades within about 1% of its post-earnings low of $128.86, far below last quarter's high above $318. That backdrop lowers the bar in one sense, but it also signals limited patience for another execution stumble. Cash flow deserves attention as well after a slightly negative first quarter and higher net debt, as does the interim leadership arrangement in data centers and the pending spinoff of the performance technologies business.
Ultimately, this report turns on a single question: did the supply problems fade as quickly as management promised? A visible rebound in data center margins alongside healthy shipments would revive the thesis that record demand translates into record profits. Another quarter of mid-teens margins would suggest the bottleneck lies in Modine's own execution, not its order book.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-21 | |
| Oct-01 | |
| Sep-23 | |
| Sep-14 | |
| Sep-10 | |
| Aug-21 | |
| Aug-21 | |
| Aug-21 | |
| Jul-29 | |
| Jul-29 | |
| Jul-28 | |
| Jul-20 | |
| Jul-16 | |
| Jul-13 |
