Jack Henry's Cautious Margin Guide Faces First Test As Record Bookings Meet Cost Headwinds
Jack Henry & Associates closed its last fiscal year sounding as confident as it has in years, with record sales, a 20-plus-year high in competitive core wins and a third straight year of margin expansion well beyond its initial target. It then set a deliberately modest bar for fiscal 2027, guiding to just 20 to 40 basis points of non-GAAP margin expansion after delivering 92 basis points. The fiscal first-quarter report, due after the close on November 3, is the first real look at whether that reset was prudence or a genuine slowdown in operating leverage.
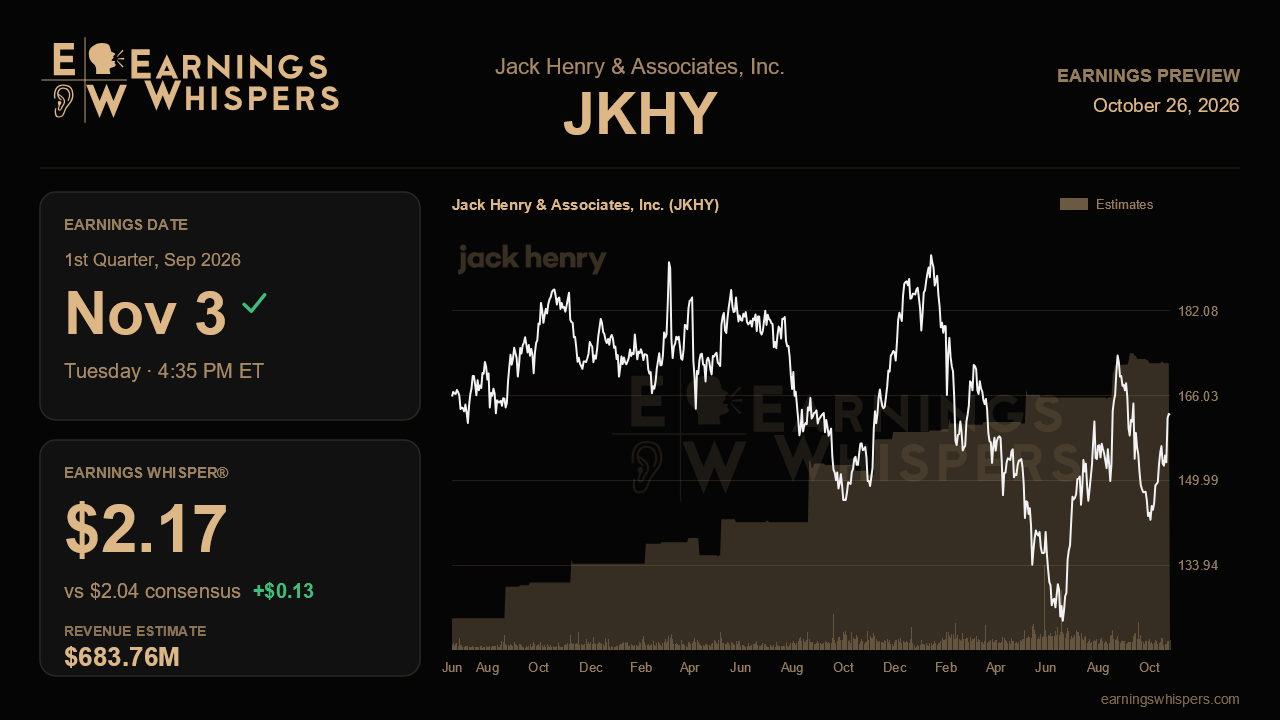
The Street expects earnings of $2.04 per share on revenue of $683.8 million, up 3.6% and 6.1% respectively from a year ago. That is modest growth by Jack Henry's standards, and it is meant to be. Management warned that first-quarter revenue would land slightly below the low end of its full-year growth range because its Connect conference shifts into the second quarter, moving roughly a point of growth with it. The first half also carries known cost pressure from self-insured medical expenses returning to normal levels and heavier spending on cybersecurity, frontier-model defenses and data-center consolidation. Against last year's unusually rich 27.2% first-quarter margin, the comparison is tough. The Earnings Whisper of $2.17 sits meaningfully above consensus, suggesting some investors expect the company's habit of beating cost targets to show up again.
The more telling comparison is annual. Jack Henry guided fiscal 2027 earnings to $7.33 to $7.38 per share, yet consensus sits at $7.11, well below the bottom of that range. Revenue consensus of $2.68 billion, by contrast, rests near the top of the company's $2.659 billion to $2.684 billion outlook. Analysts are effectively accepting management's top line while doubting its profit math. A first quarter that holds margins better than feared would pressure the Street to close that gap, while one that confirms heavy early cost absorption would vindicate the skeptics, at least until the second half, when management expects comparisons to ease.
Beyond the margin line, the quarter needs to show that sales momentum carried over. Last year's win tally built slowly, with only four competitive core wins in the first quarter before reaching 58 for the year, and management guided to 58 to 65 this year while noting it was already running ahead of the prior year's early pace. Evidence of continued up-market wins, a high trifecta attach rate across core, digital and card, and progress on newer offerings such as Tap-to-Local, Rapid Transfers and Treasury would support the narrative. Early signs from the newer catalysts matter too, including the first Banno digital deals outside the core base, the deposit-only cloud core moving into general availability and the planned stablecoin integration. On the risk side, Payments growth has lagged its historical algorithm and credit union RFP activity has thinned, so further softness there would dent the growth story. Deconversion revenue, which swung results last quarter, remains a wild card for both earnings and cash flow.
Sentiment has cooled noticeably, with the bullish reading falling to 21.5% from 44.4% ahead of the prior report. The stock has essentially tracked the S&P 500 since then, slipping 0.9% against the index's 0.7% decline, and at $162.35 it sits in the upper half of its post-earnings range, roughly 7% below the $174.99 high. That leaves room to move either way without a crowded bullish setup.
The central question is whether management's 20 to 40 basis point margin outlook is truly a floor. Management signaled it was cautiously optimistic about lifting that range, and investors have watched it raise margin guidance three times in a single year before. If first-quarter costs come in below plan while bookings stay strong, the gap between consensus and guidance becomes hard to justify. If the first-half headwinds bite harder than expected, the Street's caution will look well placed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-23 | |
| Oct-22 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-05 | |
| Oct-05 | |
| Sep-24 | |
| Sep-21 | |
| Sep-15 | |
| Sep-15 |
