Itau Unibanco Faces A Steady-Earnings Test As Shares Slide Toward Range Lows
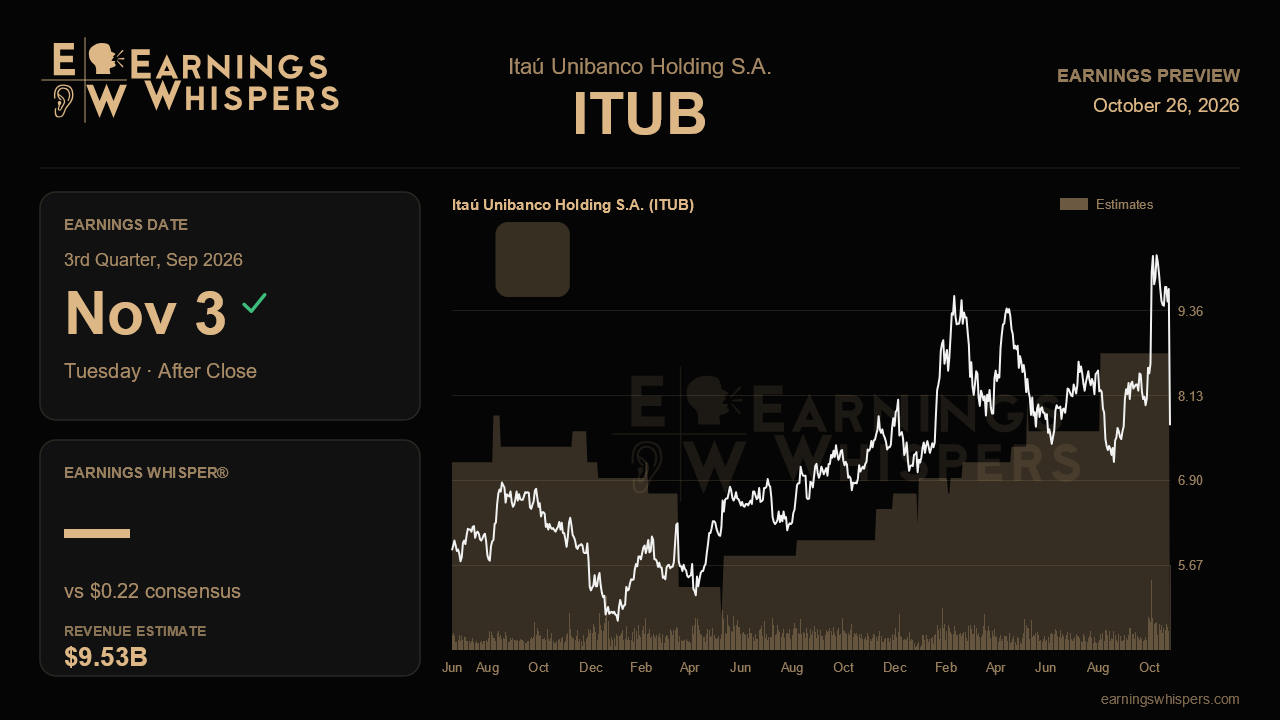
Itaú Unibanco heads into its third-quarter report with an odd disconnect. Analysts expect the bank to keep grinding out higher profits, yet the stock has dropped 9.3% since its last report while the S&P 500 edged up 0.6%. That gap of nearly ten percentage points suggests the market is pricing in something the earnings estimates are not. When the results land after the close on November 3, the question is whether steady earnings can win back a skeptical market.
The consensus calls for earnings of $0.22 per share, up from $0.21 last quarter and 15.8% above the $0.19 earned a year ago. That is solid double-digit growth for a large, mature lender, and it extends a pattern of incremental sequential gains. The revenue picture looks alarming at first glance. Forecasts of $9.53 billion would mark a 46.7% drop from the $17.88 billion reported in the year-ago quarter. That figure needs context. Revenue estimates are essentially flat with last quarter's $9.50 billion, and profits are expected to rise. Those two facts together point to a change in how the top line is being measured or compared, not a business that has been cut in half. The sequential trend is the more useful yardstick, and it describes a stable franchise rather than a shrinking one.
Management has offered no fresh formal outlook to anchor these numbers. That puts more weight on the report itself to show where the bank's earnings power is heading. For a lender of Itaú's size, the drivers that usually decide whether a quarter beats or disappoints are loan growth, the margin earned on that lending, credit costs, and expense discipline. A one-cent sequential improvement leaves little room for error. Earnings could come in at or above $0.22 with clean credit trends and steady fee income. That would support the view that the bank is compounding earnings in a measured way. A rise in provisions or flat revenue paired with higher costs would be harder to dismiss. Because results are translated into dollars for ADR holders, currency swings can also move the reported figure regardless of how the underlying business performed.
Sentiment has improved even as the share price has weakened. The current reading of 15.4% bullish is well above the 4.6% recorded ahead of the prior report. It is still modest in absolute terms, but it suggests some investors see the pullback as an opportunity rather than a warning. That optimism has not yet shown up in the stock. At $7.70, the shares sit in the lower portion of a wide post-earnings range that stretches from $7.16 to $10.20. They are also trading near the bottom of last quarter's tighter $7.39 to $8.76 band. The wider swings point to rising volatility, and the stock is nowhere near challenging its recent high.
That setup gives the report an unusual balance of risk. Expectations embedded in the price appear subdued, while the earnings bar itself is clear and achievable. A clean quarter that confirms steady sequential earnings growth and shows no deterioration in credit could narrow the gap between the fundamentals and the share price. The central issue is whether Itaú can show that its profit growth is durable and high in quality. A result built on stable revenue, contained credit costs and controlled expenses would keep the narrative of quiet, reliable compounding intact. Anything that suggests that consistency is slipping would give the recent selling fresh justification.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 |
Itaú Unibanco gains full ownership of AI startup NeoSpace for $589m
ITUB
Retail Banker International
|
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Oct-02 | |
| Sep-16 | |
| Sep-07 | |
| Aug-24 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-05 | |
| Aug-04 |
